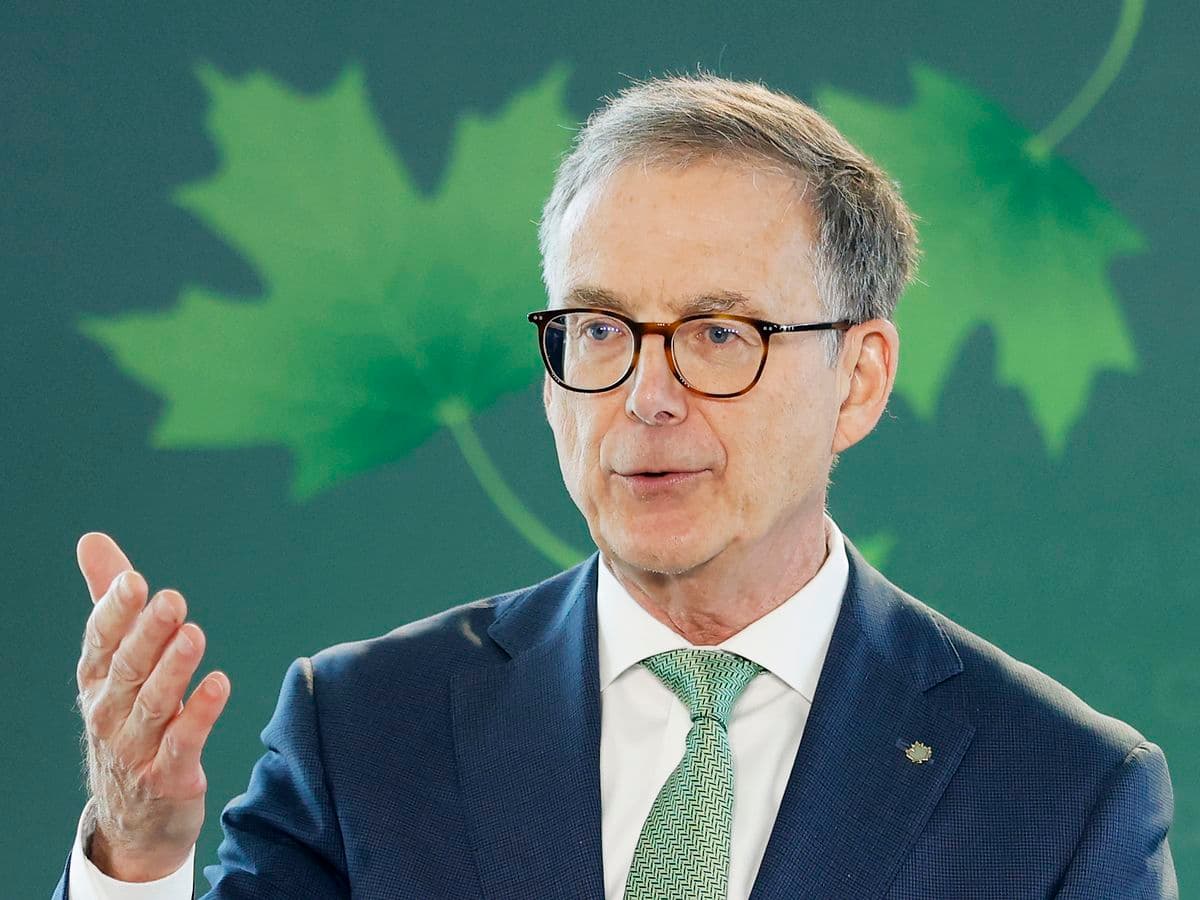
Macklem is worried that headline inflation has been around 3% and that the longer this is sustained, the greater the risks
It is astounding that the markets are pricing in a rate hike by the Bank of Canada next week as a virtual certainty and not just that, but a two-in-three chance of another move in December, so Merry Christmas to anyone looking to buy a home or car.
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman, and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account.
- Share your thoughts and join the conversation in the comments.
- Enjoy additional articles per month.
- Get email updates from your favourite authors.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account
- Share your thoughts and join the conversation in the comments
- Enjoy additional articles per month
- Get email updates from your favourite authors
Sign In or Create an Account
All of this repricing is not coming out of the blue, but rather reflects a distinctive hawkish tone of late coming from governor Tiff Macklem. I can understand the reasons why, but I don’t agree with them, nor do I support a rate hike right now given the fragile state of the Canadian economy and the nature of this statistical inflation, which comes from a global supply shock as opposed to any homegrown demand pressures — a supply shock I see as more of a deflationary squeeze on real personal incomes and profit margins than anything else.
Look at the domestic economy. A one per cent trend in real gross domestic product (GDP), which isn’t a recession but is still pathetically weak, plus the economy has lost more than 40,000 jobs this year, the housing market is in complete disarray, there’s a flat trend in manufacturing activity and there’s a contraction in the residential real estate sector.
SUBSCRIBER EXCLUSIVE: FP West: Energy Insider brings you behind the oilpatch’s closed doors with exclusive insights from insiders every Wednesday morning.
By signing up you consent to receive the above newsletter from Postmedia Network Inc.
A welcome email is on its way. If you don't see it, please check your junk folder.
The next issue of FP West: Energy Insider will soon be in your inbox.
We encountered an issue signing you up. Please try again
All the inflation is one thing: gasoline prices, which have skyrocketed 28 per cent over the past year. The 93 per cent share of the consumer price index (CPI) excluding energy is running right in line with the central bank’s two per cent target. Virtually every core inflation measure is at or below two per cent.
But Macklem is worried that headline inflation has been around three per cent for three straight months and that the longer this is sustained, the greater the risks will be of a more generalized spillover. The problem is that there is no evidence this is happening after eight months of the United States-Iran conflict.
The Bank of Canada has no control over imported inflation from high and rising energy costs; chasing headline inflation now in the context of a one-trick pony is nothing more than chasing prices at the pump, so we should ask the question of the appropriateness of targeting something completely out of your control.
If this was inflation driven by an overheated economy, that would be one thing, but that’s not what we have on our hands currently. The pace of economic activity is expanding below its potential, as anemic as supply dynamics are, given the collapse in population growth.
The Bank of Canada and most of Bay Street had a conniption earlier this week with the release of the central bank’s survey of consumer expectations because five-year inflation views rose to a four-year high, even though this metric has a very limited sample size, has a single cycle under its belt in its brief history and has absolutely no leading properties.
But it was this metric that tipped the balance for most Bay Street economic houses to shift their call for rate hikes. Bizarre.
Meanwhile, the proof of the pudding is in the eating. Not just no acceleration in core prices, but wage growth has decelerated sharply, to 2.3 per cent year over year now versus 3.3 per cent a year ago. This should not be lost on the central bank: when nominal wage growth slows to this extent, it represents the hallmark of widening resource slack in the labour market.
Surely, it cannot be lost on policymakers that job vacancies have been flat now for seven consecutive months — in other words, labour demand has lost vitality. And there is no inflation stability without the labour market playing along, as it did for that 18-month wage-price spiral in 2021 and 2022, when the economy reopened from the pandemic and the labour market was on steroids.
Labour does not have any power today and that is a critical difference between now and then. Take a look at collective bargaining agreements, and they are consistently showing a stagnant three per cent average annual trend over the life of these contracts (and without cost-of-living-adjustment clauses). That, my friends, is perfectly consistent with a two per cent inflation outlook, with or without the energy price shock and any spillover to airfares, delivery services or food.
Is the name of the game for the Bank of Canada to create the conditions for deflation in the parts of the economy not linked to energy to bring headline inflation to the midpoint of its one per cent to three per cent target? If so, it will be the economy that ends up being the sacrificial lamb in this senseless fight against inflation that has zero to do with the state of domestic demand.
Global supply-induced inflation shocks that hit the wall in the labour market, which is the current and prospective backdrop, will only lead to contraction in real incomes and, with a lag, a contraction in real consumer spending, which accounts for around 60 per cent of the country’s economic base.
By piling on this cost shock with rate hikes, the recession that we did not get when we were supposed to back in 2021 and 2022 will emerge as a primary risk for 2027, and that will come as a big surprise to most people on Bay Street (and Wall Street) who have been led to believe that recessions are relics of the past and that artificial intelligence has repealed the business cycle — the same narratives I was hearing in the late 1990s around the internet.
David Rosenberg is founder and president of independent research firm Rosenberg Research & Associates Inc. To receive more of David Rosenberg’s insights and analysis, you can sign up for a complimentary, one-month trial on the Rosenberg Research website.
Join the Conversation
This website uses cookies to personalize your content (including ads), and allows us to analyze our traffic. Read more about cookies here. By continuing to use our site, you agree to our Terms of Use and Privacy Policy.