Theo Newbegin cuts a wiry silhouette striding between towers of peaches and pears in the echoing vastness of the SPC canning factory
in Victoria’s Shepparton. Newbegin’s weathered face and long, white beard may bear witness to his 67 years, but once he jumps behind the wheel of a forklift and whips around a labyrinth of palettes, readying them for loading onto a truck, the decades melt away. His right knee might bark at him occasionally, but his lightning-fast reflexes put younger workers to shame. “I don’t feel any different to how I was in my 40s,” he grins. “People ask if I go to the gym.”
Clocking in at 2.30pm for an eight-hour shift at the cannery is merely the second act of Newbegin’s working day. He’s already hammered out a full morning of roofing – a trade he’s been toiling at since age 17. Amid a tradie shortage, he’s in constant demand, particularly for his repair work on old-school hardwood rafters, which he says modern materials can’t match.
“Fixing an old hardwood roof gives you a real sense of satisfaction,” he beams. “These new radiata pine ones? You can bounce up and down on ’em.”
Between five kids, nine grandkids, and his wife Jenny – who’s still powering through full-time work as a medical receptionist at 65 – Newbegin appears to be hardwired for perpetual motion (“my dad worked ’til he was 75,” he shrugs). Forget fine dining, Pacific cruises or the latest high-tech baubles; the four motorbikes he dotes on like prized thoroughbreds are his single indulgence.
Newbegin is part of a fast-growing club of older Australians delaying retirement well beyond the expected finishing line of 67. Today, more than 760,000 Australians over 65 are in the workforce, the highest level since Australian Bureau of Statistics’ tracking began in 1995. “Twenty years ago, one in 10 men were working at age 70; today it’s one in four,” says Terry Rawnsley, director of planning and infrastructure economics at KPMG.
Over the two decades from 2003 to 2023, retirement rates among 65- to 69-year-old Australians plunged significantly, with women’s numbers dropping from 86 per cent to 66 per cent and men’s falling from 73 per cent to 61 per cent, according to the University of Melbourne’s most recent Household, Income and Labour Dynamics in Australia (HILDA) survey findings.
Why are Australians staying on the clock? Although many remain in the workforce seeking purpose and social connection, the underlying driver for most is just to pay the bills. Rawnsley reckons something bigger is brewing – a shift in how we actually see retirement.
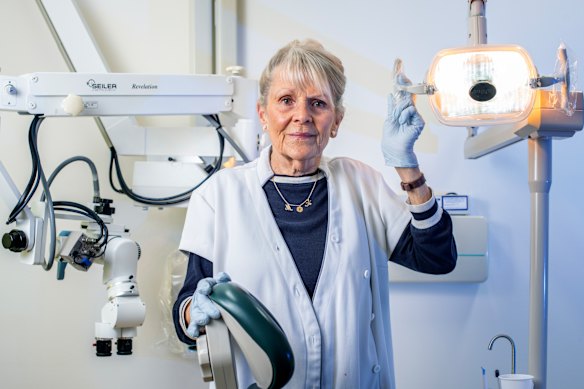
For Marion Wales, a 78-year-old dental nurse in Moss Vale in NSW, it’s the fact her superannuation coffers are running low, and she has an 81-year-old husband with limited mobility to support. “I can’t retire now because the pension isn’t covering our bills, and we don’t have enough in the super kitty,” she says. “I also want to have a decent life.”
For Anne Drane, a property manager for a real estate agency in south-western Sydney’s Liverpool, working three days a week is necessary to cover soaring private health insurance premiums and medical costs for a lung condition. But she also loves her job, and completed a financial counselling certificate only four years ago. “I like to keep busy, and also want to be able to afford to travel,” the 78-year-old enthuses.
For Shane Scully, 67, renting in Sydney while raising two teenage daughters makes working a financial necessity. “I don’t have an option. I need to keep working,” he says flatly. Yet, Scully, who designs outdoor classrooms and sensory gardens for public schools and special education units, finds his work deeply rewarding: “Turning a barren space into something that brings joy to the kids ... this makes it all worthwhile.”
For 75-year-old Brisbane-based educator Margaret Harrington, teaching has been a passion for more than 45 years – and something she continues out of a deep love for the calling rather than financial necessity. When she was made redundant from classroom teaching a decade ago, her students refused to let her go, telling her, “We know where you live and will come to you” – and she’s continuing to tutor privately from her home.
All of which has done nothing to dent the national sport of Boomer-bashing. It kicked off a few years back when Gen Z provocateurs leveraged the catchphrase “OK, Boomer” to slap down anything they pinned as peak smugness by their elders.
Boomer-bashing has turned into a minor publishing industry in recent years: from highbrow US takedowns like A Generation of Sociopaths by Bruce Cannon Gibney, and OK Boomer, Let’s Talk: How My Generation Got Left Behind, by Jill Filipovic, to Australian Fiona Wright’s satirical novel Kill Your Boomers, published earlier this year. Comedians and influencers alike have joined the pile-on, from Tom Ballard trying to turn a comedy festival crowd into a choir of Boomer-haters back in 2019 with “When the f--- are Baby Boomers going to die?” to US YouTuber Caleb Hammer griping to podcaster Joe Rogan in June that this generation “had the best housing market, college, jobs – they were set up for everything”.
Boomers, so the resentment story goes, hit the historical jackpot: dirt-cheap houses, free uni degrees, careers so stable they’d bore – or bring – a young gig economy worker to tears, and plump super payouts. And to top it all off, these silver-haired fat cats retired early, slapped a “SKI” (spend the kids’ inheritance) sticker on their shiny new LandCruiser, and flipped the bird at the young-uns as they hit the open road. What a bunch of self-serving parasites, right?
Except most of it is baloney.
The lucky generation? Sure, for the top tier of older Baby Boomers, the 20 per cent who control most of the overall wealth of their generation, but there is a vast and frequently overlooked gulf between the haves and have-nots. The Baby Boomers most at risk of financial stress are the “forever renters”, those locked out of home ownership and battling rental increases of nearly 40 per cent in real terms since the early 2000s, according to HILDA.
While at least 66 per cent of retirees own their homes outright, HILDA reports, an increasing number of younger ones – so-called “Generation Jones” (those born between 1954 and 1965) – are more likely to be still shackled to a mortgage. Vanguard’s 2026 How Australia Retires report found 24 per cent of Baby Boomers now expect to retire with a mortgage.
If you imagine most Boomers accumulated massive super payouts by the time they reached their 60s, think again. Super didn’t even exist until July 1992, when early Boomers were already in their 40s. Even then, it kicked off at just 3 per cent of earnings before taking more than a decade to crawl up to 9 per cent (it’s now 12 per cent). Without a place to call your own or a fat super nest egg to pay the rent, retirement in a pricey capital city with no income coming in apart from the government pension can be a fast track to poverty.
For University of Melbourne senior research fellow Dr Kyle Peyton, who is a fresh-faced 39, the most eye-opening statistic to emerge from the HILDA survey was a doubling between 2003 and 2023 in the number of retirees who are renting, now 12 per cent and rising. “The divide between Australians who own property and those who don’t is deeply concerning – not just for financial security, but for social cohesion,” he observes. “It’s a divide that exists within generations as well as between them.”
The new face of the housing crisis isn’t a struggling 20-something; it’s a single woman over 55 only one rental hike away from living in her car or couch-surfing. Having poured decades of sweat in and out of the workforce raising families and then caring for ageing parents, she can wind up with only a small super nest egg. “By the time they retire, Australian women typically have around one-third less superannuation than men,” notes Myra Hamilton, a sociologist at the University of Sydney. “While the super gap has narrowed in recent years, parity for women is still decades away at current rates. A quarter of grandparents – and it’s usually grandmothers – provide care for a child in a typical week, enabling their children to stay in the workforce.”
Much of the current wave of Boomer-bashing comes from young privileged commentators with no clue of what working-class life was really like in the 1960s, ’70s and ’80s. In 2023, Myra Hamilton, a Millennial, co-wrote a hard-hitting op-ed for this newspaper with her father Clive Hamilton, who recently retired from Charles Sturt University as professor of Public Ethics. “We now have a cohort of younger commentators furiously mining the data and cherry-picking the numbers to find new reasons to excoriate Baby Boomers,” the pair wrote.
Patricia Sparrow, CEO of COTA (Council on the Ageing), complains there are two deeply damaging media narratives on Boomers. “They’re either living on Easy Street or they’re frail and blocking up hospital beds. Both entirely ignore the huge social contribution Boomers are making.”
Don’t assume the Boomer-bashing doesn’t have a real-life impact. Myra Hamilton recalls that after delivering a talk in which she dismantled the myth that Boomers are universally comfortable and uncaring, an older woman approached her with tears welling in her eyes. ” ‘Thank you so much,” she said. “It hurts deeply to be branded selfish. I poured my life into raising my children, worked part-time, put everything on hold to care for my ageing parents, and I’m still pushing through work every day to cover my expenses. I love my children – yet society keeps accusing my generation of stealing their future.’ ”
While more and more older Australians are remaining in the workforce, participation rates are still below that of countries like Sweden, Japan and New Zealand, according to the OECD. And it’s been estimated by KPMG that boosting labour-force participation among experienced older workers could increase GDP by $29 billion.
Growing up in the decades after World War II, Boomers lived at a time of far greater austerity than today: a more threadbare welfare net, sparse workplace protections, widespread discrimination based on gender and colour, and zero universal healthcare. Gough Whitlam’s original Medibank didn’t arrive until July 1975, only to be scaled back months later when Malcolm Fraser came to power – leaving the country to wait until 1984 for Bob Hawke to finally establish the Medicare system we now take for granted.
Whitlam abolished tuition fees at universities in 1974, but it was middle-class kids, not working-class youth, who took advantage of it, insists Clive Hamilton. “The idea that Baby Boomers universally benefited from free higher education is a myth; university participation rates at that time were under 15 per cent,” he tells Good Weekend.
But life was so much cheaper back then, and everything’s outrageous today, right? Think again. For a reality check, let’s rewind to 1975, a year when the first Baby Boomers were in their late 20s, when flared jeans were de rigueur, lava lamps set the mood for disco hits like Lady Bump, and when a household purchase at a retail stalwart like Waltons or Grace Bros meant a Seriously Big Buy.
The family car? A popular vehicle like a Holden Kingswood sedan automatic would set you back about $4070, or a premium Cortina XL E, $4000, nearly two-thirds the median annual salary of the time ($6448). Contrast that with today’s family-sized SUVs: an MG ZS Vibe starts at just $22,990 – a mere third of today’s median annual salary of $74,000-78,000 – with Chinese hybrids like the Chery Tiggo 4 Urban and the BYD Atto 2 DM-1 starting at under $25,000.
Home entertainment? When colour television was launched in Australia on March 1, 1975 (“C-Day”), a Baird set (remember when the Brits manufactured TVs?) cost about $1300 – a staggering $11,667 in today’s dollars. Even the cheapest portable AWA-Thorn carried a price tag of $400, or $3700 now. TVs were so punishingly expensive that for many families, like mine, owning a TV wasn’t an option – we rented one for several years. Fast-forward to 2026: you can pick up a 55-inch LED Kogan smart TV for $449: a weekend impulse buy.
Whitegoods? In 1975, buying a $400 fridge or a $250 fully automated washing machine meant many months of disciplined saving or a dreaded lay-by: the equivalent of forking out $3500 to $4000 today. Even a humble Victa lawnmower carried the modern equivalent of a $1200 price tag. Now, a 4-stroke model is a steal for $424 at Bunnings. (It’s easy to forget how much globalisation and supply chains shifting to Asia have brought down prices.)
Groceries? Staples like milk, butter, eggs and bread cost way less now than in 1975 when adjusted for wages; chicken is much cheaper, red meat pricier, and while ice-cream and biscuits are cheaper, they’ve suffered shrinkflation (here’s looking at mini you, Chocolate Montes and Cornettos). Some items, such as washing powder, are marginally more expensive, but the prices of all plastic consumer goods (Glad Bags, Tupperware) have plummeted. Economists today may sweat over an inflation rate of 4 per cent, but in 1975, it was galloping at a wallet-shredding 15 per cent. Grocery prices were moving faster than a disco beat.
Dining out? Until the 1980s, your options were milk bars, hotel dining rooms, department-store cafeterias, tearooms and a handful of cafes in Sydney’s Potts Point or Melbourne’s St Kilda. Try asking a 1975 waiter for an oat milk piccolo whatevs, or quizzing them about the “provenance” of the sirloin or whether the peas are “hyper local” or not, and they’d most likely assume you were on a bad acid trip.
Clothing? Just about every item of casual and formal wear was far more expensive in 1975, when many garments were still manufactured locally, made to last and, in many working-class families, were passed down to younger siblings. When I recall to Anne Drane that my mother, a seamstress in a shirt factory, insisted on making most of my teenage shirts, much to my annoyance, she warms to the theme (“yes, we relied on our auntie to make all our clothes”). Today we’ve traded durable, locally made craftsmanship for “fast fashion” – a relentless tsunami of ultra-cheap, synthetic junk that winds up in landfill at the end of each season.
International travel? In 1975, a standard return economy airfare from Sydney to London on a major carrier like Qantas cost about $2300 – about a third of the median annual wage. Today, a return economy airfare on Qantas for the same trip costs much the same – starting at about $2200, less than three per cent of the median annual wage. Once largely the preserve of the well-heeled, international travel has become as mundane as booking an interstate bus trip.
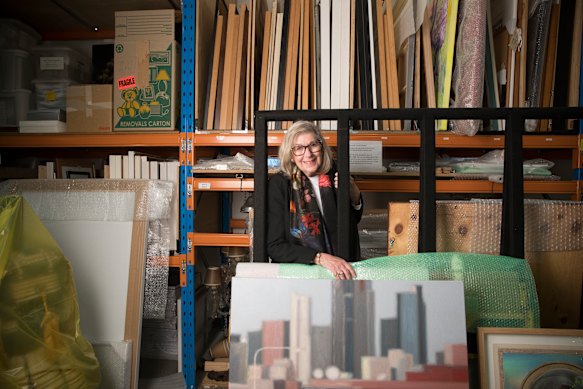
Margaret Betteridge, 73, who has worked as a curator at the City of Sydney for more than 30 years, recalls her first flight overseas to London in September 1975 to do a course in museum studies. “My salary was around $3000 per annum and the airfare to London cost a bit more than that,” she recalls. “Because it was so expensive, people who flew to Europe either saved up a long time, if they were young, or if they were old, tended to be very comfortable financially.”
Today’s acquisitive lifestyle, hypercharged by the internet’s endless digital bazaar, makes 1975 look positively spartan by comparison. We’re drowning in smartphones, iPads, Fitbits, Sonos, noise-cancelling headphones, flatpack furniture, disposable threads and – ugh! – plastic plants as decor. Consumerism didn’t truly hit its stride in Australia until the ’80s and ’90s, when tariff walls were brought down, ushering in the so-called “affluenza” era of cheap imports – and a mountain of landfill.
While financial strain is very real today, and risks getting much worse because of deteriorating international conditions, decades of lifestyle creep have turned what were once luxuries into non-negotiables. We might be skint, but do we really have to ditch our cafe breakfasts or streaming subscriptions?
Today’s great expectations were noted by many of the Boomers interviewed for this story. “This need for instant gratification – ‘We’re entitled to this now’ – didn’t exist a few decades ago,” muses Drane, who recounts a childhood in south-western Sydney’s Revesby in the 1950s marked by poverty and missed meals while her mother toiled at part-time jobs and her father struggled with post-war trauma and alcoholism.
There’s no denying, though, that Boomers were blessed with a big stroke of historical luck with housing. In 1975, a Sydney home cost about $28,000 – manageable at four times the average annual income. Today, that same dream requires $1.53 million, a suffocating 16 to 18 times the median annual salary. And yes, history has been generous to Boomers in terms of building equity in bricks-and-mortar over the decades. But this doesn’t mean they gamed the system: all they did was stay in their homes while market forces over time drove values through their roof.
Today’s housing market is brutally unfair for young people, but it’s pure piffle to imagine that getting a home loan or paying a mortgage were pieces of cake in decades past. Home loan interest rates didn’t just climb in the 1970s and ’80s – they throttled the household budget, rising from 10 per cent in 1975 to a punishing 17.5 per cent by 1990.
For my own working-class parents, both of whom worked in factories from the 1950s to the 1980s, home ownership was but a distant mirage for the entire time I was growing up. When I finally managed to help them buy a home, my monthly mortgage repayments became a high-wire act across a chasm of soaring interest rates that drove me to getting a second job until they began to fall after a year or so.
Lucky for them, they had a son: back in the 1950s, ‘60s, and ’70s, a single woman applying for a housing loan might as well have asked a bank manager for the keys to the vault. Banks routinely demanded a male “financial chaperone” – a father, brother, or partner – to sign off as guarantor, assuming the little lady would eventually resign to pop out babies anyway. Just ask Drane. When she sought to buy her first home as a 25-year-old single woman in the early 1970s, she had to jump through hoops, even though she was beginning her career in the Commonwealth Bank at the time. “To be considered, I got a second job and worked seven days a week for a year to meet their strict criteria,” she says.
It wasn’t much easier 10 years later for teacher Margaret Harrington, who applied for a loan in 1983. Even with tens of thousands of dollars in the bank from her divorce settlement, her request for a modest top-up to buy an apartment fell on deaf ears. The then 30-something had to go to five different banks before finally finding a lender willing to treat her as an independent borrower. “It was a terrible experience, made worse by bank managers making sexist remarks,” she recalls.
Back then, sexism was baked into the entire workplace. Drane recalls with absolute clarity being passed over for promotion after promotion for less-qualified males during her banking career in the 1970s. It wasn’t until the banks were deregulated in the 1980s and social attitudes began to change that those roadblocks started crashing down. By 1993, Drane didn’t just walk into a bank, hat in hand for a housing loan – she was manager of a suburban branch of the St George bank.
Younger Boomers and Gen Xers undoubtedly profited nicely off the Howard government’s 1999 tax perks, including capital gains cuts and boosts to negative gearing, which many economists believe unintentionally drained capital away from start-ups and innovation, a regrettable shift expertly exposed in Amy Remeikis’s recent book Where it All Went Wrong. “Howard turned housing from a place to live to a source of wealth,” she writes. But if you imagine Boomers monopolise the rentals and are to blame for your latest rent hike, sneak a peek at your landlord’s ID. ATO figures show that more than 73 per cent of landlords are Gen Xers or Millennials, with Boomers holding under 27 per cent (a number that COTA insists is now much lower, and set to crater, as older people offload investment properties and pass away).
If Gen Zers imagine they’re the first generation to face a raw deal, they may draw some comfort from the fact high home-ownership rates in Australia have been the historical exception, not the rule: from Federation until World War II, barely half the nation owned the roof over their heads. And home-ownership levels have remained pretty steady over the past 50 years (68 per cent in 1975 compared with 66 per cent today), although that may be under threat in the years to come.
And don’t fall for the line – often pushed by pro-development YIMBY cheerleaders – that senior Australians are selfish for wanting to stay in the family home, where they built their lives. Look around our suburbs, and you’ll see that all too often, Granny’s big, leafy backyard is bulldozed, not for a duplex or low-rise apartments, but for a brick-veneer mansion with a small paved courtyard. Forget the modest family cottage of 1975 – a sensible 130 to 150 square metres. Today’s typical Aussie house has bloated into a monstrous brick-veneer box of between 214 to 235 square metres, bursting with cinema rooms, multiple bathrooms, and empty bedrooms galore – all built to house tiny families that are half the size of those in the 1970s.
In our rapidly ageing nation, keeping senior Australians in the workforce, particularly in critical sectors like aged care, education and health, is no longer an option but an economic necessity. “Australia is shooting itself in the foot by treating willing and capable older workers like a financial liability rather than an economic lifeline,” argues Chris Grice, CEO of National Seniors Australia.
Championing the peak body’s “Let Pensioners Work” campaign, Grice believes the system actively discourages people over retirement age from staying in the workforce. For every dollar earned above $226 a fortnight for singles, the pension is slashed by 50 cents; for couples earning above $396 a fortnight, it reduces by 25 cents in the dollar. (Centrelink’s Work Bonus helps you keep more of your pension if you meet eligibility requirements, however.) Slapping seniors with fortnightly income reporting can also be a disincentive because of all the red tape, notes Grice.
Even finding a job when aged over 55 can be a marathon. ABS data shows it takes older jobseekers an average of 20 months to land a new role after losing one – more than double the nine months for younger applicants (15 to 54). COTA’s State of the Older Nation 2025 report reveals that 38 per cent of people over 50 have experienced some form of age discrimination and one in two recruiters show little or no openness to hiring workers 65 and over. “Ageism can be a significant deterrent for seniors trying to re-enter the workforce,” says COTA’s Sparrow.
Chris Grice says that institutional ageism remains rampant in recruitment and promotion, particularly in financial services, media and some areas of hospitality and sales. AI may be a double-edged sword, he says, enabling instant screening-out of older applicants, yet also simplifying software processes and helping seniors bridge technical skill gaps.
In a basic sense, Boomers are caught in a damned-if-you-work, damned-if-you-don’t Catch-22. Stick around in the office, and you’re a job-hoarder robbing eager young things of a career ladder; retire, and you’re a freeloading burden bleeding taxpayers dry. For many manual labourers and tradies, there isn’t even a choice: decades of hard physical toil make working past their 60s virtually impossible.
Painting Australia’s 3 million Baby Boomers as a uniform group of comfortable, home-owning Anglo-Saxons ignores a far more diverse and complex reality. It erases the waves of European migrants – 2 million in total between 1945 and 1965 – who spent decades breaking their backs in low-paid factory jobs, and the Indigenous Australians who have battled racism and job discrimination for their entire lives. “Boomers aren’t a single, homogeneous group,” says Sparrow. “The rich diversity of our broader community exists across every age bracket.”
Beneath all the anti-Boomer noise lies a fundamental truth that now seems long forgotten: these old-school trailblazers forged the very social freedoms we take for granted today. This was, after all, the generation of the counter-culture, one which transformed the rights for women, gay people and, to a degree, Indigenous Australians, as well as launching the environmental movement, says Clive Hamilton, whose 2016 book, What Do We Want? The Story of Protest in Australia, traces the grassroots history of these movements – and the high price some then-young people paid for their principles (arrests, fines, legal consequences). “Let’s be clear: only between 10 and 20 per cent of Baby Boomers were active participants, but the majority of young people supported their broader aims,” he says.
To this day, surveys consistently show Boomers outperforming Millennials and Gen Z when it comes to sustainable habits like recycling and curbing waste. The bitter irony? Many of the hard-won environmental protections and equal rights agendas that Boomers fought for are now under assault from populist demagogues – US President Donald Trump, the UK’s Reform leader Nigel Farage, One Nation’s Pauline Hanson – whose reactionary rhetoric is supercharged by social media algorithms.
A landmark University of Melbourne study recently exposed a dark rise in misogynistic attitudes in Australian classrooms: nearly a third of teenage boys believe gender equality has gone too far, with one in four agreeing violence is a fair response to feminism. It’s a sad spectre: impressionable young blokes taking life lessons from manosphere hucksters like brothers Andrew and Tristan Tate, now languishing on remand in a Miami, Florida prison, fighting extradition to the UK for charges of rape and human trafficking. (At his Miami bust, Andrew Tate looked less like a badass and more like a dancer at a Barry Manilow tribute, sporting an unbuttoned purple silk shirt, skin-tight Capri pants and pointed loafers, for which social media roasted him into oblivion.)
“If the Tate brothers had arrived in the 1960s and 1970s, they’d have been laughed off the stage,” chuckles Clive Hamilton. “The crowd would have been shouting, ‘Get off, you fools.’ The Tates are a reactionary backlash to the rights that Boomer women – and men – fought so hard to build.”
The young blokes pining for the good ol’ days of strict gender roles and “trad” wives remain amusingly blind to the crushing financial pressures placed on men of that era as sole breadwinners – and the battle-hardened grit of the women, forged by survival instincts in a man’s world (a theme vividly captured in Dorothy Hewett’s 1959 novel Bobbin Up). Had they been transplanted back to the factory floor of the 1950s and ’60s, these young keyboard warriors typing outrage from their family bedrooms would have been chewed up and spat out before smoko.
Besides, younger people can’t take much of the high ground with Boomers, when they’re about to become beneficiaries of their largesse. The country’s much-heralded, mega financial handover from Boomers to Gen Xers and Millennials is rapidly accelerating, notes KPMG’s Terry Rawnsley, as Boomers sell off larger homes, bankroll their offspring’s property ambitions and prepare to pass over a mammoth $3.5 trillion in the coming years.
Some weeks after our interview, Shane Scully messages me. He’d just been admitted to hospital for an angiogram, where doctors discovered an artery that was 95 per cent blocked. Surgeons inserted a large stent in the nick of time – dodging what cardiologists ominously call the “widowmaker”.
After the near-fatal scare, Scully was back at work within just over a week. He’s been prescribed meds and advised to walk more and adhere to a stricter diet, but the new regimen has inconveniently coincided with one of the most frantic times in his business.
For many working Boomers, the real daily grind isn’t the job itself but rather, looking after your health. “It’s a bitch getting old, I tell you,” reflects Scully.
Read more from Good Weekend magazine:
- ‘I had no idea about some of the issues’: The Aussies finding the downsides to downsizing
- Rachel spent five years ‘quiet quitting’ her marriage. Her husband didn’t see it coming
- She’s loved by millions of Australians but in her darkest moment, Magda Szubanski chose to be on her own
Get the best of Good Weekend delivered to your inbox every Saturday morning. Sign up for our newsletter.