Rising funding costs at South Korea's capital finance firms are pushing up interest burdens for used-car loan borrowers. KB Capital applied annual rates of 16% or higher to about a quarter of the used-car loans it extended recently, more than double the share from a year earlier. As cheaper loan products shrink, some capital firms are charging minimum rates in the 10% range even to borrowers with high credit scores.
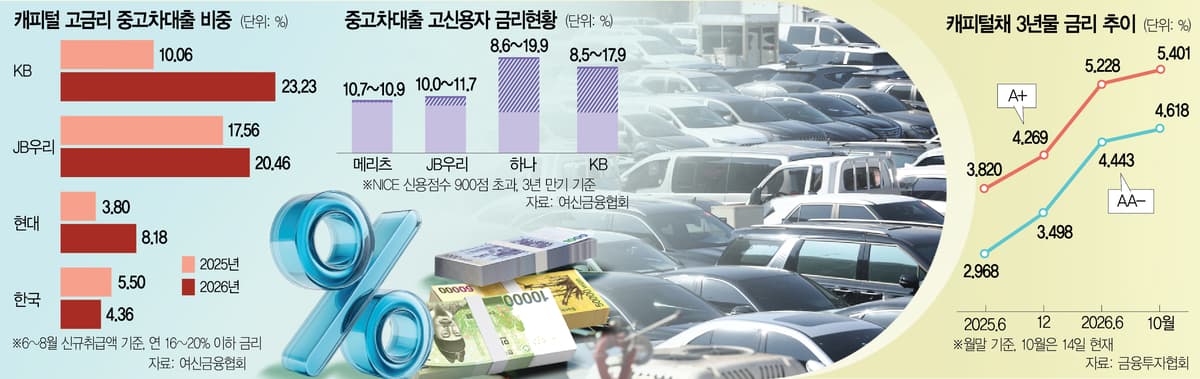
Among new used-car loans extended by KB Capital between June and August this year, 23.23% carried rates of 16% to 20%, according to financial industry data released on the 16th. That is up 13.17 percentage points from 10.06% a year earlier. At Hyundai Capital, the comparable share more than doubled to 8.18% from 3.80%. At JB Woori Capital, it rose to 20.46% from 17.56%.
The shift in borrower burden becomes clearer across a wider range of rate brackets. At KB Capital, the share of loans carrying rates of 12% or more rose to 42.13% in June through August this year from 27.74% in the same period last year, meaning more than four of every 10 new loans fell into that bracket. Hyundai Capital's share climbed to 21.87% from 15.48%, while Hana Capital's expanded to 12.78% from 0.88%.
As high-rate lending grew, the share of loans priced below 8% contracted. At KB Capital, it fell to 19.96% from 36.52%. A bracket that accounted for more than a third of new loans last year made up less than a fifth this year. Hyundai Capital's share declined to 41.53% from 53.14%. Hana Capital fell to 45.75% from 57.12%, and JB Woori Capital to 8.75% from 13.38%.
Behind the change are higher yields on bonds issued by specialized credit finance companies. Because capital firms cannot take deposits, they raise lending funds through bond issuance and other means, so their funding costs rise along with market rates. Yields on three-year AA- rated capital firm bonds rose to 4.4% at the end of June this year from 3.49% at the end of last year, then reached 4.6% on the 14th of this month, 1.11 percentage points above the level at the end of last year, according to the Korea Financial Investment Association. Yields on three-year A+ rated bonds also rose to 5.4% on the 14th from 4.269% at the end of last year.
With funding conditions deteriorating, capital firms have less room to attract customers with low rates. "Early this year, funding burdens were lighter than they are now, so we had room to offer products at low rates through our own promotions," an official at a capital firm said. "After those promotions ended, the rate burden borrowers feel also grew."

Average rates on used-car financing are also climbing. At KB Capital, the average rose 1.34 percentage points to 11.69% in August this year from 10.35% in June through August last year. Hyundai Capital's average rose to 9.35% from 8.45%, and JB Woori Capital's to 12.51% from 12.26%.
Top-tier borrowers are feeling the increase as well. In recent disclosures, the minimum rate on used-car financing for borrowers with NICE credit scores above 900 on 36-month terms was 10.7% at Meritz Capital and 10.0% at JB Woori Capital. Both companies offered products in the 4% range as recently as the first quarter of this year, making the rise in minimum rates substantial. Under the same conditions, Hana Capital applied a minimum of 8.6% and KB Capital 8.5%.
Financing costs are far from negligible for new-car buyers as well. For a Hyundai Motor Avante purchased with 30% of the vehicle price paid in cash and the balance repaid over 36 months, KB Capital's rates run from 7.0% to 7.7% and Hyundai Capital's from 5.4% to 8.5%. Hana Capital's range is 6.0% to 10.0% and Meritz Capital's 5.8% to 10.8%, putting the upper end above 10%.
Auto financing rates may face further upward pressure. Bank of Korea Governor Shin Hyun-song recently signaled an intent to continue a tightening stance, and costs are also expected to rise as existing bonds are refinanced. "When bonds issued earlier at low rates mature, firms have to raise the money again at higher rates," an official in the financial industry said. "Even if market rates do not rise further right away, the refinancing burden can show up in auto loan rates later."