Key Facts
- The Selic stands at 13.75% after September’s cut, so Thursday’s trade is about how far the easing cycle runs and which rate-sensitive shares catch the bid first.
- The National Monetary Council meets today, and any signal on inflation targets or credit rules will shape long-term rate expectations for local assets.
- IPCA-15 inflation data lands on Friday, but the pre-market will already be positioning for whether the mid-month print stays close to economists’ forecasts of about 0.4% to 0.5% for the month.
- Foreign positioning matters after a weak local session, with the real holding near R$5.02 and investors watching whether global dollar strength spills into Brazilian assets.
- Bradesco’s third-quarter earnings are due today after the close, giving the first clear read on credit quality and margins at a large private bank under the new Selic level.
- Prediction markets Polymarket traders put Flávio Bolsonaro’s chance of winning the 25 October runoff at 78.5% and Lula’s at 21.5%, as of 11:34 p.m. ET on Wednesday, 21 October.
Prediction markets · who wins the runoff
Implied chance of winning Brazil’s presidency on 25 October, from traders’ prices.
Polymarket
Flávio Bolsonaro 78.5% · Lula 21.5% (US$191 million traded)
Kalshi (regulated in the US by the CFTC)
Flávio Bolsonaro 80% · Lula 21%
As of 21 October, 11:20 pm ET (04:20 Lisbon), updated every 20 minutes. Prices are bets, not polls, and can move fast.
Why we show this: prediction markets turn real-money bets into a live probability that moves within minutes of the news, which is why investors, campaigns and newsrooms in the United States now follow them closely. We show them next to polls and official results, never instead of them.
Today’s Focus
The Selic stands at 13.75% after the Copom (central bank rate committee) cut it on 16 September. There is no rate meeting this week, so Thursday is about how aggressively investors price the next move on 3–4 November.
The National Monetary Council gathers today, and any tweak to the inflation target framework would ripple through rate futures and the real. Local traders are also looking ahead to Friday’s IPCA-15 inflation report, which will test whether the easing case still holds.
Bradesco’s third-quarter results offer a concrete read on how Brazil’s large private banks are managing credit risk while rates stay historically high. The real’s path and foreign appetite for local equities remain the swing factors at the open.
What matters today. Whether the easing trade extends through today’s National Monetary Council meeting and into Friday’s inflation data, or pauses as investors lock in gains after the Selic cut.
Brazil Election Data Room
Runoff poll average: Flávio Bolsonaro 51.1%, Lula 48.9%
33 national polls from 19 pollsters since 4 October, updated hourly. Every poll, free to download.
One-stop reference
Company Intelligence
Every listed company in Latin America — financials, ownership and structure for 1,450+ companies across 26 exchanges, in one place.
Today’s Economic Events
9 am BRT
Mexico — Mid-month Inflation Rate (Oct, YOY): consensus 3.6, previous 3.42
9 am BRT
Mexico — Mid-month Inflation Rate (Oct, MOM): consensus 0.37, previous 0.33
9 am BRT
Mexico — Mid-month Core Inflation Rate (Oct, MOM): consensus 0.18, previous 0.17
9 am BRT
Mexico — Unemployment Rate (Sep): consensus 3, previous 3
9 am BRT
Mexico — Core Inflation Rate (Oct): consensus 0.18, previous 0.17
9 am BRT
Mexico — Unemployment Rate n.s.a (Sep): consensus 3, previous 3
9 am BRT
Brazil — BCB National Monetary Council Meeting: no forecast published
9 am BRT
Mexico — Mid-month Core Inflation Rate (Oct, YOY): consensus 3.7, previous 3.79
9 am BRT
Mexico — Inflation Rate (Oct): consensus 0.37, previous 0.33
9:30 am BRT
United States — Initial Jobless Claims (week to Oct 17): consensus 200,000, previous 199,000
9:30 am BRT
United States — Continuing Jobless Claims (week to Oct 10): consensus 1.72 million, previous 1.71 million
9:30 am BRT
United States — Jobless Claims 4-Week Average: consensus 200,000, previous 198,500
12 pm BRT
Argentina — Consumer Confidence (Oct): consensus 41.5, previous 41.8
| Instrument | Level | Session |
|---|---|---|
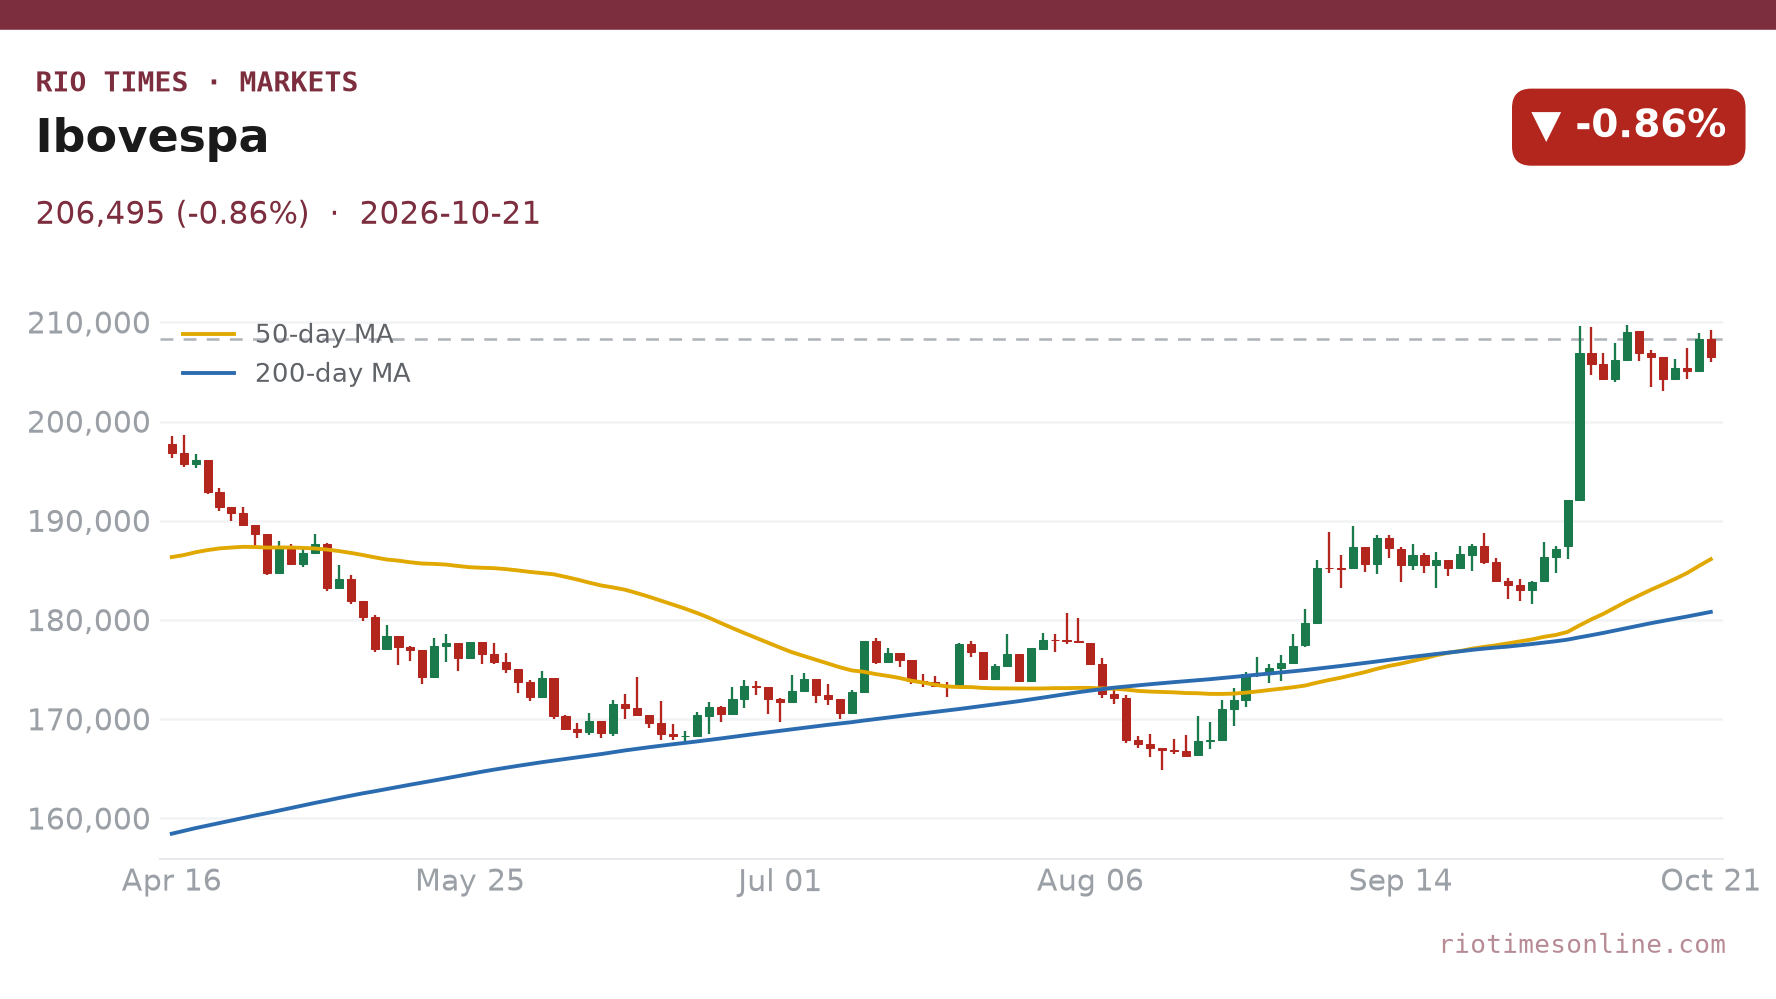
| Ibovespa (Brazil) | 206,495 | -0.86% |
| S&P 500 (US) | 7,757 | +0.58% |
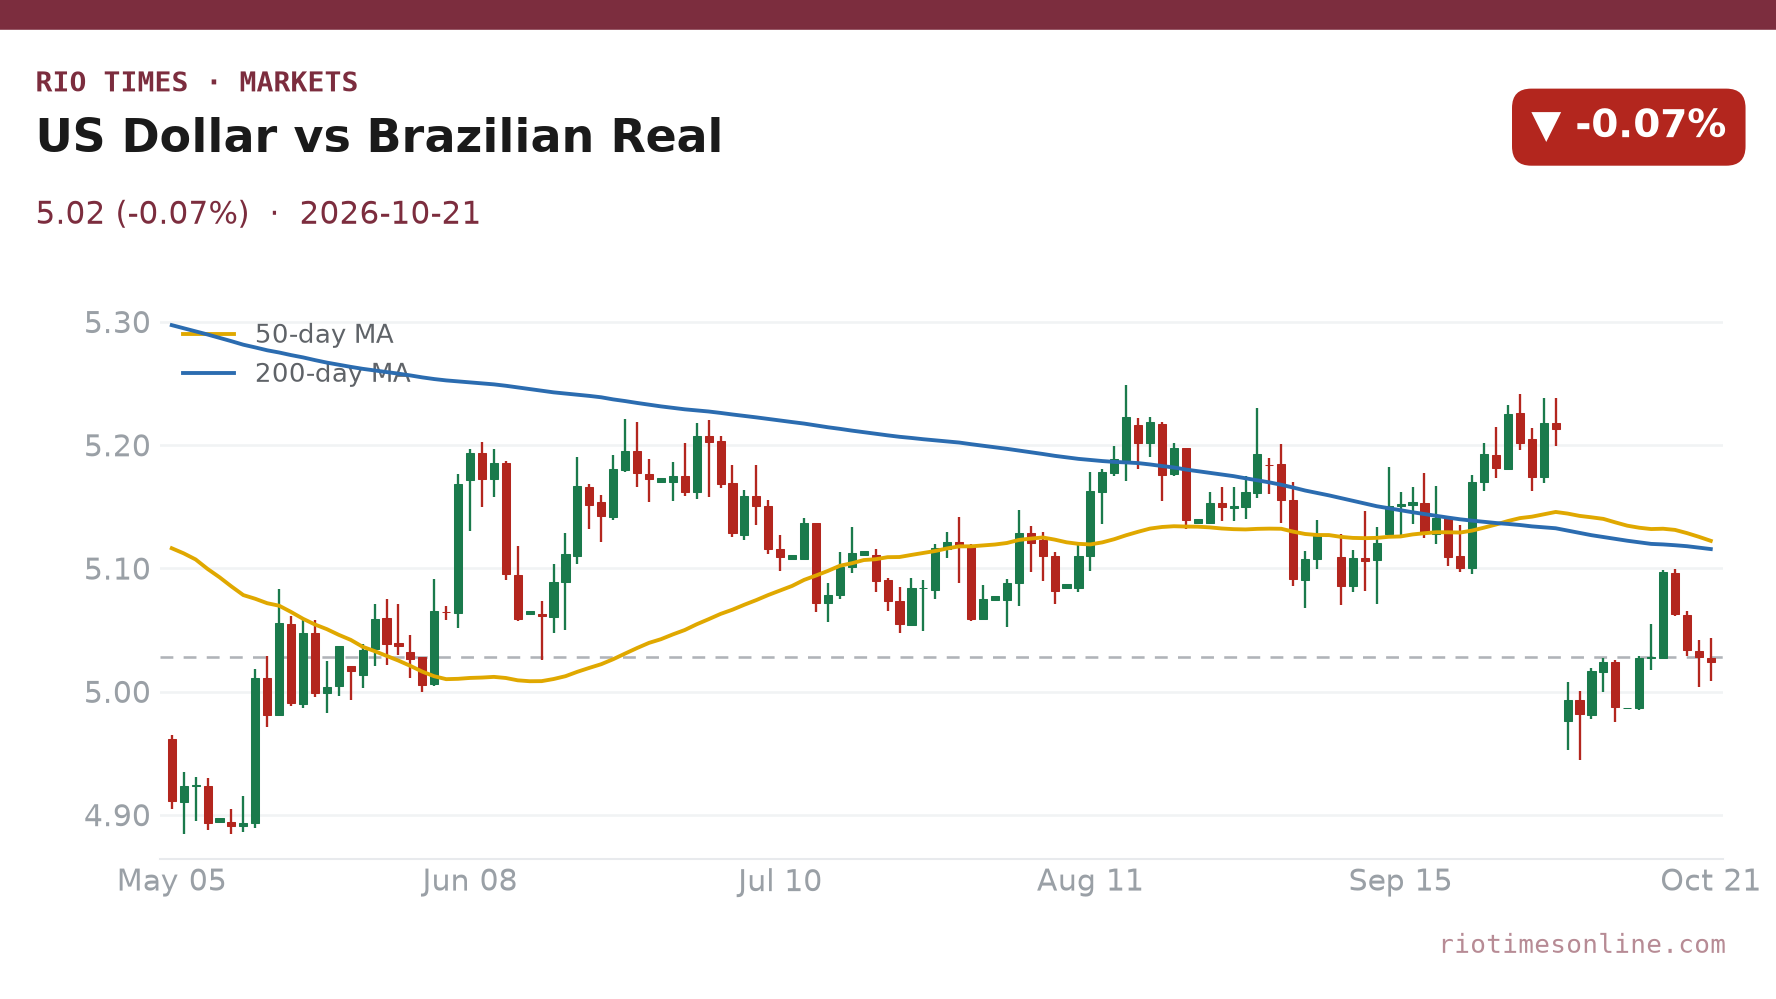
| USD/BRL | 5.0243 | -0.07% |
Source: market close, 21 October 2026.
01 The setup in one read
Brazil’s central bank cut the Selic to 13.75% on 16 September, its fifth straight cut, and there is no rate meeting this week. Thursday’s session is about what comes next: investors are pricing how much further the easing cycle can run.
The National Monetary Council meets today, a gathering that sets inflation targets and credit rules and can shift the long-term rate outlook in minutes. With IPCA-15 inflation data due Friday, the pre-market is already hedging whether price pressures stay contained enough to justify another cut in early November.
Bradesco’s third-quarter results land today and will show how one of Brazil’s largest private banks is handling credit quality and margins at these rate levels. Investors will also weigh Sunday’s presidential runoff before deciding how much risk to hold into the weekend.
Assessment — Easing momentum faces a credibility test MEDIUM
The Copom’s 25-basis-point cut in September keeps the easing cycle alive, so the path of least resistance should favour rate-sensitive Brazilian shares. But the National Monetary Council today and IPCA-15 on Friday are the next credibility checkpoints for the disinflation story. The variable to watch is whether the real stays near R$5.00 or breaks toward R$5.03 on any hawkish surprise from the council.
02 Where Brazil is set to open
| Instrument | Last close | Indicated | Watch today |
|---|---|---|---|
| Ibovespa | 206,495 | — | 209,067 record close as upside marker |
| USD/BRL | 5.0243 | — | 5.00 support and 5.03 resistance |
| Bradesco PN (BBDC4) | — | — | Q3 earnings and credit quality read |
The board shows the real little changed and the Ibovespa just below its record area, leaving room for a rebound if easing expectations hold. With no pre-market indication yet, the key levels are the 209,067 record close for the index and the psychological R$5.00 floor for the dollar.
A steadier real would support the easing trade in Brazilian equities, while a drift toward R$5.03 would signal caution among foreign investors ahead of the National Monetary Council headlines.
Live Market IntelligenceBrazil Morning Call — Live BoardInside: market breadth, the sector heatmap, currencies & rates, the Latin America scoreboard and the full instrument board.
Rio Times · Live Market Intelligence
Brazil Morning Call — Live Board
B3 · pre-open setup
Oct 22, 2026 · 00:38
Ibovespa · benchmark
206,495.23 -0.86%
L 167,142day rangeH 168,310
+21.85% over 12 months
Market breadth · 33 names
52% advancing
17 ▲ advancing16 declining ▼
Currencies, rates & key inputs
USD / BRL
5.16
+0.01%
EUR / BRL
5.95
+1.01%
Selic rate
14.00%
·
Brent crude
88.88
-0.03%
Iron ore
161.91
·
Sector heatmap · average move today
Materials
+1.58%
SUZB3, KLABIN
Mining
+1.16%
VALE3, CSNA3, GGBR4
Other
+0.76%
BRENT, WTI, IRON ORE, GOLD
Industrials
+0.20%
WEGE3, RENT3
Financials
-0.10%
ITUB4, BBDC4, BBAS3, B3SA3
Energy
-0.12%
PETR4, PRIO3
Consumer Staples
-0.25%
SLCE3, ABEV3
Utilities
-1.38%
ENEV3
Consumer Disc.
-1.98%
AZZA3, LREN3
Latin America scoreboard
IndexLastTodayStrength
IbovespaBrazil 206,495.23 -0.86%
S&P/BMV IPCMexico 69,583.42 +0.47%
S&P IPSAChile 10,985.55 +0.54%
S&P MERVALArgentina 3,017,221 —
MSCI COLCAPColombia 2,560.37 +1.07%
BVL S&P PerúPeru 59,870.67 -0.52%
Full instrument board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IBOV | 206,495.23 | -0.86% | +21.85% | 208,295.98 | 168,310 | 167,142 | — |
| USD/BRL | 5.16 | +0.01% | -5.13% | 5.16 | 5.18 | 5.14 | — |
| EUR/BRL | 5.95 | +1.01% | -5.83% | 5.89 | 5.98 | 5.94 | — |
| SELIC | 14.00% | — | — | — | — | — | |
| BRENT | 88.88 | -0.03% | +34.42% | 88.91 | 90.07 | 88.12 | 29,713 |
| WTI | 83.11 | -0.11% | +31.57% | 83.20 | 84.35 | 82.40 | 166,848 |
| IRON ORE | 161.91 | — | +58.10% | 161.91 | 161.91 | 1 | |
| GOLD | 4,461 | +1.78% | +33.20% | 4,383 | 4,503 | 4,421 | 139,824 |
| SILVER | 65.59 | +1.26% | +73.05% | 64.77 | 66.98 | 64.81 | 46,406 |
| LITHIUM | 75.20 | +1.47% | +62.95% | 74.11 | 75.80 | 75.08 | 89,275 |
| SOY | 1,184 | +3.20% | +17.05% | 1,148 | 1,199 | 1,168 | 163,179 |
| CORN | 480.50 | +10.02% | +29.34% | 436.75 | 480.75 | 459.50 | 341,248 |
| WHEAT | 655.00 | +3.93% | +29.70% | 630.25 | 657.75 | 631.50 | 128,793 |
| COFFEE | 317.25 | -5.51% | +0.67% | 335.75 | 321.20 | 313.55 | 21,747 |
| SUGAR | 16.43 | -1.79% | -3.01% | 16.73 | 17.11 | 16.22 | 171,992 |
| ORANGE JUICE | 138.55 | -0.47% | -45.38% | 139.20 | 141.05 | 137.50 | 703 |
| COTTON | 85.03 | +2.33% | +26.78% | 83.09 | 82.90 | 81.96 | 16,546 |
| BEEF | 223.60 | -3.93% | -5.18% | 232.75 | 226.40 | 223.00 | 16,126 |
| CATTLE | 339.10 | -3.16% | -1.82% | 350.17 | 345.50 | 338.60 | 10,164 |
| COCOA | 5,719 | +3.18% | -34.96% | 5,543 | 5,779 | 5,574 | 26,773 |
| PETR4 | 41.64 | -0.05% | +35.19% | 41.66 | 41.97 | 41.15 | 41,499,400 |
| VALE3 | 72.97 | +0.83% | +30.75% | 72.37 | 73.54 | 72.66 | 17,658,000 |
| SUZB3 | 41.33 | +2.35% | -23.55% | 40.38 | 41.48 | 40.35 | 3,914,900 |
| KLABIN | 17.69 | +0.80% | -2.95% | 17.55 | 17.74 | 17.48 | 2,057,400 |
| SLCE3 | 13.34 | +0.30% | -12.25% | 13.30 | 13.42 | 13.20 | 1,454,200 |
| ABEV3 | 14.89 | -0.80% | +21.91% | 15.01 | 15.07 | 14.81 | 16,453,100 |
| ITUB4 | 38.60 | -1.03% | +4.57% | 39.00 | 39.34 | 38.39 | 29,487,800 |
| BBDC4 | 16.85 | +0.36% | +3.50% | 16.79 | 16.90 | 16.67 | 19,416,900 |
| BBAS3 | 19.37 | +0.47% | +0.73% | 19.28 | 19.44 | 19.16 | 11,069,200 |
| B3SA3 | 14.26 | -0.21% | +12.73% | 14.29 | 14.47 | 14.11 | 33,037,800 |
| WEGE3 | 47.59 | +0.49% | +29.99% | 47.36 | 48.08 | 47.36 | 3,364,600 |
| PRIO3 | 59.14 | -0.19% | +50.67% | 59.25 | 59.81 | 58.74 | 3,325,600 |
| RENT3 | 34.68 | -0.09% | +0.84% | 34.71 | 34.96 | 34.35 | 7,979,100 |
| AZZA3 | 15.89 | -2.63% | -53.76% | 16.32 | 16.42 | 15.82 | 1,330,300 |
| CSNA3 | 4.30 | +0.47% | -42.65% | 4.28 | 4.41 | 4.26 | 10,076,100 |
| GGBR4 | 24.69 | +2.19% | +51.38% | 24.16 | 24.85 | 24.18 | 7,047,600 |
| ENEV3 | 24.21 | -1.38% | +70.49% | 24.55 | 24.64 | 23.99 | 9,297,000 |
| LREN3 | 11.87 | -1.33% | -28.65% | 12.03 | 12.17 | 11.83 | 9,683,300 |
Largest moves today
CORN 480.50 +10.02%
COFFEE 317.25 -5.51%
WHEAT 655.00 +3.93%
BEEF 223.60 -3.93%
SOY 1,184 +3.20%
COCOA 5,719 +3.18%
CATTLE 339.10 -3.16%
AZZA3 15.89 -2.63%
The session read
The Ibovespa eased 0.86%, with breadth positive — 17 of 33 names higher. Materials led, while Consumer Disc. lagged.
03 On the B3 radar today — National Monetary Council and Bradesco earnings
| Item | When | Why it matters |
|---|---|---|
| National Monetary Council meeting | — | Sets inflation targets and credit rules; shapes long-term rate expectations |
| Bradesco Q3 results | After close | Large private-bank read on credit quality, margins and high-rate effects |
The National Monetary Council is the day’s most consequential event for macro positioning, because any shift in the inflation target framework would change the entire rate outlook. Bradesco’s earnings give a micro read on how banks are managing under the new Selic level.
04 Copom and the macro backdrop
The Selic now sits at 13.75% after the 25-basis-point cut on 16 September, and the central bank’s next decision comes on 3–4 November. The market’s base case is that lower inflation and slower growth still justify further easing, even as external pressure from US rates lingers.
Today’s National Monetary Council meeting adds a layer of policy risk, since the council oversees the inflation target that guides the central bank’s decisions. If the council signals a lower or more flexible target, rate futures could rally and lift rate-sensitive shares; a conservative stance would do the opposite.
On Wednesday the EIA Crude Oil Stocks Change showed US crude inventories falling by 3.06 million barrels in the week to 16 October (previous draw 8.56 million, forecast 0.8 million), while the EIA Cushing Crude Oil Stocks Change was a build of 0.99 million barrels. Friday’s IPCA-15 report is the next hard data point, with the monthly estimate at 0.43% and the annual pace at 4.73%. A print below those levels would reinforce the easing trade, while a surprise would force a rethink before the November Copom vote.
05 Corporate stories to watch today
Bradesco’s third-quarter results are the main corporate event, offering a view of how a large private bank is handling credit quality and margins with the Selic at 13.75%. Investors will focus on loan-loss provisions and net interest income as a gauge of the broader earnings season.
06 The levels to watch at the open
For the Ibovespa, the record close at 209,067 is the first upside test if the easing trade extends, while holding above the 206,000 area keeps the rebound intact. A quick push toward that record would signal that foreign investors are re-engaging with Brazilian equities.
On the currency, the real’s near-term fate hinges on the R$5.00 to R$5.03 range. A break below R$5.00 would confirm confidence in Brazil’s rate path and support local shares; a drift above R$5.03 would warn that external dollar strength is overriding the domestic easing story.
Bradesco’s earnings could also set the tone for financial shares, which carry heavy weight in the Ibovespa. Strong results would anchor the index, while any sign of deteriorating credit quality would test the market’s appetite for rate-sensitive stocks.
07 What to watch
- National Monetary Council decision: Any change to inflation targets or credit rules will move rate futures, the real and bank shares instantly.
- Bradesco Q3 earnings: Credit quality and net interest income will gauge how banks cope with the Selic at 13.75%.
- Real’s R$5.00 floor: A break below R$5.00 would confirm easing confidence; a move toward R$5.03 signals caution.
- IPCA-15 pre-positioning: Traders will start hedging Friday’s inflation report today, especially in rate-sensitive sectors.
Background: Wheat Fund Falls 1.95% as Corn Fund Gains 0.67%.
Background: Steel Fund Dips 0.05% as CSN Falls 5.2%.
What Prediction Markets Say
Traders on Polymarket, a prediction market where people bet real money, put Flávio Bolsonaro’s chance of winning the 25 October runoff at 78.5 percent and Lula’s at 21.5 percent at 11:34 p.m. ET on Wednesday, 21 October. About US$191.2 million had been traded on that market.
These prices are bets by traders, not polls, and they can move within minutes of a debate or a new survey. The official result will come from Brazil’s electoral court, the TSE.
Why we show this: prediction markets turn real-money bets into a live probability that moves within minutes of the news, which is why investors, campaigns and newsrooms in the United States now follow them closely. We show them next to polls and official results, never instead of them.
Frequently Asked Questions
What did Copom decide in September?
On 16 September Brazil’s central bank cut the Selic benchmark rate by 25 basis points to 13.75%. There is no Copom meeting in October.
Why does the National Monetary Council meeting matter today?
The council sets Brazil’s inflation target and credit rules, so any signal there can change the long-term rate outlook and shift local asset prices.
When is the next Copom meeting?
The next Copom decision is scheduled for 3–4 November, and markets are already pricing how much further the easing cycle can run.
What is IPCA-15?
IPCA-15 is Brazil’s mid-month consumer inflation index, and Friday’s release will test whether price pressures remain contained enough to support more rate cuts.
Market data: RT
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Free every Sunday · Prediction markets
Want prediction market reports on your country?
One short email every Sunday, starting November 1: what the markets say about elections, currencies and policy in your country, with volumes and plain-English explanations.