
Key takeaways
- U.S. gross federal debt passed $40 trillion in August 2026; about $32.4 trillion of it is held by the public.
- Net interest on the debt now runs above $1 trillion a year and eats roughly 18.5% of federal revenue, a record.
- Heavy Treasury borrowing competes with private borrowers for capital (“crowding out”), adding upward pressure on interest rates, though the near-term rate story is still mostly inflation and the Fed.
- Freight feels it first: truck loans start around 7.9% to 8.9%, Class 8 orders are down year over year, small carriers are under strain, and warehouse development costs more to finance.
- Anyone planning a fleet replacement cycle or a long-term warehouse lease should model both Fed policy and the structural deficit.
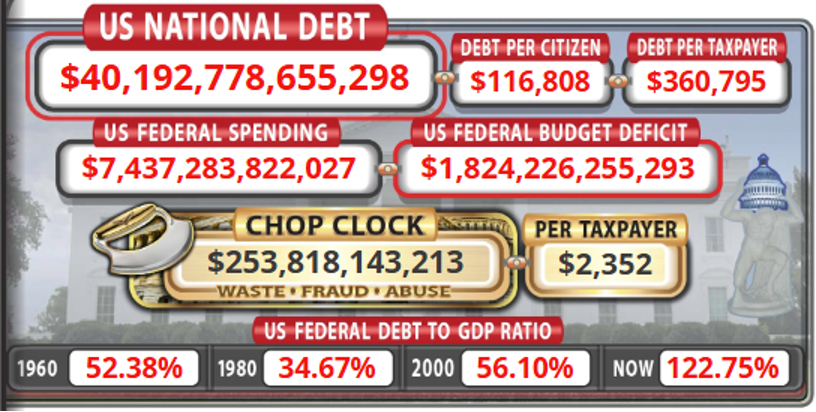
On last week’s Freightonomics show, we discussed CBO rule-of-thumb numbers on how much an increase in the interest rate (as shown by the Effective Federal Funds Rate) would impact the debt. I had in my mind publicly held debt when I said it was somewhere in the neighborhood of $34T. Turns out I transposed a couple numbers and was thinking 34.2 (getting old stinks). It’s actually $32.4T, which is still not good. I looked this morning to see what the total U.S. debt total currently is. That number is worse yet.
Source: usdebtclock.org, 09/23/2026
Gross federal debt crossed $40 trillion in mid-August 2026, months earlier than most forecasters had penciled in, as the Washington Post reported at the time, and it has held in that neighborhood since, touching $40.12 trillion in Treasury’s own daily debt-to-the-penny data as of September 21. Of that total, $32.4 trillion is debt held by the public and $7.7 trillion is intragovernmental, per Congress’ Joint Economic Committee Debt Dashboard. Debt held by the public alone is now running close to 100% of GDP (Debt Clock’s 122.75% is gross federal debt, public plus intragovernmental), and the Congressional Budget Office projects that ratio to reach 120% by 2036 and 175% within thirty years, surpassing the 1946 postwar record of 106% along the way. The debt has roughly doubled in under a decade.
Before we go further, we need to talk about scale. “Trillion” looks fine on paper, but it is difficult to wrap our heads around just how big that number is. To be perfectly honest, one almost needs a metaphor to understand the metaphor, but I’m going to try my best. I don’t want to bore you with too many conversions, but we need to establish some foundations for this. Let’s assume that each dollar of federal debt is one drop of water, 1/20th of a milliliter, or 1/100th of a teaspoon. On my kid’s medicine syringe, 1 tsp = 5 ml; so that math checks out. Following our earlier assumption, that means each teaspoon is a $100 bill of debt. According to World Aquatics, a long-run Olympic-sized swimming pool is 50m x 25m x 2.5m or about 164’1” x 82’ x 8’2”. This means it holds 3,125,000 liters of water, or 825,538 gallons. That means each pool holds 62.5 billion drops. For a federal debt of $40.1T, that means almost 642 pools. Imagine trying to swim that, much less drink that much. If you drank a gallon of water a day, it would take you 2,260 years to down all that. (See what I meant about the metaphor needing a metaphor?)
For freight and logistics, the headline number is not the worrying thing by itself. It’s what a debt stock this large, growing this fast, does to the price of capital, and freight is one of the most capital-intensive, most interest-rate-sensitive sectors in the economy.
Interest on the national debt now tops $1 trillion a year
One small bit of good news is that neither we nor the federal government need to drink that much pool water, at least not all at once. Federal debt gets bought and sold, comes due and gets reissued, on a constant basis. One credit card gets paid off, another gets issued. But, the feds have to pay interest on the money they borrow, just like everyone else. This cost is called “servicing” the debt. And, since the feds both borrow debt and gain interest on balances held (just like in your savings account), the reported numbers are the net of the two.
Net interest on the debt ran $1.02 trillion for the first eleven months of FY26, up 9% from $933 billion over the same span in FY25, and annualized interest costs crossed the $1 trillion mark in August, according to the Peterson Foundation’s interest tracker. Interest is now the second-largest line in the federal budget after Social Security, ahead of defense and Medicare individually and, on a 2025 full-year basis, ahead of the entire defense budget outright, Fortune reported this month. Interest payments now consume roughly 18.5% of federal revenue, above the prior record of 18.4% set in 1991, and CBO projects that share to reach 25% by 2036, with cumulative net interest over the next decade totaling $16.2 trillion. None of that money buys roads, ports, or anything else freight moves for. It is a pure transfer to whoever holds the debt.
How federal debt raises the cost of capital
The 10-year Treasury yield sits at 4.97% as of this week, near a 19-year high, with hawkish Fed commentary on further rate hikes doing a good part of the near-term work, per Trading Economics’ yield tracker. That’s a useful caveat before reaching for the debt as the sole explanation: a meaningful share of the current move is monetary policy responding to inflation, not fiscal policy responding to the deficit. It’s also worth noting the 30-year yield, at roughly 5%, is ordinary by the standards of the last fifty years: it was around 8% in 1991 and over 10% before that, the same Fortune piece notes. Rates this high aren’t historically unprecedented, even if they’re a shock relative to the 2010s.
That said, the deficit is doing its own work on the margin. FY26’s deficit is running around $1.9 to $2 trillion, or 5.8% of GDP, a level CBO itself flags as historically unusual with unemployment below 5%, a point the Peterson Foundation has made as well. That’s the textbook crowding-out setup: the Treasury needs buyers for an ever-larger volume of new debt, and it has to compete for the same pool of savings that would otherwise fund corporate bonds, mortgages, and equipment loans. As economist Ed Yardeni told Fortune, capital flowing into corporate bonds is capital not flowing into Treasuries, and Treasury yields have had to rise to clear the market. Treasury has also doubled its buyback operation size to $4 billion per transaction, a form of direct market management that analysts have described as blurring the line between routine cash management and yield control, which is itself a signal that debt absorption is not frictionless right now.
The academic version of this is the Penn Wharton Budget Model’s capital crowd-out estimates: in a partially open economy where foreign investors finance about 40% of new issuance, each additional trillion dollars of non-productive borrowing is estimated to reduce the private capital stock by roughly 0.65% to 0.78% by mid-century and GDP by 0.23% to 0.28%. Scale that to the trillions being added annually now, and the effect compounds, though it is partly cushioned as long as foreign capital keeps showing up to buy Treasuries.
Where higher interest rates show up in freight and trucking
Equipment financing. Trucking runs on borrowed capital for its rolling stock, and commercial truck loan rates are currently starting around 7.90% to 8.90% for well-qualified borrowers, per LendingTree’s lender survey. That rate environment is a direct pass-through of the Treasury curve plus a lender’s margin. It shows up in the order books: preliminary Class 8 net orders for August 2026 came in around 13,000 to 13,200 units, down 14% to 19% year over year, the eighth straight year-over-year decline, and well below the ten-year average of roughly 23,100 units, Commercial Carrier Journal reported. FTR’s Dan Moyer points to fleets extending truck lifespans and absorbing higher maintenance costs rather than replacing equipment, with high interest rates cited as one factor among several, alongside tariff uncertainty and the 2027 EPA NOx standard. Financing cost isn’t the only story here, but it’s a real one.
Small-carrier attrition. More than twenty trucking and logistics firms filed for bankruptcy in May 2026 alone, FreightWaves reported. The primary drivers FreightWaves points to are erratic demand and elevated operating costs, fuel chief among them, plus margins that stay thin even when spot rates rise, rather than financing costs specifically. But for the segment of the industry running on leased or financed equipment, a higher cost of debt is a background pressure that compounds every other stress carriers are already under, even where it isn’t the headline cause.
Warehouse and DC development. Industrial building loan rates were around 6.58% as of June 2026, per SelectCommercial, and industrial bridge loans are running 7.5% to 9.5% this year, according to PeerSense. That raises the hurdle rate for new distribution center development at exactly the moment e-commerce and nearshoring are pushing demand for well-located industrial space. Slower new supply growth is a second-order effect worth watching for anyone modeling warehouse rents and network footprints over the next few years.
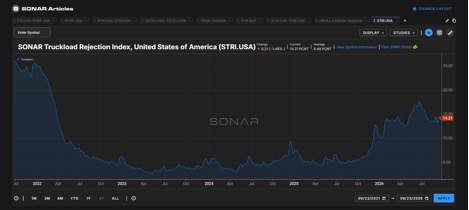
Current market backdrop. For context, SONAR’s national snapshot as of September 22 shows tender rejections (STRI) at 14.21, up about 1% week over week and up 5.6% over the past month; spot rates at $3.43 per mile, up 48.7% year over year; and contract rates at $2.66 per mile, up 15.7% year over year. Diesel, meanwhile, is at a record national average of $6.53 per gallon, but that’s mostly a geopolitical story (the Iran conflict, Russian refinery strikes, a Russian export ban, and historically low inventories), not a debt story, as Logistics Management’s coverage of the EIA data makes clear. It’s worth keeping that distinction clean: rising rates are being driven by a mix of tight capacity, fuel cost pass-through, and the financing backdrop described above, and it would be a mistake to attribute all of it to Washington’s borrowing.
The honest takeaway for carriers, shippers and brokers
The crowding-out case for freight isn’t that the debt is single-handedly setting truck loan rates or capping warehouse construction. It’s that a structurally larger, faster-growing debt load adds a persistent upward bias to the cost of capital across the economy, and freight, as one of the most financing-dependent, thin-margin sectors there is, feels that bias earlier and more acutely than most. The near-term rate story is still mostly about inflation and the Fed. The multi-decade story, with interest costs on a path to a quarter of federal revenue and debt-to-GDP heading well past the postwar record, is increasingly about the deficit itself. Anyone underwriting a fleet replacement cycle or a ten-year warehouse lease should be modeling both.
Frequently asked questions
How big is the U.S. national debt in 2026?
Gross federal debt passed $40 trillion in mid-August 2026 and stood at about $40.12 trillion on September 21, per Treasury’s Debt to the Penny data. About $32.4 trillion is debt held by the public and $7.7 trillion is intragovernmental.
How much does the federal government pay in interest on the debt?
Net interest ran $1.02 trillion in the first eleven months of FY26, up 9% from the same span in FY25, and annualized interest costs crossed $1 trillion in August. Interest now takes about 18.5% of federal revenue, and CBO projects that share to reach 25% by 2036.
What is crowding out, and how does it affect freight?
Crowding out happens when heavy government borrowing competes with private borrowers for the same pool of savings, pushing interest rates higher. Freight is one of the most capital-intensive, rate-sensitive sectors, so higher borrowing costs show up quickly in truck financing, equipment orders, carrier margins, and warehouse development.
Is the national debt the reason freight rates are rising?
Not primarily. As of September 22, SONAR data shows tender rejections (STRI) at 14.21 and spot rates up 48.7% year over year, driven by tight capacity, record diesel prices, and the financing backdrop. The debt acts as a persistent background pressure on the cost of capital rather than the direct cause of today’s rate moves.
Want to see how capacity, rates, and costs are moving in your lanes? Subscribe to SONAR for real-time freight market data.
The post How National Debt Affects Freight Costs and Financing appeared first on FreightWaves.