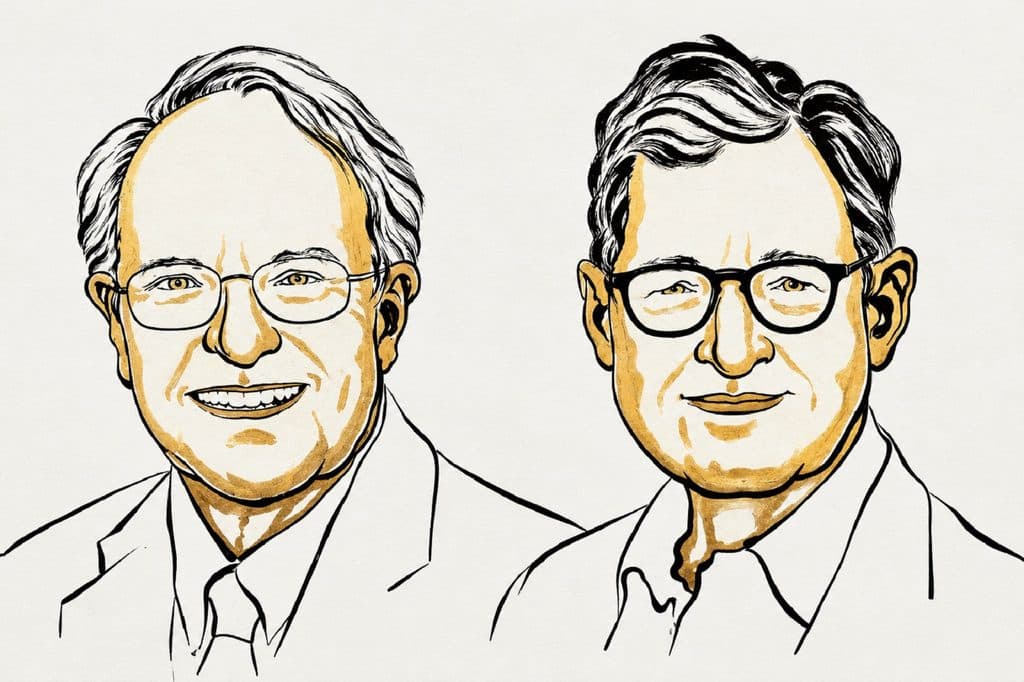
The Royal Swedish Academy of Sciences awarded the 2026 Nobel Prize in Economic Sciences in Memory of Alfred Nobel on Monday to American economists Robert E. Hall and Michael Woodford for their contributions to the microeconomic foundations of macroeconomic stabilization.
Their research has advanced understanding of how household and business decisions influence economic cycles and how governments and central banks can respond to crises.
The award recognizes decades of work that transformed the analysis of economic policy by demonstrating that stability depends on more than simply adjusting interest rates or increasing public spending.
It also requires understanding consumer and business expectations, anticipating their responses, and clearly communicating policy decisions. The two researchers will share a prize of 12 million Swedish kronor, equivalent to approximately US$1.2 million.
Robert E. Hall and Michael Woodford win the Nobel Prize in economics
Hall, born in 1943 in Palo Alto, California, is a professor at Stanford University. He earned his Ph.D. in economics from the Massachusetts Institute of Technology (MIT) in 1967 and built an academic career focused on macroeconomics, consumption, economic growth, and household behavior. His research helped explain why people do not make spending decisions based solely on their current income, but also take their future economic prospects into account.
Woodford, born in 1955 in Chicopee, Massachusetts, is a professor at Columbia University in New York City. He earned his Ph.D. from MIT in 1983 and became one of the most influential figures in the study of modern monetary policy. His work deepened understanding of the relationship between central bank decisions, economic agents’ expectations, and the evolution of inflation and economic activity.
Although their research followed different paths, both economists helped establish a stronger theoretical foundation for policies aimed at moderating recessions and preventing economic expansions from leading to imbalances that are difficult to control.
A response to the limitations of traditional theories
The work of the two economists gained particular relevance after the oil crises of the 1970s, when Western economies experienced a combination of high inflation and unemployment known as stagflation. Traditional economic policy tools revealed their limitations, reigniting debate over governments’ ability to stabilize the economy without exacerbating other problems.
Keynesian theories had emphasized the importance of government intervention through public spending and interest rates to cushion economic fluctuations. Hall and Woodford helped renew this approach by incorporating more rigorous analysis of the individual decisions that collectively determine economic behavior.
The central idea is that households and businesses do not respond automatically to government measures. Their decisions depend on what they expect to happen to incomes, prices, borrowing costs, and economic conditions. As a result, a policy can produce outcomes different from those anticipated if authorities fail to account for how the people expected to respond to it will interpret the measure.
2026 economic sciences laureate Robert E. Hall’s hypothesis was that changes in consumption could not be predicted because they depend on new – and thus unpredictable – information.
Hall presented his results in an article in 1978, which was something of a eureka moment for research. His work became key to the development of modern research on consumption.
#NobelPrize
— The Nobel Prize (@NobelPrize) October 12, 2026
Expectations, a key tool for central banks
One of Woodford’s main contributions was demonstrating that central banks’ communication about their future decisions can have a decisive influence on the economy. If businesses and consumers understand what measures will be taken and trust them, they can adjust their decisions before changes in interest rates have fully taken effect.
This approach elevated the importance of so-called forward guidance, through which monetary authorities signal the likely course of their policy. The strategy became particularly important after the 2008 financial crisis, when interest rates approached zero and central banks had to turn to additional tools to stimulate economic activity.
Hall’s research, meanwhile, helped explain how expectations about future income shape current consumption. A family that considers an increase in income temporary may choose to save much of the additional money, while another that expects its economic circumstances to improve permanently will likely increase its spending. These differences are essential to assessing the impact of fiscal and monetary measures.
The Swedish Academy highlighted that the models developed by both researchers have improved policymakers’ ability to implement stabilization measures and respond to shocks such as energy crises or sudden changes in household consumption.
Their work does not eliminate uncertainty or guarantee that government and central bank decisions will always produce the expected results. However, it provides tools to anticipate how economic agents will respond and assess the consequences of public interventions more accurately.
With this recognition, Hall and Woodford join the ranks of economists whose research has helped shape contemporary economic policy.
Their combined contribution underscores a central conclusion: stabilizing an economy requires more than acting on its major indicators; it also requires understanding the individual decisions that determine those indicators and the expectations that shape the behavior of millions of people and businesses.