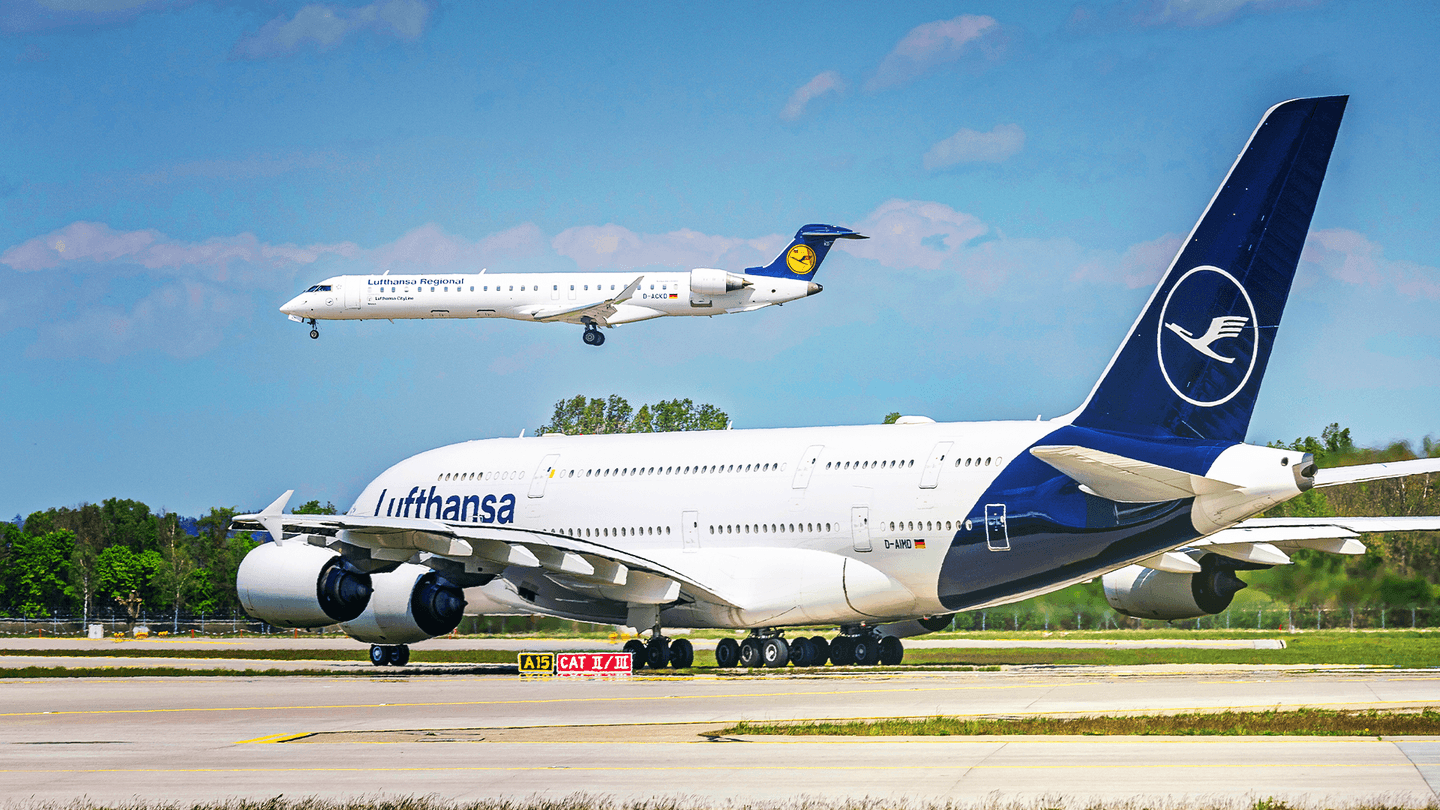
Most major European airline conglomerates aggressively concentrate operations into a single mega-airport to capture scale. The Lufthansa Group feels differently about this, splitting its main network across four central gateways in three countries. Its multi-hub structure deliberately disperses long-haul widebodies and regional traffic, rather than chasing absolute consolidation like many other groups do.
Managing this sprawling ecosystem all comes down to a balance of capacity allocation and yield protection between  Lufthansa, SWISS, and Austrian Airlines. This article takes a look at each of the key hubs, analyzing how the group coordinates
 Frankfurt Airport(FRA),
 Munich Airport(MUC), Zurich Airport(ZRH), and Vienna International Airport(VIE) as a unified system in the face of major infrastructure constraints and shifting economic pressures.
The Two Major Hubs Of Lufthansa
Lufthansa addresses its domestic network split by dividing its German positioning into two distinct operational tiers, operating FRA as the group's global mega-hub alongside MUC as its high-performing southern counterpart. FRA handles heavy corporate trunk routes and massive global freight logistics, while MUC targets streamlined transfer efficiency and high-yield regional wealth.
The divergence in their recovery trajectories highlights the operational pressures these German gateways face. As per Fraport, FRA handled 63.2 million passengers in 2025, marking a 2.6% increase from the previous year, though it remained roughly 10% below pre-pandemic levels. Meanwhile, MUC processed 43.4 million passengers, up 4.4% to reach 91% of its 2019 record of 47.9 million, with approximately 42% of those travelers connecting through its joint-venture Terminal 2 facility, according to Munich Airport. These scale disparities led the Lufthansa Group to intervene directly through its centralized Hub Steering Board, cutting short-haul capacity disproportionately across FRA and MUC for the summer 2026 schedule to counteract surging jet fuel costs.
Heavy congestion, strict night-flight caps, and rising operational costs at Germany's main gateways continue to squeeze short-haul margins. If even its largest German hubs face unprecedented problems, then how does the group protect its overall network yield?
Where Size Is Not So Important
Shifting operations across the Swiss border brings a distinctly different operational philosophy, where ZRH prioritizes high-yield density and connection efficiency over raw industrial scale. As SWISS's home base, the airport benefits from a wealthy national catchment area boosted by global banking, pharmaceuticals, and technology sectors. This premium-heavy demographic allows the national carrier to keep strong average fare yields that offset the structural disadvantages of operating within a high-cost European market.
Operational performance metrics reflect this strength, with ZRH handling a record 32.6 million passengers, marking a 4.5% increase and rising above pre-pandemic levels for the first time across a full operating year, as per 2025 figures from Zurich Airport. The infrastructure present supports this momentum through a compact, highly integrated terminal design that links directly to national rail networks. Such design efficiencies enable remarkably short minimum connection times, allowing transfer passengers to move between Schengen and non-Schengen gates with minimal friction and high schedule reliability.
Controlling these tight connection windows allows SWISS to feed high-value transfer traffic efficiently into its long-haul intercontinental network spanning North America, Asia, and Africa. At the same time, this high-yield engine operates under strict environmental regulations, including rigid night curfews and legally mandated noise abatement flight paths. These local constraints make schedule management far from straightforward, but they help the hub maintain peak financial performance without violating its strict operating boundaries.
The Perfect Location?
At the eastern edge of the group's operational map lies VIE, functioning as the dedicated home hub of Austrian Airlines. As noted by Air Cargo World, the airport provides an unmatched geographical advantage for short- and medium-haul feeder operations connecting Western Europe to destinations across the Balkans, Eastern Europe, and select Middle Eastern corridors. Austrian Airlines holds a strong market share at VIE, using the airfield to funnel regional traffic into its expanding long-haul network.
Official statistics from airport CEO Julian Jäger show that VIE set a new passenger record, reaching approximately 32.6 million travelers (precisely 32,559,115) in 2025, a 2.6% increase over the previous year. However, VIE expects passenger volumes to fall to around 30 million in 2026, mainly because low-cost airlines are cutting flights there. Despite facing near-term headwinds from budget carriers trimming capacity at the airport, VIE still has stable profitability from focusing heavily on regional feed and specialized connections.
The airport infrastructure features efficient pier layouts and modern passenger facilities designed to handle high volumes of connecting regional passengers smoothly. With targeted long-haul routes and a strong grip on Central and Eastern European feeder lanes, VIE is a prime example of what a mid-sized hub can be: one that can thrive within a major airline conglomerate by dominating a specific geographic corridor.
Cutting 20,000 Flights
Managing these massive European gateways alongside other key nodes means the Lufthansa Group must move away from isolated hub autonomy toward a unified, centralized operational system. The Lufthansa Group manages its hubs more as a single system, coordinating FRA, MUC, ZRH, and VIE alongside Brussels Airport(BRU) and Rome Fiumicino Airport(FCO) through a new Hub Steering Board that coordinates their schedules to maximize connections and avoid overlap. The conglomerate's various operating certificates are treated as a macro-network, allowing planners to allocate capacity where yield and demand justify deploying assets.
The tangible impact of this centralized oversight became evident when the group optimized its flight offerings for the summer 2026 schedule, cutting 20,000 unprofitable short-haul flights through October, as noted in Simple Flying reports. These capacity reductions fell mostly on FRA and MUC, while the group added flights in ZRH, VIE, and BRU. Jet fuel prices have doubled since the Iran conflict began, and rather than absorbing fuel penalties across every legacy route, the steering board redirected short-haul capacity cuts away from more resilient eastern and southern operations.
These group-wide adjustments demonstrate the core strength of a diversified multi-hub model under centralized direction. When macroeconomic pressures or soaring operational costs strike specific regions, the conglomerate possesses the structural flexibility to trim unprofitable flying in congested domestic markets and still preserve growth in high-yield or lower-cost feeder sectors.
What Is The Real Benefit Of This Hub System?
Maintaining four massive gateways across Central Europe provides the Lufthansa Group with an unmatched operational safety valve when any regional events disrupt air traffic flow. Operating across multiple jurisdictions and independent airport slots prevents systemic failure when single-hub carriers face severe ground strikes, adverse weather events, or air traffic control caps. The central Hub Steering Board's grounded operational oversight lets dispatchers dynamically reroute connecting passengers and reallocate aircraft rotations during irregular operations. When FRA or MUC encounters severe congestion or industrial action, traffic can be taken on or bypassed through ZRH or VIE, preserving high-yield transfer itineraries and protecting overall network punctuality.
As highlighted in analysis by Simple Flying, this level of structural redundancy is a core competitive advantage that protects against localized macro-shocks. By distributing capacity across diverse national markets rather than relying on a single mega-terminal, the conglomerate ensures that potential disruptions, such as regional air traffic control restrictions or operational constraints, do not end up becoming enterprise-wide paralysis.
Furthermore, this multi-hub flexibility underpins the group's ability to adjust capacity dynamically in response to fluctuating fuel costs and geopolitical tensions, such as the recent energy market volatility that saw jet fuel prices double. When operational expenses hit specific regional corridors, the centralized coordination framework lets network planners shift aircraft and re-optimize flight banks seamlessly. Ultimately, it means that the group can sustain stable operations across its broader ecosystem while protecting its core financial performance.
Will This System Live On?
The Lufthansa Group's multi-hub system shows how decentralized operations can thrive under unified central governance. By aligning FRA, MUC, ZRH, and VIE into a coordinated macro-network, the conglomerate balances industrial scale, high-yield corporate catchments, and regional feeder advantages. There is no need to compete blindly against one another, because these four pillars work in concert to defend Central Europe's skies against outside competition.
Will this system prevail in the long run? Much of the potential for this interconnected model's long-term success depends on how smoothly the group integrates modern aircraft cabins while absorbing ongoing infrastructure delays. Centralizing short- and medium-haul network planning, all while preserving localized hub strengths, allows the airline group to streamline costs without alienating regional passengers or losing valuable feed traffic.
The group will continue altering its network, building on the strategic trimming of 20,000 short-haul flights across its core hubs. Operating expenses are currently highly volatile for all airlines, especially for a group as large as the Lufthansa Group. Traffic recovery rates across FRA, capacity shifts at VIE, and centralized scheduling optimization will determine whether this multi-pillar model remains Europe's most resilient airline network strategy, or whether all the pillars will crumble under the intense pressure being exerted upon them.