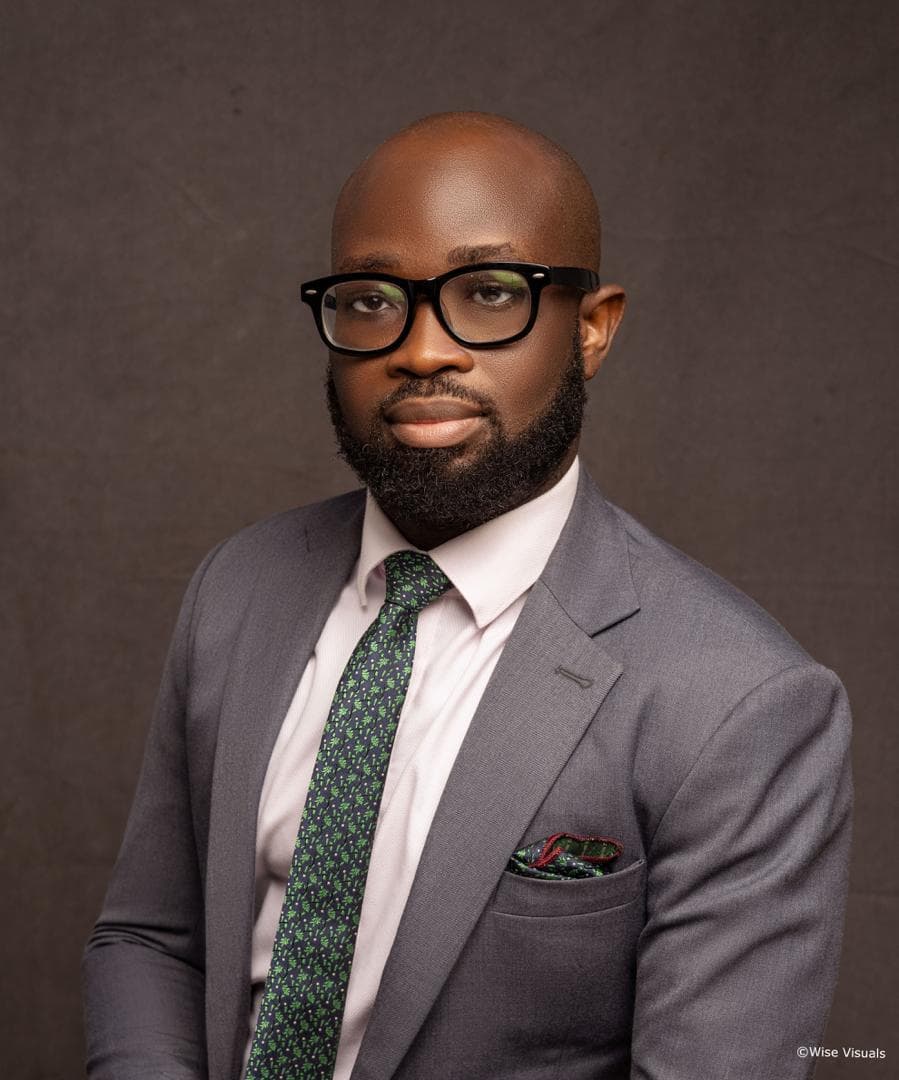
The Chief Executive Officer, Zitra Investments, Mr. Babatunde Obadero in this interview with Kayode Tokede hinted that the Central Bank of Nigeria interest rate cut is expected to drive economic activities. Obadero also discussed the company’s sixth anniversary, its plans to list on the Nigerian Exchange Limited and expand its operations. Excerpts
What has been the biggest constraint on access to credit in Nigeria?
If you talk to customers, they are at the receiving end of high interest rates. I think everybody in financial services felt a sense of relief after the last Monetary Policy Committee meeting. One of the reasons we are glad about the MPR decision is that we hope to start seeing interest rates come down.
Hopefully, that trend continues and is paired with a decline in inflation as well. When that happens, it should allow us to provide financing to customers at lower rates than we have today, which would help drive not only increased borrowing but also increased economic activity.
At the end of the day, we are in business to see our customers grow their economic activity, and that should, in the end, lead to greater prosperity for all of us as Nigerians.
Zitra Investments is marking its sixth anniversary. Looking back, what do you consider the company’s most significant contribution to SMEs and the Nigerian economy at large?
Zitra Investments has made a real impact on the SME sector and the Nigerian economy as a whole. Six years on, we have disbursed about 300,000 loans worth more than N30 billion. Supporting small businesses is at the heart of our business. We set out to deepen access to financial services for people who previously had limited or no access, wherever they are across Nigeria, and I believe we have been able to achieve that.
Interestingly, our SME portfolio performs better than our consumer credit portfolio. The data tells me that SMEs in Nigeria are better behaved than people often assume. Historically, we have seen them perform very well in repaying their loans.
More than 65 per cent of our customers are women, and the data also tells us that women demonstrate stronger credit behaviour than their male counterparts. Over the last two years, about two-thirds of the loan facilities provided by Zitra Microfinance Bank have gone to women.
We have seen significant growth in our operations over the last two years, and our goal is to triple the numbers I just mentioned over the next 24 months. During that period, we expect to disburse, on average, another N30 billion in loans. So, you will see a significant increase in our lending activity over the next 12 to 24 months.
Our fund management business, Zitra Fund Managers, has also grown. It not only seeks to manage funds for large corporates, institutional investors and the public sector, but is also focused on deepening financial inclusion by onboarding retail customers and small businesses. Ultimately, it is about helping our customers create and grow wealth.
What does being in business for six years mean to you personally, and what would you say is the central achievement of those six years?
Personally, I understand how difficult it is for businesses in Nigeria, and I dare say anywhere in the world, for a startup to launch and still be operating six years later. For me, that is a huge achievement in itself. Considering that SMEDAN says less than 20 per cent of businesses in Nigeria survive beyond their fifth year, while US data suggests the figure is less than half, simply making it past five years is something we should pat ourselves on the back for.
But we have not just survived this entire time. We have thrived, with year-on-year growth of about 80% since we started.
Zitra Investments has survived several challenges, including double-digit inflation, the unification of the naira in the foreign exchange market, and recession. What lessons have you learned?
We have learnt a lot of lessons at Zitra Investments. First, we were born in the COVID year, so I guess we were born into resilience and into coping with tough times. We literally started our business in 2020. If there was ever a time people would have assumed was a difficult time to start a business, it was 2020.
So, we are a product of resilience. If you are going to build a business in Nigeria that will stand the test of time, one of the most important things you need is grit. I like to call it “stick-to-it-ability”: the ability to stick to your principles, your core values and your vision of where you are headed, and to keep pushing until you achieve your desired outcomes. I think that is one of the core things that sets us apart.
Speaking to inflationary pressures and the devaluation of the local currency, I would say that what has helped us navigate these times is our innovation. It is important that we continue to find ways to manage our costs and remain laser-focused on efficiency, whilst giving customer service the pride of place it deserves. It is one of the reasons why we have successfully retained more than 70% of our customers since inception.
Thankfully, the economic pressures are easing as inflation growth declines, and our currency has been relatively stable in recent times. We believe that this portends well for businesses across different sectors, and clearly, financial services would do even better.
On asset management, what do your assets under management stand at now?
At Zitra, we have tried to position ourselves to offer value to different customer segments. Everything I have stated so far relates to our microfinance banking business. On the other hand, we have Zitra Fund Managers, a Securities and Exchange Commission-licensed asset management company that helps our customers manage their assets, whether that means equities, access to Eurobonds, or government-issued instruments such as treasury bills and bonds.
Until recently, that was not even a retail conversation. Thankfully, the mass market is now interested as well. But think of it this way: Zitra Fund Managers provides fund management services to our upscale customers, companies, large commercial clients and institutional investors, as well as retail customers and small businesses, while our microfinance bank provides access to savings, payments and loans to our retail customers and SMEs across all walks of life.
The business is structured so that Zitra Microfinance Bank can be your banking platform wherever you are in the country, not only for individuals but also for small businesses. Zitra Fund Managers can manage portfolios for all types of customers across different market segments. We also have a payments business that handles cross-border payments, whether you are paying bills in China, India, Bangladesh or any other part of the world. Our Zitra Group now has a combined balance sheet of about N50 billion.
When it comes to competition in the financial sector, what makes you unique?
Our unique value proposition is our ability to relate to our customers with empathy. Service is at the heart of what we do. Some people argue that their unique value proposition is technology. I think that is now a commodity. New products or features may give you more bells and whistles, but at the end of the day, they may not move the needle for you in the marketplace.
We also deliberately structured the business to serve customers across all the relevant touchpoints in the financial services value chain. You need a loan? Come to us. You want to save? Come to us. You want to invest? We are here for you. You want to buy Eurobonds? There is an entity within the ecosystem we have built that will attend to that. You need to pay your invoices for goods or services from China? Talk to us.
A one-stop shop for all your money needs. That is Zitra. When we say we are your wealth creation partner, we mean every part of that statement, and that is why we are here.
Which investment products have performed best this year, and which would you encourage prospective investors to consider for 2027?
All of our products have done well. I cannot point to one that has performed poorly. On the lending side, whether retail loans or SME loans, we have done well. We have funded purchase orders and discounted invoices for customers, and those have performed well.
In the fund management business, both our wealth management products and our fixed-income instruments have done well. We also have currency-specific products. For instance, we have FX products that help customers manage their money not only in naira but also in dollars, pounds or euros, as the case may be. Those have performed well too.
What would you describe as your biggest achievement?
I look at achievement not from the point of view of what makes you feel good about yourself, but in terms of how much impact you are able to make and how many people’s lives you have added value to. In the end, that is where our value lies as a business.
So, we are very mindful of the fact that we have disbursed more than 300,000 loans worth in excess of N30 billion. Our digital app is available on both the Google Play Store and the iOS App Store, and it has recorded more than 200,000 downloads.
These are important footprints. They mean we have done something right by these customers. The goal now is to deepen that impact: to get more feedback from them, understand their pain points better, and work out how to deliver better, faster and more convenient services.
What role has technology played in the business?
Technology is key. I must say first, though, that when people think of innovation, many limit their thinking to technology. Innovation goes beyond technology. But, leaving that aside for a moment, technology has been critical to what we do.
You can pick up your phone or laptop anywhere in the world and carry out your transactions, whether you are paying a bill, requesting a loan or starting a savings plan, without talking to anyone through our Zitra Ease mobile app or our Zitra Business internet banking platform. You can also call or text our contact centre team and have any problem resolved through the app, on WhatsApp or across our other social platforms.
It is in our plans to find creative ways to use technology and the AI tools available in the marketplace in ways that are in tune not only with our own internal business dynamics but also with how Nigerian consumers and businesses behave. It is one thing to have global tools; it is another to localise them, and I think it is important to get that point across. We have successfully deployed AI underwriting tools adapted to our local context for our consumer credit business, and we are hoping to do the same effectively for our SME lending. It is not enough to import those tools from the West. What matters more is that we customise them and bring our own cultural input into the technology and digital tools that are globally available.
What are the company’s growth targets for the next six to 10 years?
We are very focused on expansion, and in the coming months and years, we will show our customers and the market some of the very ambitious plans we have.
For instance, it is important to us that we extend our geographical reach, increasing access for customers who may not want to rely solely on digital channels. It is also important that we expand our product offerings to match our customers’ needs, whether in the asset management business, where we will be doing a lot more work in the coming months, in the bank, or in the payments business.
Over the next few weeks, we will also have our first commercial paper in the market as we embark on a N50 billion fundraise programme.
So, across our ecosystem, you will see significant expansion and growth in all of our businesses, in terms of platforms, products and access.
Are there plans for Zitra Investments to list on any Nigerian exchange?
The short answer is yes. There is a future where Zitra is listed on the NGX. Part of what we must do in Nigeria is make sure our businesses are listed on the NGX. There are different ways to go about it, but it is important that more businesses list. It is part of how we deepen our business environment, deepen participation in our markets, and enable everyone to participate in enterprise without necessarily being responsible for the day-to-day operations of the businesses. Hopefully, it also helps democratise access, not only to the market but to our businesses themselves.
Part of what limits the longevity of Nigerian businesses is that they are tied not only to the past but also to the strengths of their founders. A business needs to outlive those who started it, and I believe listing is part of how to achieve that.
Listing does not guarantee anything, but it potentially gives businesses more opportunities for growth. In the end, that takes the business forward because it can access not only new capital but also new thinking.