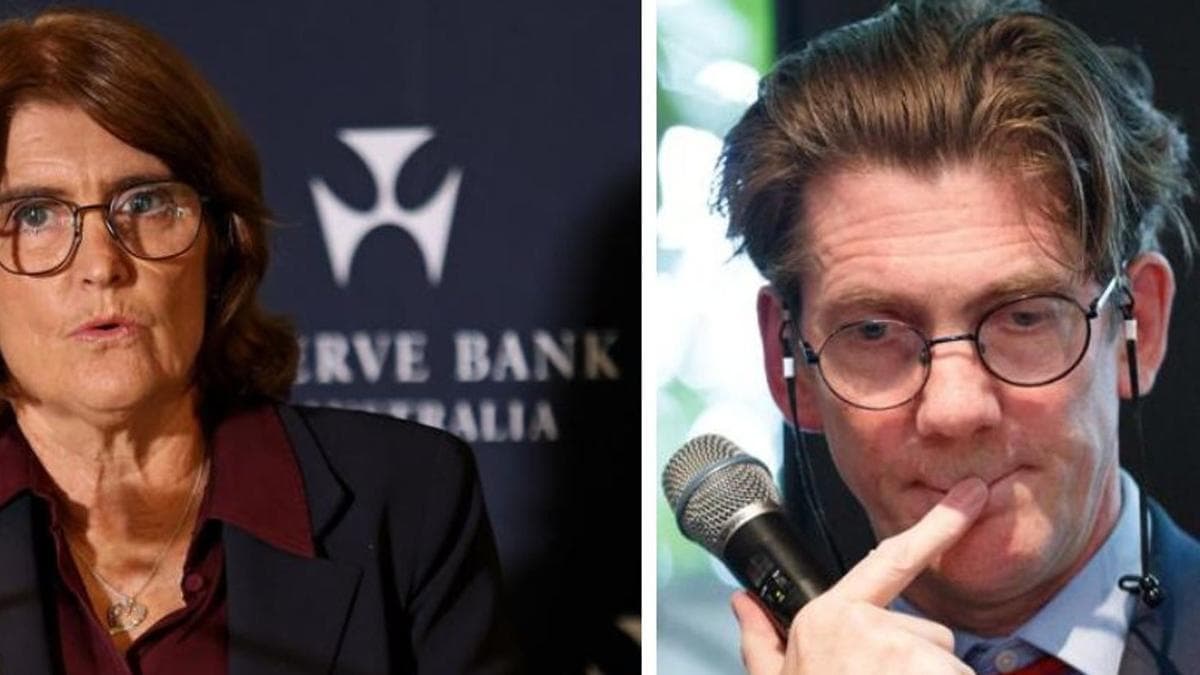
RBA deputy governor Andrew Hauser has hinted at further interest rate pain, saying the central bank will be forced to make hard choices going forward.
Mr Hauser told the Citi Investment Conference 2026 that inflation was higher than expected.
“Where do we stand today? Well, we’re a week and a half from the policy meeting, and we’re still finalising our forecast,” Mr Hauser said.
“I don’t know for sure, but a few things are clear, and the inflation outlook looks materially worse than we projected in the August report.”
Mr Hauser said the RBA would have to make difficult decisions, including a trade-off between a worsening jobs market and rising inflation.
In August the central bank expected headline inflation to be about 3.9 per cent, but it came in at 4.0 per cent.

So far in its rate-hiking cycle, the RBA has lifted the cash rate four times in six meetings by a total of 100 basis points. It has climbed from 3.60 to 4.60 per cent.
Markets are pricing in just a 27 per cent chance that the central bank lifts interests rates again on Melbourne Cup day.
Mr Hauser said the central bank was in a nightmare position where Australians expected inflation to stay higher for longer.
“The basic fact is inflation has been high for a long time now and we are beginning to see signs that some people in the community are not sure we are going to bring it back into target,” Mr Hauser said.
The RBA runs on a dual mandate of keeping price growth between 2 to 3 per cent while also maintaining full employment.
Currently, the two parts of the policy are pulling in opposite directions.
The latest Australian Bureau of Statistics data shows headline inflation is going the wrong way, largely due to the government’s temporary fuel excise tax cut ending.

Meanwhile, the all-important trimmed mean inflation rate – which strips out the top and bottom 15 per cent of items – was 3.60.
Complicating the picture are the volatile unemployment figures that showed 39,000 Australians lost their jobs.
Unemployment rose to 4.7 per cent, its highest level since the Covid pandemic but still well below the historical average.
Going forward, Mr Hauser said the central bank faces a “hard choice” of protecting the labour market while fighting inflation.
“The challenge facing the board, and has for some time, is do you do more to tackle high inflation recognising that means weaker activity and labour markets or do we hold our horses to protect the labour market” he said.
NED-9108-Monthly-Inflation-Indicator
Shock group facing interest rate pain
Despite much of the focus being on mortgage holders, Mr Hauser used his fireside chat to correct the record.
He said renters and low-income households felt rising rates more.
“I’ll make one other point because mortgagees get a lot of the attention. The greatest pain by higher inflation is held by those who are renting or on low incomes,” he said.
Mr Hauser said up to 15 per cent of renters were in negative cash flow, with higher inflation being a “gut punch” to these households.
The RBA’s latest modelling suggests just 2 per cent of households with a mortgage are in negative cash flow.
Mr Hauser reiterated that despite the attention on mortgages, borrowers suffered the least when interest rates increased.
He said when considering interest ratess, the RBA factored in the Australian dollar, asset prices and savings and investment incentives.

Have to react to rising oil prices
Mr Hauser was quizzed further about the pain households were feeling due to the US-Iran war.
Since July, unleaded fuel prices have surged about 39 per cent, while drivers who use diesel have been slugged more than 45 per cent.
Motorists pay about 1 cent more a litre for every $1 rise in a barrel of crude oil.
Mr Hauser said the central bank was forced to react to these price shocks due to flow-on impacts across the economy.
“We can’t stand in the way of a price shock … we are all poorer and we have to accept that fact,” he said.
“What we can do, and what we must do, is prevent one-off supply shocks and persistent supply shocks feeding through into higher second-round effects, higher inflation expectations.
“That will just make a bad thing worse.
“Where the shock is temporary, where the economy is balanced, where inflation expectations are well anchored, you can still do the standard playbook of looking through it, let the price level rise, accept that you’re worse off. Move on. No monetary response.”