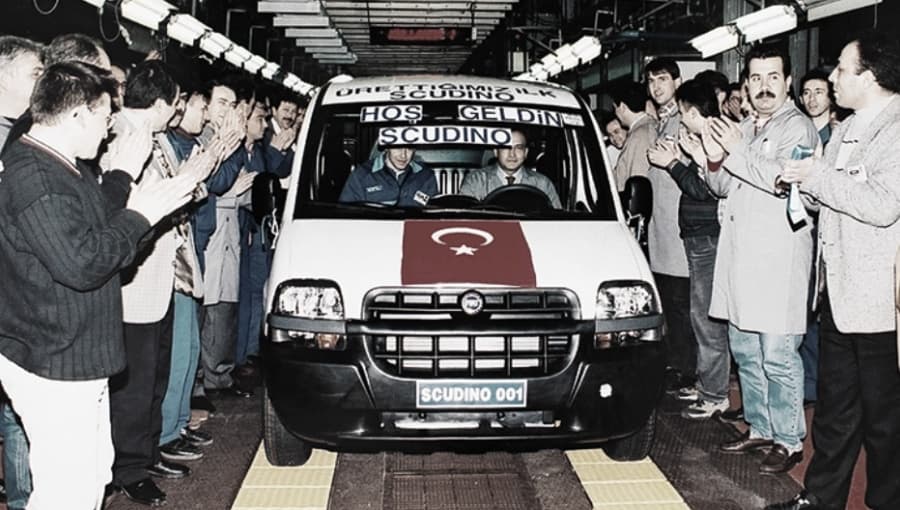
Turkey’s concerns over how to protect its car market from unfair Chinese competition have been eclipsed by a growing threat to the future of its own exports of vehicles and parts to the European Union – a threat that has further blunted its hopes of additional investment in the latest automotive technology.
Barrier-building
Until this year, Turkey and the EU appeared to be on the same page when it came to cheap Chinese vehicles. The European bloc imposed an additional tariff of up to 35% – over and above the existing 10% duty – on electric vehicles (EVs) from China in 2024. Turkey, which has a longstanding customs union with the EU, had already slapped an additional 40% customs duty on EVs from the People’s Republic in March 2023. Later, this would be extended to include hybrid and conventional Chinese cars. Minimum amounts of tax per car were also specified.
Ankara had also made market entry for carmakers from China and from other non-EU countries without free trade agreements with Turkey conditional on the availability of an extensive network of after-sales services.
In this way, Ankara intended to protect its domestic auto manufacturing plants, which are overwhelmingly owned by foreign investors including European Stellantis (BIT: STLAM) and Renault (EPA: RNO), to support its own national electric car brand, TOGG – a pet project of President Recep Tayyip Erdogan – and to encourage Chinese carmakers to open assembly plants in Turkey so as to bypass the customs wall.
Mixed results
Turkey’s car imports from China peaked in 2024, accounting for nearly 10% of all sales. In 2025, however, they flattened, notwithstanding the boom in the overall car market, and in 2026, Chinese car imports have fallen faster than the market. TOGGs have re-emerged as the best-selling EVs, followed by Teslas.
However, the protectionist measures have done little to temper Turkey’s overall merchandise trade deficit with China, which rose from $38.1bn in 2022 to $46.3bn in 2025. Moreover, the main beneficiaries of decreasing Chinese car imports have been other imported models, mostly from Europe. Imports accounted for over 70% of car sales in 2024 and 2025, compared to around 60% between 2019 and 2022.
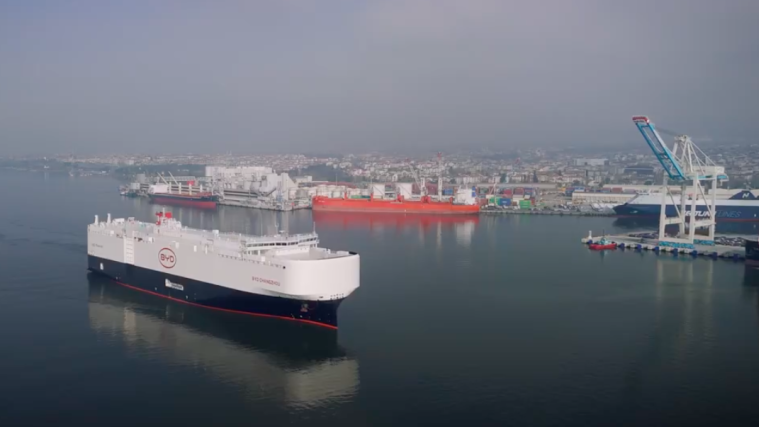
The BYD Changzhou heads for port: China's BYD began shipping large volumes of EVs into Turkey after Ankara became receptive to the company in anticipation that it would build an auto plant in Manisa. Then Turkey realised no construction work was taking place...
As for investments, China’s BYD (SHE: 002594) confirmed plans for a 150,000 EVs-per-year plant in Manisa, Turkey, in 2024. In return, it was temporarily exempted from the 40% additional duty. Imports of BYD models soared until Ankara realised that the plant was not being built. In June, the project was officially shelved, with no compensation or customs arrears paid. Chery (HKG: 9973) and its various brands once again became dominant in Chinese car exports to Turkey.
WTO case
In July, a World Trade Organisation (WTO) panel decided in China’s favour on an application made by Beijing . It said that none of Turkey’s arguments could be held to justify discriminatory import regulations or tariff increases exceeding the so-called bound rate – i.e., the maximum import duty to which a country has committed itself for a certain product. To add insult to injury, the panel also criticised the granting of tariff exemptions in return for investment pledges.
Turkey’s Ministry of Trade noted that the report was not final, that it imposes no financial obligations on Turkey, that Ankara disagrees with it and that Ankara has the right of appeal. The appeal deadline has been suspended until October 27 pending bilateral talks. Given the paralysis of the WTO’s dispute settlement system, an extension of these negotiations seems likely.
Options might include limits on import numbers, like this month’s cap on European imports of Chinese hybrid vehicles, or a minimum car price deal. Alternatively, Turkey may simply rephrase its measures, some of which have already been revised since Beijing lodged its complaint. But don’t hold your breath: right now, Ankara has weightier matters on its mind.
Over in Europe…
In Paris, Brussels and Berlin, thinking has evolved. Besides protecting its existing manufacturers, the EU is looking to upgrade its entire technological capacity to reduce dependence on both the US and China. Its draft Industrial Accelerator Act (IAA), unveiled in March, aims to decarbonise manufacturing and raise its share in GDP from 14% to 20% by 2035. The emphasis is on energy, technologies, energy-intensive industries – and automobiles.
Turkey is pushing to ensure that "made in Europe" includes "made in Turkey" when it comes to vehicles.
Once the legislation is adopted, autos (and their components) “made in Europe” will be favoured in public tenders, procurements for publicly supported programmes and consumer incentives like subsidies for EV prices. This raises the age-old question of whether Turkey is “in Europe”.
Ankara’s business community and Ministry of Trade say ‘Yes’. They point to the heavy European investment in the Turkish automotive sector, the extensive two-way network of supply chains, the EU’s 70% share in Turkey’s automotive exports, and the relatively balanced bilateral trade volume of some €55bn per year in cars, commercial vehicles and parts, which makes up a quarter of Turkey-EU trade.
However, an agreement reached by France and Germany this month suggests that Europe will say ‘No’: While “equivalent origin” rules may apply in some cases, Ankara will be largely excluded from the IAA mechanisms.
Investment gap
Turkey is in urgent need of investment to upgrade its car plants and re-orient its component, battery and software capacity. Electric cars now account for almost 20% of new cars sold in Turkey, and hybrids for over 30%. EVs already dominate Turkey’s export markets.
Toyota (TYO: 7203) has long produced a plug-in hybrid car at its plant in Turkey while Hyundai (KRX: 005380) recently started to manufacture an all-electric model. TOGG is also creating its own ecosystem. Turkey has strengths in commercial vehicles, and its bus makers are championing autonomy. Yet for the most part the multinationals owning almost all Turkey’s car plants have been slow to transform their operations.
With the IAA casting a shadow over equal access to the EU market, new investment may be harder to come by. BYD will feel that its decision to invest in Hungary, an EU member country still with relatively low labour costs, has been validated.
How to respond
While Turkey and its supporters among European industrialists lobby to attenuate the damage, the media has proposed retaliation – for example, by imposing additional duties on imports from European firms like Volkswagen (ETR: VOW3) that do not manufacture in Turkey.
Such blatant disregard of the customs union (and WTO rules) is unlikely. In time, Ankara may nevertheless manipulate its sales tax rates to favour locally produced vehicles, selectively enhance its investment incentives or credit subsidies and increase its backing for TOGG. It could also reinforce the advantages that locally produced goods and services enjoy in Turkish public tenders, rather than repealing them as recently mooted – and as the EU has long demanded.
Not everybody is pessimistic. Koc Holding Automotive Group president Haydar Yenigun, local partner to both Stellantis/Fiat and Ford (NYSE: F), has said that Europe will soon see what a mistake it has made. He also predicted that new partnerships with Chinese firms would strengthen Turkish industry further.