By Hsu I-ping and William Hetherington / Staff reporter, with staff writer


The number of mortgage borrowers aged 65 or older in Taiwan exceeded 61,600 at the end of last year, the most since records began in 2009, according to the latest available sample data.
As of December last year, the Joint Credit Information Center’s mortgage dataset contained nearly 1.51 million outstanding mortgage cases, of which more than 61,600 involved borrowers aged 65 or older, accounting for about 4.08 percent of the total.
The figure was up from nearly 54,700 a year earlier, an increase of 6,900, or more than 12 percent.
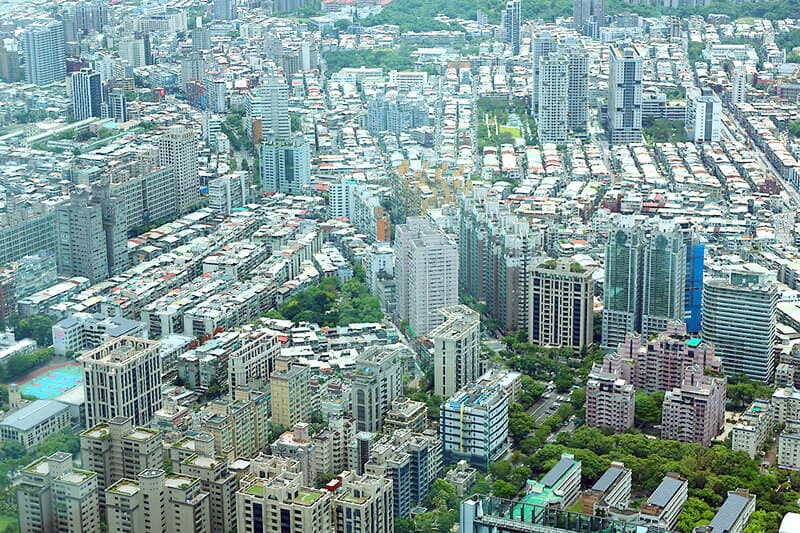
Commercial and residential buildings are pictured in Taipei on June 27.
Photo: CNA
The number of mortgage cases involving borrowers aged 65 or older has more than tripled over the past decade, rising from about 19,500 in December 2016.
New mortgage cases involving borrowers aged 65 or older also remained relatively high. In the second quarter of each year from 2017 to this year, the number ranged from a low of 477 in 2017 to a high of 1,950 in 2022. The second-highest figure was 939 in 2024, while the latest data showed 547 new cases in the second quarter of this year.
Sinyi Realty’s (信義房屋) real estate research office project manager Tseng Ching-te (曾敬德) said that the number of elderly mortgage borrowers was substantial.
Some might need loans to access funds or purchase a different home, while it was unclear whether the trend was related to reverse mortgages, he said.
Banks’ willingness to lend to older borrowers also suggests confidence in their ability to manage lending risks, Tseng said, adding that the trend was unlikely to cause problems.
Colliers landlord representation services department director Huang Shu-wei (黃舒衛) said that banks generally consider a borrower’s age and the mortgage term when assessing loan applications.
Many use a combined borrower age and loan term of 75 to 80 years as a reference for risk management, although the actual repayment period depends on the bank’s lending policies and the borrower’s income and ability to repay, he said.
Taiwan’s emergence as a super-aged society, along with later retirement ages, the growing number of elderly people returning to work and increasingly diverse income sources, are challenging traditional methods of assessing mortgage repayment capacity, Huang said.
For wealthy borrowers, loans are increasingly serving purposes beyond home purchases, extending to broader asset allocation and wealth succession planning, Huang said.
However, outstanding debts can be deducted from an estate’s taxable value only if they meet tax-law requirements and are supported by adequate documentation. Borrowing money does not automatically reduce estate tax liabilities. Tax authorities are particularly likely to scrutinize the reasons for a loan, the movement of funds and their actual use when borrowing occurs late in life or during serious illness, Huang said.
Beyond reverse mortgages and trusts, the substantial property and financial assets accumulated by Taiwan’s post-World War II baby boom generation are gradually entering the wealth-transfer stage, Huang said.
How the financial sector redesigns lending, asset revitalization and wealth transfer tools would become a key challenge in the next phase, he added.