Every day, 90,000 barrels of Nigeria’s crude are pledged to a lender under Project Gazelle, limiting the country’s freedom to sell or direct those barrels elsewhere while the loan remains outstanding. At more than $100 a barrel, the crude has a gross annual sales value of about $3.3 billion. The government wants to refinance the facility, but the key question is whether the deal will free more oil or simply pledge it under easier terms.
One alternative is a sovereign Eurobond that could settle the outstanding Gazelle balance and, if the contractual obligations are formally discharged, release the associated crude. The benefit would extend beyond potentially lower financing costs, giving Nigeria greater flexibility to earn foreign exchange, generate revenue or supply domestic refineries. That raises a central question about the government’s proposed refinancing: why replace one crude-backed facility with another when conventional dollar borrowing might offer a way out?
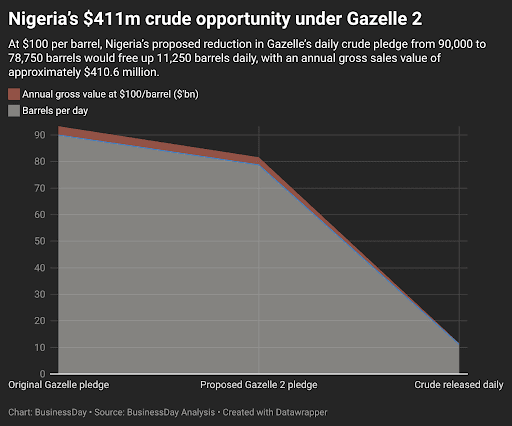
The National Economic Council (NEC) approved a proposed $4.5 billion Gazelle 2 arrangement on August 3, 2026. About $1.5 billion would refinance existing obligations, while the remaining $3 billion would provide additional liquidity for reserves, fiscal needs and infrastructure. Under the proposal, the daily crude commitment would fall from 90,000 barrels to about 78,750 barrels.
CFG Advisory argues that Nigeria should consider issuing a sovereign Eurobond to settle Gazelle, cancel its associated crude-delivery commitments and replace oil-backed financing with conventional dollar debt. The distinction matters. Gazelle 2 would reduce the volume of pledged crude by 11,250 barrels a day. A successful Eurobond refinancing could potentially eliminate the existing delivery obligations altogether. But that outcome would depend on the settlement amount, the original contract and the cost of raising new debt. A cheaper headline interest rate alone would not establish which option offers better value.
The value of the barrels
The arithmetic shows why the choice matters. At $100 per barrel, the 90,000 barrels committed daily under Gazelle have a gross annual sales value of approximately $3.285 billion. Reducing the commitment to 78,750 barrels would lower that figure to about $2.874 billion, leaving 11,250 barrels a day outside the proposed pledge.
Those barrels would have a gross annual sales value of roughly $411 million at the assumed oil price. The figure is almost ten times the indicative $42.45 million in annual interest savings from refinancing $1.5 billion at 7.54 percent rather than 10.37 percent.
The comparison is not between equivalent amounts of money. The $411 million represents potential gross sales, not additional government revenue, while the $42.45 million represents an indicative financing-cost difference before fees. Production costs, royalties, taxes, contractual obligations and the terms of the replacement debt would determine how much of the oil’s value Nigeria could retain.
Olugbenga Olaoye, an energy economist and member of the USAEE, said, “Pledging crude oil to repay debt comes at an opportunity cost, particularly when oil prices are high. At $100 per barrel, the focus should not be on the gross value of the crude alone, but on how much revenue the federation can retain after production costs and contractual obligations. Nigeria needs to assess whether tying down future oil supplies delivers greater value than alternative financing arrangements that leave more crude available for commercial sale.”
Still, the scale of the potential revenue makes the allocation decision consequential. Oil committed to a lender cannot necessarily be redirected at the government’s discretion, even when higher prices increase its value. The question is whether Nigeria can recover that flexibility without paying so much to exit the facility that the financial benefit disappears.
The case for cheaper dollar debt
Existing Nigerian Eurobonds provide a reference point for CFG Advisory’s proposal. An October 12 market analysis citing Debt Management Office data put yields at 7.54 percent for a January 2031 bond, 7.65 percent for a June 2031 bond and 8.02 percent for a September 2033 bond. Gazelle’s reported current financing rate was approximately 10.37 percent.
At 7.54 percent, $1.5 billion in borrowing would carry annual interest of about $113.1 million, compared with $155.6 million at 10.37 percent. The indicative difference is $42.45 million annually. At 8.02 percent, the difference would be approximately $35.25 million.
These calculations illustrate the potential benefit, not a guaranteed saving. Yields on outstanding bonds do not establish the price of a new Eurobond issue. Market conditions, maturity, transaction expenses, early-termination charges and the final Gazelle settlement amount would all affect the result.
Idris Oyekan, a capital market and credit rating analyst at DCR, said: “Refinancing Project Gazelle with a Eurobond could lower Nigeria’s financing cost, but that outcome is not automatic. The government must compare the effective cost of a new Eurobond with the existing facility, including issuance fees, settlement charges and other transaction costs. The yield on an existing sovereign bond provides a useful benchmark, not a guarantee of the rate Nigeria would secure today. The decision should be based on the total cost of borrowing, not the headline interest rate alone.”
The proposed $4.5 billion Gazelle 2 arrangement also extends beyond refinancing. Only about $1.5 billion is intended to settle the existing balance. The remaining $3 billion is additional borrowing and should be assessed separately. If Nigeria chooses the Eurobond route, it must distinguish the amount required to extinguish Gazelle from any additional funds it wants to raise. Otherwise, a transaction presented as cheaper refinancing could obscure the cost and purpose of new borrowing.
Sheriff Abdulsalam, a corporate finance and alternative investments specialist, said: “The key question is whether Gazelle 2 creates enough economic value to justify the additional borrowing. Refinancing the outstanding $1.5 billion may improve the terms of existing debt, but adding another $3 billion introduces a separate investment decision. Nigeria should demonstrate how the additional funds will be deployed, what returns or fiscal benefits they will generate, and whether these benefits outweigh the cost of fresh debt and continued crude commitments. More liquidity is not necessarily better financing.”
Ultimately, the test is whether Nigeria can lower its financing costs, regain flexibility over its crude and use any additional borrowing productively. The size of the facility matters less than the net fiscal value it delivers.
Can released crude strengthen domestic supply?
CFG Advisory also argues that freeing crude could support deliveries to Dangote Refinery and help reduce pressure on local petrol prices. That possibility gives the proposal a wider economic dimension. Crude made available for domestic refining could reduce the need for imported feedstock, support refinery utilisation and potentially increase domestic product supply. But the benefits depend on actual deliveries and commercial terms, not merely on a reduction in the volume pledged to lenders.
Nor would more domestic crude automatically guarantee cheaper petrol. International oil prices, exchange rates, refining costs, distribution expenses and market margins would continue to influence pump prices. The government should therefore track the additional barrels delivered to domestic refineries, the imported feedstock displaced, the resulting change in product output and any measurable effect on consumer prices. The same discipline should apply to crude redirected towards exports or other revenue-generating uses.
Publish the full cost of the decision
Before presenting Gazelle 2 or a Eurobond alternative as a fiscal gain, the government should disclose the all-in financing costs, settlement charges, maturity, repayment schedule, collateral arrangements and the precise crude obligations that would remain or be extinguished.
It should also explain how the additional $3 billion under Gazelle 2 would be used and how the expenditure would support repayment capacity, rather than allowing the liquidity component to be bundled into the refinancing argument.
At $100 a barrel, Nigeria has a stronger reason to examine the opportunity cost of committing crude to debt repayment. But the objective should not be to maximise the number of barrels released at any price. It should be to maximise the net revenue retained after accounting for financing costs and contractual obligations. A cheaper Eurobond could offer a route to that outcome. Whether it does depend on the executed terms and the cost of settling Gazelle in full.
The measure of success is straightforward: lower total financing costs, clearly extinguished crude commitments and more net revenue available to the federation or productive domestic uses. Until the government publishes the terms and demonstrates those gains, the oil windfall is an opportunity to secure, not a dividend already earned.
Related News

Oluwatobi Ojabello, PhD, is a dynamic and multi-dimensional Assistant Editor for Economy and Markets with over two years of professional journalism experience. He delivers authoritative, data-driven coverage of fiscal policy, financial institutions and capital markets, using clear analysis to explain Nigeria’s most complex economic developments. His work focuses on macroeconomic policy, financial stability and corporate performance, turning technical issues into accessible narratives that inform both experts and everyday readers.

