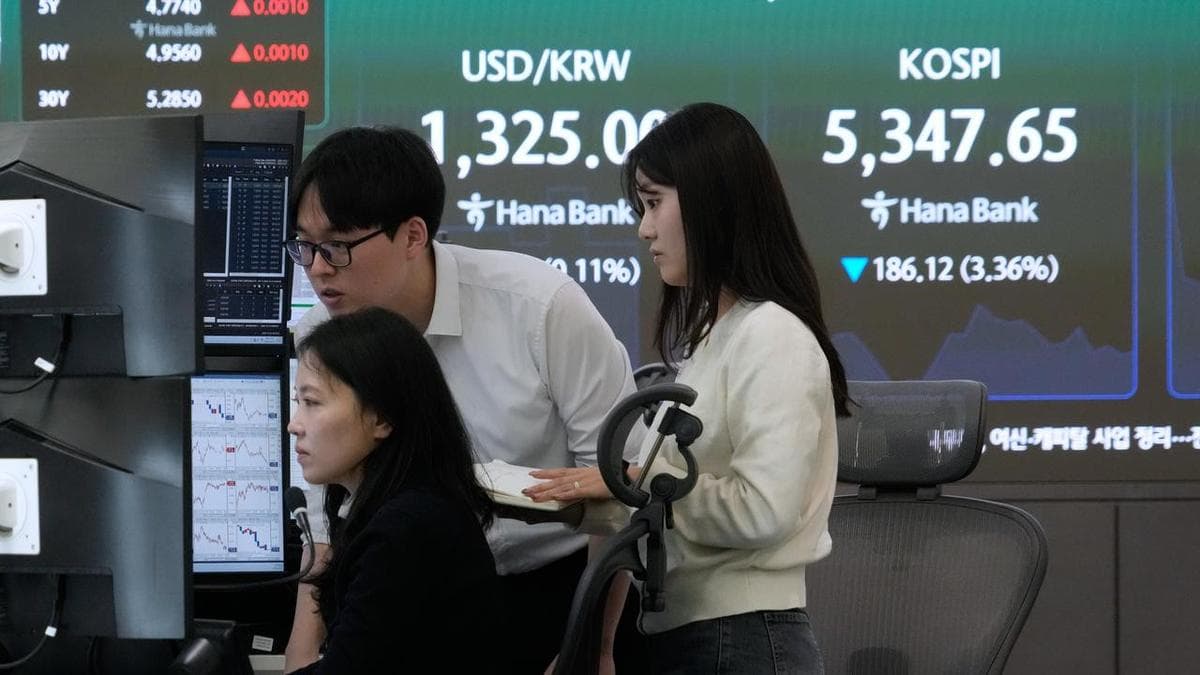
Asian shares have fallen as concerns over the enormous funding needs of AI hammered tech and led to the biggest daily rally in Treasuries in more than three years, with investors fleeing to sovereign bonds and safe-haven currencies.
Markets also sharply pared back expectations of further policy tightening from the Federal Reserve, stripping out almost a full quarter-point rate hike for next year amid concerns a bursting AI bubble could derail the data-centre investment boom and hobble the US economy.
A December rate rise is no longer fully priced, with the implied probability falling to 85 per cent.
That was despite elevated oil prices, with Brent hitting a five-month peak at $US114 a barrel on Friday. Houthi attacks in Saudi Arabia stoked concerns of further disruption to energy supplies as fears grow that the conflict in the Middle East could escalate sharply.
MSCI's broadest index of Asia-Pacific shares excluding Japan fell 0.3 per cent on Friday, bringing its weekly loss to 2.7 per cent and marking a fourth straight week in the red. Japan's Nikkei dropped 1.3 per cent and was down a whopping five per cent for the week.
South Korea's KOSPI skidded 1.7 per cent, on course for a 4.3 per cent weekly decline, with memory chipmaker SK Hynix down 2.5 per cent on the day. Taiwan's stock market was closed due to a typhoon.
An index of mainland Chinese blue chips lost 1.1 per cent on Friday to hit the lowest level since July 2025. The index was down about 20 per cent from its peak in late June. Hong Kong's Hang Seng edged up 0.1 per cent after dropping three per cent on Thursday.
"AI is under the cosh," said Charlie McElligott, managing director for cross-asset strategy at Nomura Securities International in New York, in a note.
"US Treasury bonds are - gasp - working as your hedge again, as the market seems to be real-time repricing the probabilities of a US growth scare off the back of the AI reset."
On Wall Street, the Nasdaq slumped more than two per cent as Meta shares lost nearly eight per cent after the Facebook parent posted its first cash outflow in more than a decade due to its AI-related expenditures, and announced plans to issue non-voting shares in a two-for-one split to raise capital to spend on the technology.
Tesla shares fell 3.1 per cent as the electric car maker cut its 2026 capital spending plans.
"The question is whether selling accelerates or markets stage another familiar reversal," said Chris Weston, head of Research at Pepperstone.
"There's nothing more emotive than a falling market where buyers refuse to engage. Sellers don't need a fresh catalyst when deteriorating price action itself encourages more selling."
As equities tumbled, money flowed into safe-haven US Treasuries, sending yields plunging across the curve overnight. The benchmark 10-year Treasury yield slid more than 19 basis points, the biggest drop since March 2023, before steadying at 4.9591 per cent on Friday, back below the closely watched five per cent level.
That was also due in part to the ongoing sell-off in French bonds, whose benchmark yield climbed six basis points overnight to 5.0601 per cent, the highest level since 2002.
"The US 10yr yield gapped back below five per cent with some conviction. We're not convinced it keeps on going," said Padhraic Garvey, ING's regional head of research for the Americas.
"We're minded to expect it to snap back above (five per cent), as we still have inflation/fiscal deficit/AI boom underpinnings to navigate. And we have the US midterm elections approaching as an excuse for trouble. But it will need some degree of calm in the risk space first."
The two-year Treasury yield slumped nearly 19 bps overnight and were last flat at 4.6566 per cent.
Government bonds in Asia also rallied. The yield on 10-year Japanese government bonds fell nine basis points to 2.790 per cent, while Australia's 10-year yield dropped 10 bps to 5.164 per cent.
In currency markets, safe havens such as the yen and Swiss franc gained. The US dollar fell 0.2 per cent to 156.44 yen on Friday, after slumping 0.9 per cent overnight.
The dollar also slipped 0.1 per cent to 0.8196 Swiss francs, the lowest in a month, after an overnight fall of 0.5 per cent.
Gold failed to catch any safe-haven demand though, and was flat at $US4,021.99 an ounce on Friday after a nearly three per cent drop overnight.