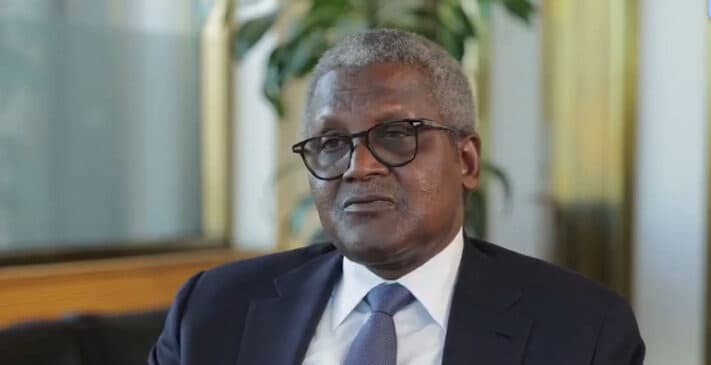
…Maps out $50 billion bet on Africa’s industrial future
Aliko Dangote, President of Dangote Group, said Africa can only become an industrial powerhouse if it fixes its electricity shortage, builds stronger home-grown financial institutions and adopts policies that turn raw materials into manufactured goods.
The president and chief executive officer of Dangote Industries Ltd. said the continent has the resources, population and investment opportunities to compete as a manufacturing hub, but lacks the institutions and infrastructure to capture the benefits.
He spoke at the 2026 Financial Times Africa Summit in London in a conversation with the newspaper’s Africa editor, David Pilling.
“For Africa, what we need the most today is actually power,” Dangote said.
About 650 million Africans have no access to electricity, a gap he called incompatible with the continent’s industrial ambitions. Unreliable supply forces countries to export minerals unprocessed rather than refine them locally, he said, adding that mining companies often cite power as the main reason they can’t build processing plants near their mines.
Dangote’s group has outlined a $50 billion investment program for 2026 to 2030. He said the plan is partly meant to show other Africans that large projects can be delivered on the continent and to encourage them to invest. The goal, he said, is a wider industrial ecosystem that creates jobs and keeps more economic value in Africa, not just a bigger conglomerate.
“The legacy we are trying to set up is how do we industrialise our continent?” he said.
Asked why Africa has produced so few industrial companies of global scale, Dangote pointed first to finance. The continent needs “very strong financial institutions, their own financial institutions,” he said, along with firm agricultural and industrial policies.
Read also: Nigeria diesel receipts hit 13-month low as domestic supply, imports plunge
He used the group’s experience building the Dangote Petroleum Refinery in Lagos to illustrate the problem. Conventional project financing was extremely hard to secure for major African industrial investments, he said, so the group paid for the refinery from its own balance sheet.
Long financing negotiations can sink industrial projects, Dangote said, by delaying construction, raising costs and exposing investors to shifting economic conditions.
Going without project finance carried heavy risks, made worse by the collapse in Nigeria’s currency and the cost of building supporting infrastructure, he said.
The naira weakened from about N136 to the dollar to as much as N1,800 while the refinery was being developed, and roughly 90 percent of the group’s revenue was in the local currency.
Dangote also urged African governments to rethink how they shield local industry, warning that cheap imports could permanently erode the continent’s productive capacity. Emerging manufacturers need policy support to compete with established foreign producers, he said, particularly when imports are priced low enough to discourage investment in local factories.
He distinguished that from barriers between African countries. Dangote called for a regional approach that protects industry from unfair outside competition while keeping the aims of the African Continental Free Trade Area intact. African economies should trade more freely among themselves, he said, under a common framework against external competition.
The industrialist questioned why poverty remains widespread given the continent’s farmland, mineral wealth and young population. Those endowments suggest the problem is not a lack of resources but too little productive investment and industrial capacity, he argued.
“Why should we remain poor?” he asked.
Dangote said he is optimistic that African governments, entrepreneurs and investors are increasingly determined to build their own productive capabilities.
Related News

