In last week’s installment of Mexico and My Money, I wrote about investing in Mexican real estate through the lens of financing a property purchase. But foreigners have many more options for investing extra cash in Mexico, whether it’s to diversify a portfolio or invest funds acquired while living here.
Our recent financial survey found that readers’ top investment in Mexico is real estate, with 85% of respondents saying they had bought property here, either to live in or for other reasons. Besides real estate, MND readers apparently do very little investing in Mexico. About 8% of survey respondents said they have bought stocks or bonds, while roughly 10% said they had invested in a local business.
Below, I’ll look at three investing opportunities for foreign residents in Mexico: CETES, pagarés and stocks.
Earning passive income with Mexican government bonds
Known as CETES, government bonds are one of the simplest, low-risk options expats have to earn passive income while living in Mexico. And who doesn’t need a little extra money these days?
CETES, or Certificados de la Tesorería de la Federación, are Mexican federal treasury certificates and the functional equivalent of U.S. Treasuries. They are auctioned by the Bank of Mexico most Tuesdays and available in various maturities (e.g., one, three, six and 12 months).
Known as “zero coupon” bonds, these securities are sold at a discount, with investors receiving the full face value at maturity, just like a U.S. T-bill. For this reason, you receive no interest payments on CETES until maturity, so holding them for the full term is essential to earn a return.
Mexico and My Money: Borrowing for a property purchase in Mexico
Yields and requirements for buying CETES
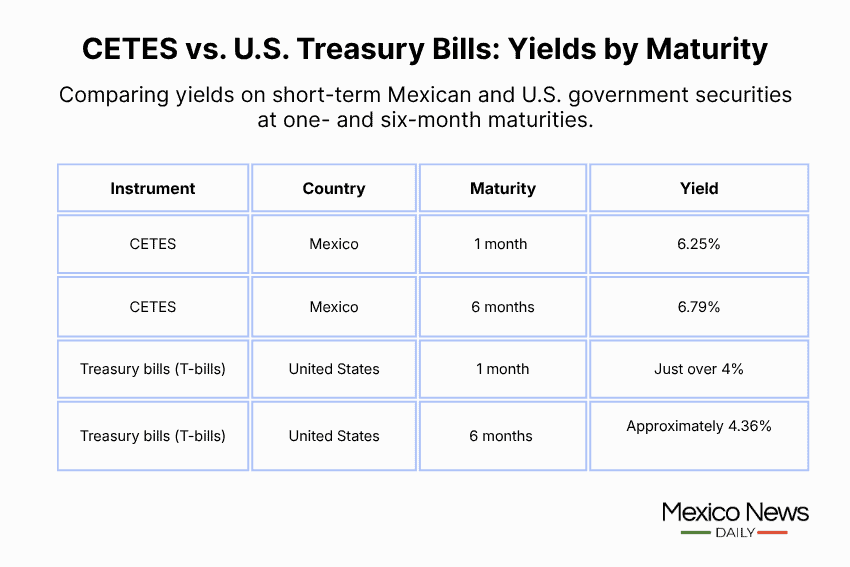
The most obvious benefit of investing in CETES is to help insulate your savings from inflation, which is currently running around 3.5% in Mexico. Besides, CETES are currently leaving U.S. T-bills in the dust on yields.
CETES yields vary based on the holding period, with six-month bonds currently offering 6.79%, while those with a one-month maturity yield 6.25%. In contrast, a six-month T-bill yields about 4.36% and a one-month T-bill yields a little over 4%, which is only slightly above the U.S. 3.7% inflation rate.
While savvy investors know there’s a first time for everything, the Mexican government has never defaulted on interest payments for CETES bonds. Given the stability of Mexico’s economy lately, the odds of a government default on these bonds (especially for short holding periods) are very low.
These bonds can be purchased by Mexican citizens and legal foreign residents, but not by tourists or those living outside Mexico. In addition, foreign residents must meet the following requirements:
-
Be over 18 years of age.
-
Show proof of legal residency (e.g., a permanent or temporary residency card).
-
Have a bank debit card or CLABE number for a Mexican bank account in which the investor is the owner. (Foreign accounts cannot be linked.)
-
Have a CURP number (found on your residency card) and RFC number (Mexican tax ID).
The Mexican government operates a website to sell CETES directly to the public at cetesdirecto.com. These bonds can also be purchased through Mexican brokers.
Mexican bank promissory notes (pagarés)
Pagarés, short for pagaré con rendimiento liquidable al vencimiento, are a low-risk, term deposit earning a fixed yield.
They work similarly to certificates of deposit in the U.S., where the purchaser lends money to a Mexican bank for a specified period and the bank pays a fixed interest rate upon maturity. Pagarés are funded with cash and fully insured up to the IPAB limit of 400,000 UDIs (3.54 million pesos or about US $193,000) when purchased from regulated banks.
Right now, these investments are yielding anywhere from 3% to 11% annually. Traditional banks like BBVA, Santander and Banamex tend to offer lower yields (3% to 7%), while fintech and digital providers such as Inbursa offer higher yields (8% to 11%).
Key trade-offs of pagaré investments
The primary downside to pagarés is their lack of liquidity. If an investor withdraws funds from a pagaré before it matures — or sells it on the secondary market before maturity — all of the accrued interest is forfeited and the seller incurs a penalty. So, it’s important to commit funds that won’t be needed during the lockup period.
Pagarés are purchased directly from the issuing bank. Unlike CETES, they cannot be bought from brokers. Another key difference between CETES and pagarés is the capital required. Banks typically have a minimum investment of around 5,000 pesos (US $267) for pagarés, while CETES can be purchased for as little as 100 pesos (US $5).
Like CETES, foreigners interested in buying pagarés must hold legal residency in Mexico and maintain a Mexican bank account.
Foreigners can also invest in Mexican stocks
Full confession: I spent six years working as an equity analyst for various investment banks back in the early aughts, so I do not take stock investing lightly.
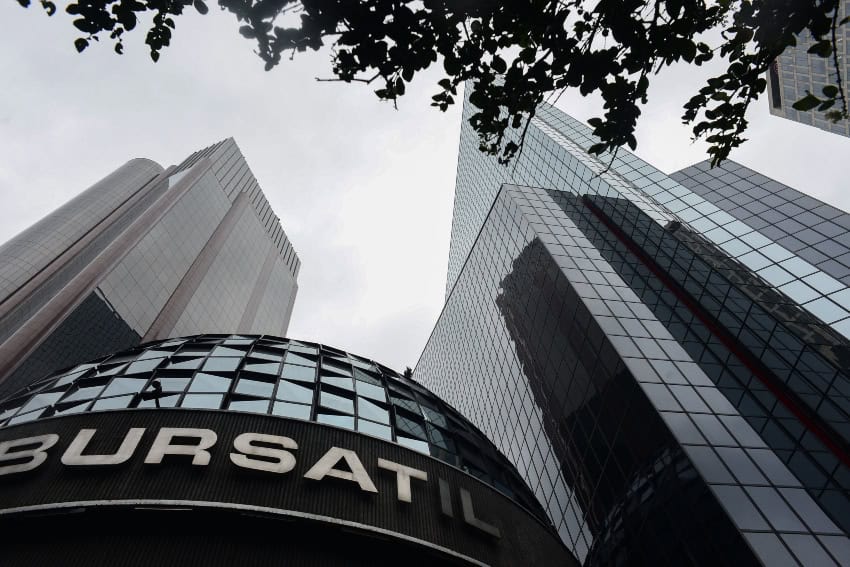
While some investors may purchase stock after hearing a hot tip from a friend or watching an influencer on TikTok, I don’t endorse it. In contrast to purchasing CETES and pagarés, there is more risk associated with stock investing.
There is no guarantee that your investment will make money, and it’s possible to lose all your principal. For anyone serious about stock investing, due diligence is required.
Stock investing by Mexican households is not common, with an estimated 1% to 5% actively trading stocks. For those who do, one of the best places I’ve found to research Mexican stocks is TradingView Mexico. For market news, another great resource is Mexico Market Chatter from Miranda Intelligence. Mexican brokers such as BBVA, Actinver and Monex also produce equity research for their private clients, as do some foreign brokerage houses.
Navigating Mexican brokerage accounts
Legal foreign residents can trade Mexican stocks through a licensed Mexican brokerage house. Two of the most popular platforms with retail investors today are GBM+ (Grupo Bursátil Mexicano) and Bursanet (by Actinver).
But there are a few unique hurdles for foreign nationals to clear. Chief among them is that foreigners must open a Mexican brokerage account in person rather than online.
Mexico and My Money: Affordability is a growing problem in Mexico, too
When doing so, the following is typically required:
-
A valid passport.
-
Proof of legal immigration status (residency card), either temporary or permanent.
-
CURP and RFC numbers.
-
Constancia de Situación Fiscal (your official tax status issued by the SAT).
-
Proof of local domicile less than three months old (e.g., a CFE bill).
-
CLABE number for a Mexican bank account in your name.
If none of these options appeal to you, keep an eye out for my upcoming article examining emerging opportunities across Mexico’s fast-growing fintech sector.
From tipping and working with local contractors to moving money into Mexico from abroad, check out more from MND’s “Mexico and My Money” archive.
MND writer Dawn Stoner is reporting from Guadalajara.