A statement by the International Monetary Fund (IMF) mission team to Malawi last week, after engaging the local authorities on the issue of a possible next Extended Credit Facility (ECF) programme, should spark hope in Malawians.
The messaging suggests the economy is stepping into the right direction.
The Breton Woods’ institution lauded Capital Hill for working towards stabilising the economy. It spoke highly of the National Economic Recovery Plan (NERP).
“In line with the 2026-27 budget targets, domestic revenue is increasing, and expenditure has been tightly controlled,” IMF mission chief Justin Tyson said in the statement.
He said the authorities had also taken decisive actions, such as fuel and sugar pricing reforms, which helped improve market functioning.
“Inflation has been moderating in recent months, supported by low food inflation, though non-food inflation remains high,” the IMF report reads.
But this does not necessary point to improved living standards. Malawians are not unaware of the hardships they endure.
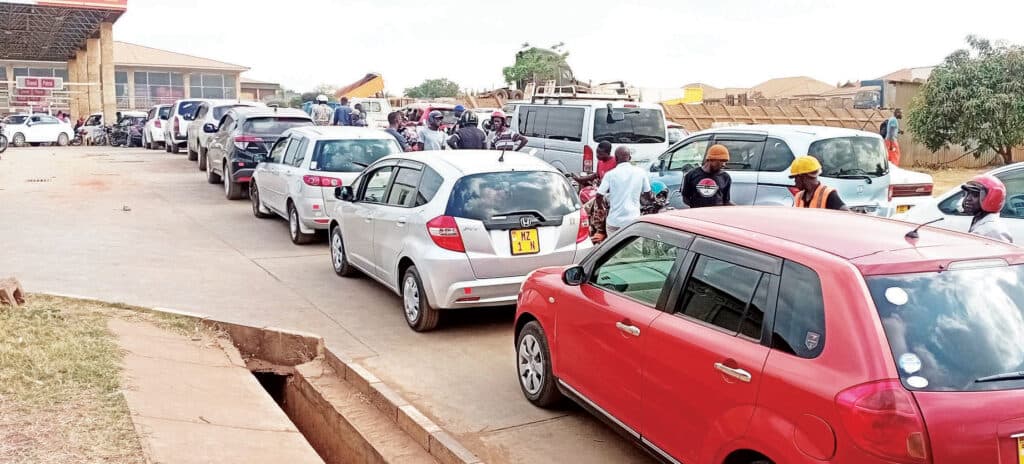
Most are paying three times more for bus fare due to fuel scarcity, which has, for weeks now, rocked the economy.
Traders cannot secure foreign exchange. They continue opting for the parallel market, pushing up commodity prices.
Power outages persist, affecting small-scale business operators.
The frustration is clear. Many people have taken to social media, criticising the government.
The situation is not new. Malawians have lived through one of the most volatile economic periods in the country’s modern history.
Between 2016 and 2026, the economy performed like a rollercoaster, where brief periods of quiet recovery were repeatedly disrupted by severe weather disasters, global market shocks, foreign exchange shortages and painful currency devaluations.
Across the entire decade, annual economic growth averaged less than 3 percent, barely keeping pace with a population expanding at 2.6 percent each year.
The decade was not entirely without bright spots, as the economy demonstrated a remarkable capacity to bounce back whenever weather conditions were favorable and global markets remained calm.
The clearest high point came in 2019, when national economic growth reached 5.4 percent.
Good rainfall produced a bumper harvest of staple food crops such as maize and strong output of tobacco, which remains the country’s primary foreign exchange earner.
During this brief period, headline inflation slowed down to single digits, offering the much-needed relief to ordinary consumers.
Another notable recovery occurred in 2021, when real gross domestic product expanded by 4.6 percent as Covid pandemic restrictions eased and the government rolled out the Affordable Inputs Programme.
In its review during that period, the Ministry of Finance noted that when agricultural productivity flourishes, the entire domestic supply chain shifts into high gear by boosting rural spending power, powering local manufacturing and stabilising food prices in urban centers.

Unfortunately, these periods of growth were regularly cut short by compounding external and natural disasters. The onset of the Covid 19 pandemic in 2020 dragged growth down to just one percent as international trade, tourism, and local business activity ground to a halt.
This was quickly followed by an unprecedented series of climate shocks that battered the country’s economic infrastructure. In 2022, Tropical Storm Ana and Cyclone Gombe damaged the Kapichira Hydroelectric Power Station, cutting off a third of the nation’s electricity supply for months.
In March 2023, Cyclone Freddy devastated the Southern Region, killing over a thousand people and destroying vital roads, bridges and farmland.
Shortly after, an El Niño-induced drought in early 2024 ruined maize harvests across central and southern districts.
The financial damage from these weather events was immense and long lasting.
In its post-disaster assessment report, the World Bank observed that Cyclone Freddy alone inflicted over $500 million in economic damage and losses on Malawi, forcing the government to divert vital development funds into emergency relief and reconstruction.
At the same time, global fuel and fertiliser prices spiked following the outbreak of the war in Ukraine.
With foreign exchange reserves dangerously depleted due to weak export earnings, the Reserve Bank of Malawi was forced to devalue the Kwacha by 25 percent in May 2022, followed by a further 44 percent devaluation in November 2023.
These adjustments caused the prices of imported goods to surge overnight, pushing headline inflation to 28 percent and creating acute shortages of fuel, medicines and essential imports.
By 2025 and 2026, the country entered a phase of strict economic repair under the government’s National Economic Recovery Plan.
The IMF highlights that restoring macroeconomic balance in Malawi requires sustained fiscal discipline, transparent debt management and structural market reforms to restore investor confidence and rebuild foreign reserves.
However, severe structural challenges remain, as public debt stands at above 91 percent of GDP, with debt service payments consuming a massive share of domestic revenues.
While the government must continue fixing macroeconomic policy and curbing public debt, public debate in Malawi has, for too long, centred entirely on blaming politicians and government departments whenever economic hardship strikes.
Pointing fingers at political leaders will not transform the national economy on its own. If Malawi is to break this cycle of economic vulnerability, citizens must become active, productive partners in the solution rather than passive onlookers waiting for government interventions.
Transformation begins with a fundamental shift in how ordinary Malawians approach agriculture and local business. Moving away from total reliance on rain-fed maize and tobacco is no longer optional.
At the same time, there is a need to build a culture of personal savings to pool resources, start small-scale manufacturing enterprises and create sustainable livelihoods.