
The energy transition faces a critical-minerals crunch by 2035 that extends beyond how much material miners can extract, as processing bottlenecks and unreliable project forecasts threaten supplies, according to GEM Mining Consulting.
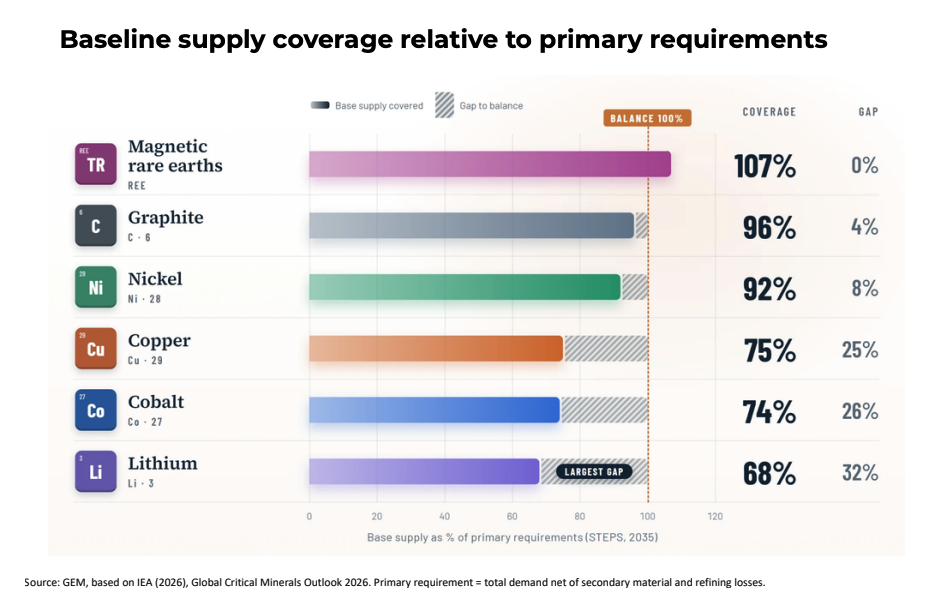
The Santiago, Chile-based consultancy estimates projected supply will meet just 68% of lithium demand in 2035, compared with 74% for cobalt and 75% for copper. Yet graphite and rare earths, where projected volumes appear more adequate, face greater supply-chain risks because processing capacity is heavily concentrated in China.
“A reserve becomes strategically relevant only when it can be financed, permitted, extracted, processed, qualified and delivered through a resilient supply chain,” GEM said in its report.
The analysis challenges a common way of assessing mineral security: comparing announced mining capacity with projected demand. GEM argues that those figures can substantially overstate the material actually available to manufacturers because mines face permitting and financing delays, ramp-up problems, metallurgical losses and customer qualification requirements.
Supply reality
To account for those risks, GEM developed two measures: a Volume Scarcity Index tracking the gap between supply and primary demand, and a Supply Chain Fragility Index measuring factors including processing concentration, technological dependence and geographic risk.
Lithium emerges as the most constrained mineral by volume, scoring 80 out of 100 on GEM’s scarcity index. Cobalt scores 65, while copper registers 62.
The picture changes when supply-chain vulnerability is considered. Rare-earth magnets score 95 out of 100 on GEM’s fragility index and battery-grade graphite scores 89, despite projected supply covering 107% and 96% of their respective demand in 2035.
Cobalt scores 78 for fragility, while nickel reaches 66 because processing is concentrated in Indonesia and China. Copper, despite its looming physical deficit, scores a comparatively low 36.
That distinction means the biggest mine-supply deficit is not necessarily the greatest strategic vulnerability. For lithium, cobalt and copper, GEM sees the priority as bringing dependable new mine production into operation. For graphite and rare earths, diversifying refining and processing outside dominant producing countries is more important.
Rare earths illustrate the problem. GEM estimates diversified magnet supply outside China would cover only 15% of global demand, leaving consumers exposed even if aggregate worldwide production appears sufficient.
Capacity gap
Announced project capacity can also give policymakers and investors a misleading impression of future mineral availability, GEM said.
The consultancy calculates that a hypothetical project designed to produce 100,000 tonnes annually may ultimately provide only about 60,200 tonnes of reliable, saleable output after adjusting for development and operating risks — a reduction of nearly 40%.
The losses can accumulate throughout a project’s development and production chain. Permitting and financing can delay construction, commissioning can push back output, mines need time to reach nameplate capacity and metallurgical recoveries reduce the amount of usable material produced.
Material that leaves a processing plant may face another hurdle: meeting the chemical and technical specifications required by battery, magnet and other manufacturers.
The findings suggest governments seeking secure critical-mineral supplies may need to look beyond headline resource estimates or planned mine capacity. Processing infrastructure, financing, permitting, technical performance and the ability to deliver qualified material all determine whether underground resources become usable supply.
For miners and investors, GEM argues that this changes how projects should be valued. A smaller deposit with proven processing, infrastructure and customers may carry greater strategic importance than a much larger resource without a reliable route to market.
The energy transition’s mineral race, in other words, may be decided as much by what happens after the ore leaves the ground as by how much miners can extract.