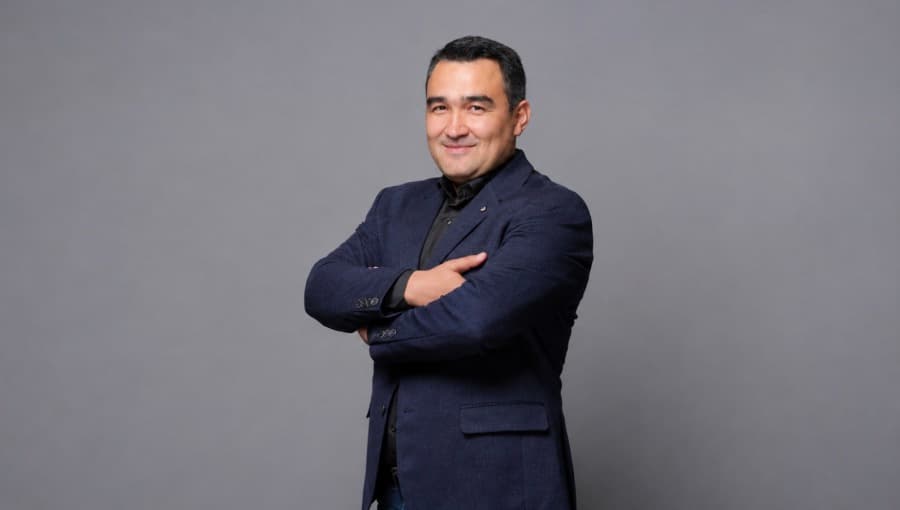
Artificial intelligence could eventually handle most routine financial transactions, from paying utility bills and monitoring debt deadlines to negotiating prices, but Click is taking a cautious approach to deploying the technology in finance, its co-founder Rustam Fayziev told Intellinews in an interview.
Click, Uzbekistan’s largest digital payments platform, has more than 24mn users and is already using AI across most of its operations, including HR, marketing, legal work, administration and its call centre. Fayziev noted that the company was nevertheless keeping people at the centre of financial decision-making, reflecting the higher risks associated with mistakes in the sector.
“We are still at a stage where artificial intelligence should be understood as an assistant and an intelligent tool, not as an autonomous individual, superintelligence or artificial general intelligence,” Fayziev said.
Human oversight remains central
Click follows a “human in the loop” approach under which employees review AI-generated analysis and recommendations and remain responsible for final decisions.
The company uses AI to help develop automation scripts, but has not introduced autonomous AI agents to run financial processes without human approval.
“AI helps employees improve the quality, speed and efficiency of their work, but it does not change where responsibility lies,” Fayziev said.
AI is already being used across Click’s operational departments. In its call centre, for example, speech analytics allows the company to analyse calls, identify recurring problems and better understand customer complaints.
The technology is also increasingly being incorporated into product development. Fayziev highlighted that Click ultimately wants developers to become “orchestrators” of AI agents that participate directly in building products, while retaining human oversight.
From payment app to everyday language
Click’s expansion has coincided with a broader transformation in how Uzbek consumers pay for goods and services.
The company now has more than 24mn users, but Fayziev sees its influence also reflected in how its name has entered everyday language. Consumers increasingly ask merchants, “Do you have Click?” rather than simply whether they accept transfers.
The shift reflects the rapid adoption of digital payments in Uzbekistan. Around 15 years ago, bank cards were relatively uncommon, while the country now has about 75mn cards for a population of roughly 38mn.
Fayziev sees a similar leap taking place with artificial intelligence, particularly as the technology moves from chatbots and large language models towards autonomous or semi-autonomous agents.
AI agents could become the new payment intermediary
Payment systems are already beginning to develop tools that allow AI agents to make transactions on behalf of users. Fayziev expects the model to initially rely on strict limits set by account holders, but believes those boundaries could expand as consumers become more comfortable delegating financial tasks to software.
An AI agent could eventually negotiate prices, monitor debt repayments and pay utility bills and other recurring expenses automatically.
“That may fundamentally change the payments industry,” Fayziev said.
Advertising could also change if consumers increasingly delegate routine purchasing decisions to AI. Companies may eventually market products to a consumer’s AI agent rather than directly to the individual, as the agent decides which products or services to buy.
The same technology could make personal financial management more accessible. Financial advisers and accountants remain unaffordable for many consumers, but AI systems trained on financial expertise could help people prepare budgets, monitor obligations and manage recurring expenses.
Fayziev noted that consumers would initially need to retain control by setting limits and reviewing the actions of their agents rather than giving them unrestricted access to their money.
Security and responsibility
The rise of agentic payments will also require a new generation of security systems, Fayziev added.
Just as the introduction of bank cards brought new anti-fraud mechanisms, payments made by AI agents will require safeguards tailored to the technology.
Responsibility for an erroneous transaction would depend on how it occurred. If an AI agent acted within the authority granted by its owner, the user would ultimately be responsible for that transaction. If hackers stole credentials or tokens held by a service provider and used them to access an agent, responsibility would instead fall on the compromised infrastructure.
This division of responsibility could make the security of AI-payment infrastructure as important as the technology itself.
Central Asia could leapfrog to AI-native finance
Fayziev believes Central Asia could become an early adopter of AI-native financial technology because the region has repeatedly skipped intermediate stages of technological development.
Uzbekistan moved relatively quickly from limited use of bank cards to widespread digital payments and from traditional communications towards smartphones and messenger platforms, particularly Telegram. Email never became as deeply embedded in professional communication as it did in many developed markets, according to Fayziev.
A similar leap could now occur with AI agents.
Yet the region lacks some of the infrastructure needed to realise that potential. Central Asian banks are not connected to several major international payment platforms, including Apple Pay, Samsung Pay and Google Pay, while banks, payment processors and mobile operators do not yet have official connectors to AI platforms such as ChatGPT, Claude and Gemini.
The region therefore has strong consumer readiness for new digital technologies, but its AI and payments infrastructure remains a constraint.
AI could cut product development from months to days
For Click, the transition towards becoming an AI-native company could ultimately involve a much broader restructuring than simply automating existing tasks.
Fayziev stressed that most current AI-native companies are start-ups built around small teams and large numbers of AI agents, while there are still few examples of large corporations successfully making the same transition.
An AI-native company could eventually have only a handful of human employees working alongside hundreds or thousands of AI agents, he said. That would force companies to rethink employee roles, organisational structures and established development methodologies such as Scrum and Agile.
Click has already seen a dramatic reduction in the time required to develop a minimum viable product. The process previously took about four months. After the company began using a start-up-style approach to product development, that period fell to about one week.
Fayziev compared the change to a 3D printer capable of constructing a house overnight. When construction takes months, repairing a single part of an existing building makes sense. But if an entire structure can be rebuilt overnight at a much lower cost, rebuilding it from scratch may become more efficient.
The same logic, he said, is beginning to apply to software.
The biggest impact of AI may therefore not be the automation of existing processes, but the need to redesign those processes around technology that can perform tasks dramatically faster and more cheaply.
For established companies such as Click, that could mean that becoming AI-native is less about adding AI to existing operations and more about deciding which parts of the existing business should be rebuilt altogether.