The International Monetary Fund has advised the South Korean government to set aside the tax revenue gains from the semiconductor boom for future economic crises rather than spend them now. The fund said Korea should build fiscal room in case the artificial intelligence investment boom falters. It stressed that with rising global sovereign bond yields pushing up government interest costs, the revenue windfall from the boom should be used to strengthen fiscal soundness.
In its October Global Financial Stability Report released on the 13th, the IMF identified an AI-driven market correction, a surge in sovereign bond yields and cyber threats as the three biggest risks to global financial markets. While the global economy and financial markets are holding firm, the report said, the capacity to absorb shocks has weakened as reliance on the AI industry has grown and government debt has accumulated.
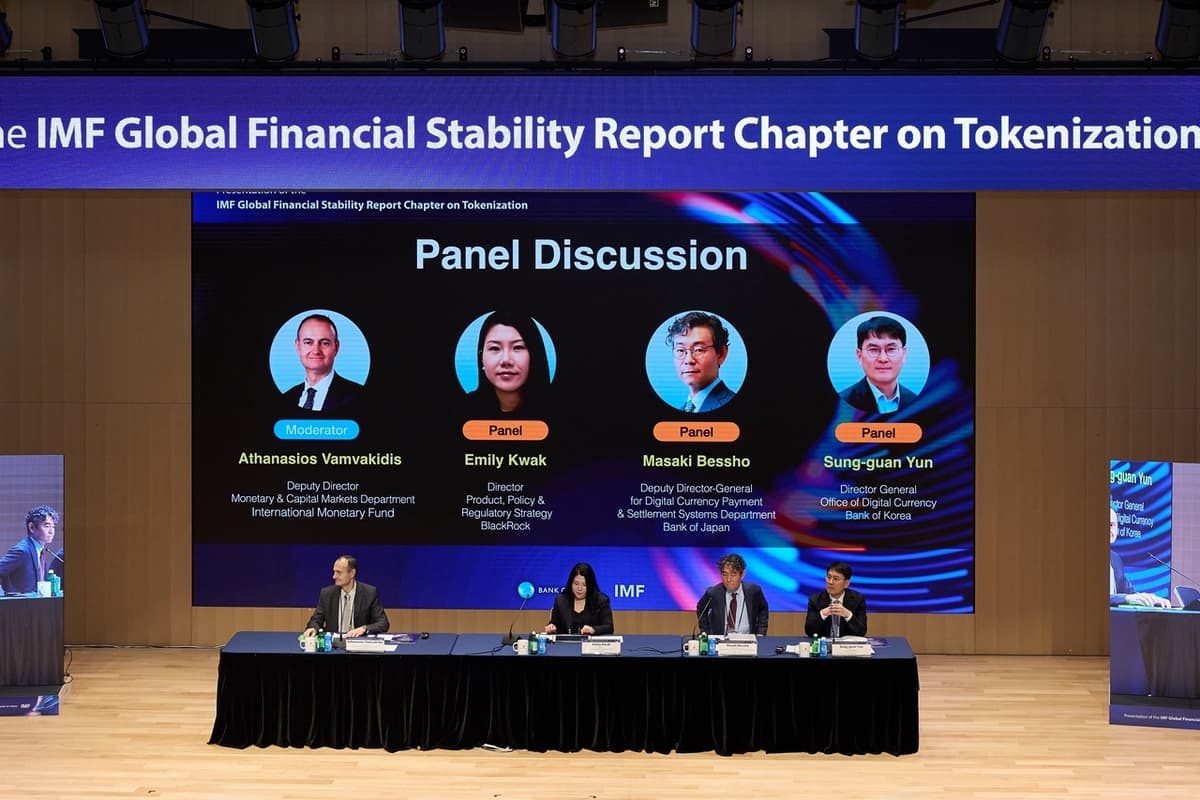
Athanasios Vamvakidis, an IMF deputy director, praised Korea's semiconductor industry and AI competitiveness but called for prudent use of the additional tax revenue, speaking in an interview with Korean media on the 8th following a presentation on the GFSR's tokenization chapter at an annex of the Bank of Korea. Noting that he was not familiar with the details of a case in which the government used revenue secured from the chip boom to redeem about 5 trillion won in treasury bonds, he said additional fiscal revenue should first be considered for saving in preparation for a downturn.
Vamvakidis said Korea is at the forefront of AI development and its stock market has performed well, and he assessed that those gains are translating into substantial fiscal revenue. But he stressed the need to distinguish whether the revenue increase from the chip boom is temporary or lasting. If the additional revenue proves stable, its use for future generations could be considered, he explained, but a hasty expansion of spending could create economic imbalances.
He also emphasized coordination between fiscal and monetary policy, saying that saving in good times is what makes spending possible in difficult ones. If the government expands fiscal spending while the central bank tightens to curb inflation, the two policies can work against each other.
Behind the IMF's emphasis on securing fiscal room lies the uncertainty surrounding the AI investment boom. Vamvakidis said share prices of AI-related companies are not necessarily excessively overvalued, but pointed out that the economy and financial markets are far too dependent on AI. Comparing the situation to putting all one's eggs in a single basket, he warned that if AI investment returns fall short of expectations, the shock could spread to financial markets and the real economy.
He singled out as a risk factor the circular financing structure in which large technology companies invest in AI firms, which in turn purchase semiconductors and cloud services. According to the report, 13 publicly disclosed circular financing deals since 2023 are linked to about $300 billion in equity investment and $650 billion in debt financing. If investment returns disappoint, the analysis found, a contraction in funding and a decline in revenue could occur at the same time.
Rising sovereign bond yields are another variable adding to fiscal strain. The IMF attributed this year's rise in yields to higher energy prices stemming from the war in the Middle East and shifts in the outlook for monetary policy at major central banks. Countries with high government debt face a greater risk of falling into a fiscal vicious cycle as rising yields increase interest costs and refinancing burdens.
The IMF assessed that high government debt and inflation have left countries with less room for fiscal and monetary policy responses than in the past. Because it has become harder to deploy large-scale fiscal support once a crisis hits, the fund said, buffers should be built in normal times. The message is read as applying to Korea as well, where the semiconductor and AI boom is driving higher tax revenue: medium- to long-term fiscal stability should take priority over short-term fiscal expansion.