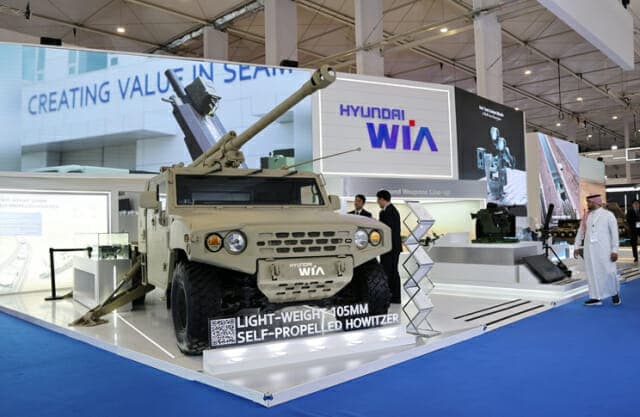
Hyundai Motor Group is consolidating its ground weapons business, including tanks and artillery, under Hyundai Rotem (064350.KS). The plan calls for Hyundai Rotem to strengthen its competitiveness through vertical integration in defense, while Hyundai Wia (011210.KS) concentrates on future mobility businesses such as electrification and robotics.
Hyundai Rotem said in a regulatory filing on the 19th that it will acquire Hyundai Wia's special business division. The acquisition covers the entire business, including the operating assets and liabilities of the division, which handles defense operations. The deal is valued at 358.386 billion won, derived from the division's operating value of 480 billion won minus items such as 117 billion won in land and buildings that will be leased.
"Vertical integration in defense will secure price competitiveness and expand localized items, strengthening our export competitiveness," Hyundai Rotem said. Hyundai Rotem, which exports the K2 tank, will now also produce large-caliber artillery, including barrels for the K9 self-propelled howitzer and main guns for the K2 tank, previously made by Hyundai Wia's special business division.
Hyundai Wia is divesting its defense business, the operation on which the company was founded, after spinning off its machine tools business in July last year. "This is a decision to realign our business portfolio around future mobility, including electrification and software-defined vehicles," a Hyundai Wia official said. "It is a strategy of selection and focus based on our core mid- to long-term strategy." The proceeds will fund investment in growth businesses such as constant velocity joints, thermal management systems and robotics.
Hyundai Rotem plans to relocate production plants after completing the acquisition. If a special resolution passes at Hyundai Wia's extraordinary shareholders meeting on Nov. 27, the acquisition will close in the first quarter of next year. All employees will be retained.
Separately, Hyundai Rotem said the same day that third-quarter operating profit fell 11.0% from a year earlier to 247.1 billion won. Revenue rose 0.1% to 1.6207 trillion won. Both figures fell short of market expectations of 1.8005 trillion won in revenue and 276 billion won in operating profit.
The shortfall is attributed to a combination of factors, including lower margins from the won's appreciation, an increase in less profitable domestic orders, and the deferral of expected orders due to delays. The order backlog stood at 29.142 trillion won at the end of the third quarter, down 1.2626 trillion won from 30.4046 trillion won at the end of the second quarter.