In the seven years since TOC Americas last took place in Cartagena, global laden container volumes have slipped about 10% below where they would have been without the multiple disruptions that have hit the industry since 2018, according to Dinesh Sharma, director at Drewry Maritime Advisors.
Sharma’s research measured growth from 2018 against forecasts of where the industry had imagined it would be today last time they met in Cartagena. Predicting the future, he said, was and is not easy. Transshipment hubs grew by about 6% a year on average over that period, against roughly 3% for gateway ports and 1.5% for the underlying economies they serve. The inefficiency, he said, is no longer contained at the big transshipment hubs: it is flowing through to gateways too, leaving Latin America’s overall throughput an estimated 2–3% below his 2018 projection. Performance varies sharply by market, Sharma added: Mexico and Brazil are growing more slowly, while Colombia is seeing strong consumer spending and rising real wages, with Peru, Chile and Ecuador following a similar pattern.
Offering a geopolitical insight into the direction of travel, Henry Ziemer, of the Centre for Strategic and International Studies (CSIS) in Washington, said the current political situation only further complicated the commercial picture. Ziemer argued the Americas are becoming strategically important precisely because the rest of the world has become more violently contested. “I think the Americas are becoming a key hedge, geopolitical hedge, in a more contentious world,” he said.
A tug of war over ownership
That attention, Ziemer said, is not without cost. Washington’s growing interest in the region’s infrastructure raises the odds that port decisions get caught up in politics rather than commercial logic. “Who controls ports and maritime infrastructure matters now more than ever,” he said, warning that US agencies do not always have full visibility of who actually owns or runs a given facility. “Ports can sometimes be caught in a bit of a tug of war where different agencies are acting under imperfect information about ownership structures, about operational control,” he said.
Who wins Panama’s next tenders
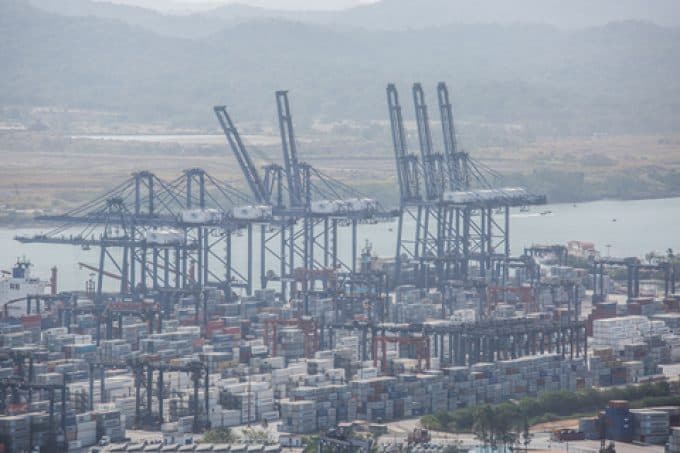
Ziemer’s clearest example was Panama, which is running caretaker arrangements at Balboa and Cristóbal through APM Terminals and TiL while preparing to tender two new ports. “There’s an expectation from the administration in the United States that a U.S. company will be basically receiving one of those ports,” he said. He questioned whether that expectation matches the market: “Will they be the most competitive option? Will they adhere to the specifications that the Panamanian government is looking for?” For Ziemer, that is the sharper risk, not the cost of capital. “The real dilemma is not so much in the financing side, but in the question of which countries and which companies are delivering the infrastructure capability,” he said.
Reading the money, not the flags
Other panelists read the same uncertainty in more commercial terms. Natalia Gil, economic investigations leader at Grupo Puerto de Cartagena (GPC), told the panel that capacity figures increasingly conceal differences in connectivity and reliability. Her team’s analysis of routes across the Caribbean and Panama between 2023 and 2026 found that a container line changes a route, a service or a parameter of a service on average every 3.9 days, with the toughest quarters for Cartagena, including the Panama Canal drought and disruption around the Strait of Hormuz and the Suez Canal, also the quarters when the port won the most new services.
Nicolas Romero, regional head Latin America at Pacific International Lines (PIL), said the line is redesigning its ships around the region’s constraints rather than waiting for ports to catch up: “we take the challenge to adapt the fleet to the needs of the terminal.” Enrique Piqueras, chief executive of PSA Panama, argued the bigger bottleneck in most Latin American countries sits outside the terminal gate altogether, a problem he said he had seen repeat in Peru, Colombia, Argentina and Panama. “Competitiveness isn’t given by the port … it’s given by the environment,” he said.
Asked by an audience member from the Panama Canal Authority how to read where geopolitics is heading, Ziemer pointed away from announcements and towards capital flows, and towards countries with existing ties to Washington such as Panama, Colombia and Mexico. Sharma agreed the political backdrop was real, whoever occupies the White House. “As much as you like the current administration or dislike the current administration, what this has resulted is in a great big shakeup,” he said, pointing to a shift from integrated tariff structures towards shorter-lived bilateral trade frameworks that add short-haul volume to ports without necessarily adding profit. But asked where capital was actually landing, he pointed to his own data rather than Washington’s intentions: “If we just look at the expansions happening within Latin America, the vast majority of them are brownfield expansions.”
The gap between the two readings showed again when Sharma was pressed on how he weighs geopolitics against his own projections. “We just take what Henry says and we convert them into numbers,” he said.