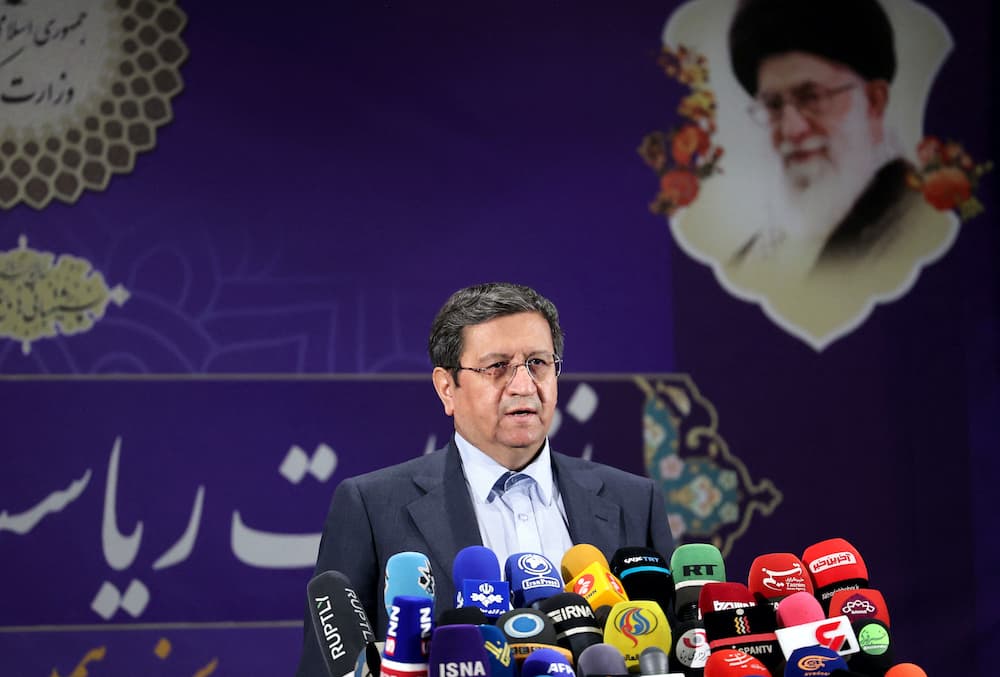
US claims that Iran’s economy is collapsing are an illusion, the governor of Iran’s central bank said on Wednesday, as Tehran faces a US naval blockade aimed at driving its oil exports to zero and draining state coffers.
Washington reinstated its blockade of Iranian ports in July and launched “Operation Economic Outcast” on Aug. 24, a campaign aimed at severing Iran’s remaining financial and commercial links with the global economy.
According to energy intelligence platform Vortexa, Iran’s seaborne crude exports fell to zero in the second week of September from a 14-day average of 230,000 barrels per day at the start of the month, and remained there as of Oct. 5.
In September, Washington expanded the campaign to target Iranian airlines, further isolating the country and making links to the outside world more limited and costly.
US pressure has coincided with a sharp fall in the Iranian rial. According to exchange-rate data from Iranian currency tracker Bonbast, the rial has lost nearly 35 percent of its value against the US dollar since July.
Speaking at an International Monetary Fund meeting in Bangkok, Abdolnasser Hemmati said that the central bank was prioritizing curbing inflation, stabilizing inflation expectations, preserving financial stability and maintaining banking and payment services, while securing foreign currency for medicine and essential goods. Annual inflation reached 73.6 percent in September, according to the Statistical Center of Iran.
Iran’s central bank launched a program in late September to sell up to $2 billion through state banks to support the rial.