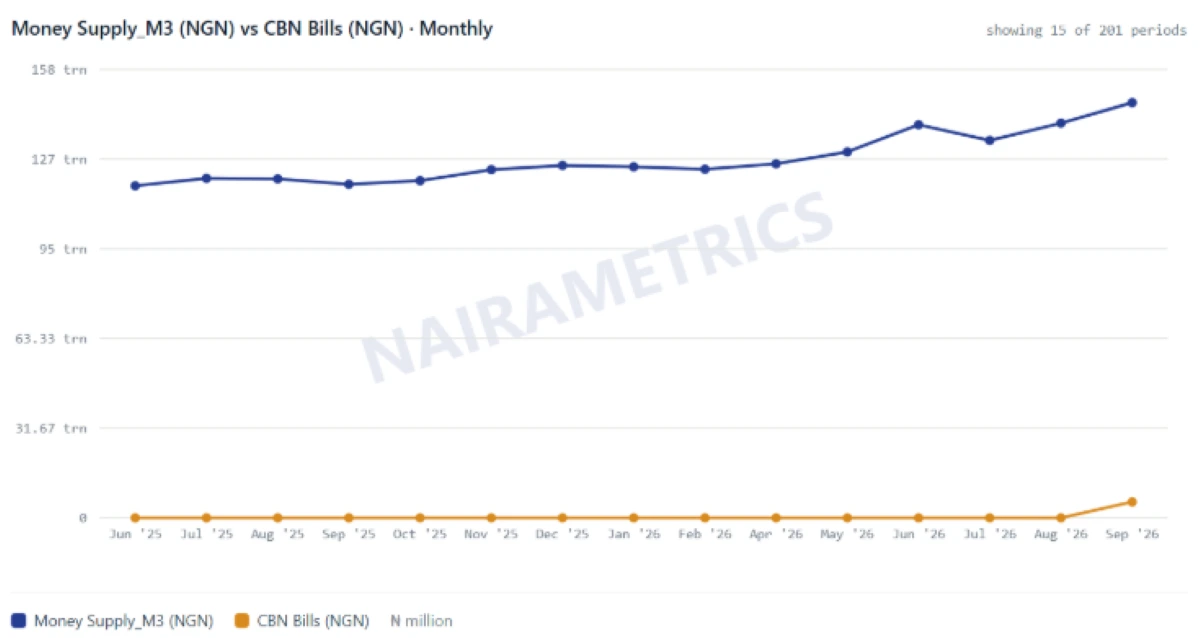
Central Bank bills held by money-holding sectors surged to N5.60 trillion in September 2026 from just N9.68 billion in August, accounting for 74.4% of the monthly increase in the country’s broad money supply.
Data from the Central Bank of Nigeria (CBN) show that the value of these bills increased by N5.59 trillion within one month, while broad money supply, measured by M3, rose by N7.51 trillion to N146.60 trillion.
The development presents a significant shift in the composition of Nigeria’s monetary aggregates, with the increase in CBN bills accounting for the bulk of the monthly expansion in M3.
Although broad money supply increased by 5.40% month-on-month to N146.60 trillion, the narrower M2 measure, which excludes CBN bills, rose by a modest 1.38% to N141.00 trillion from N139.08 trillion in August. The increase in headline money supply was driven primarily by the sharp rise in CBN bills.
CBN bills account for bulk of monthly increase
The CBN’s monetary statistics distinguish between M3 and M2, with CBN bills held by money-holding sectors included in the broader M3 measure.
- In September, CBN bills rose to N5.60 trillion from N9.68 billion in August, representing an increase of approximately 57,744% month-on-month.
- The increase compares with the N7.51 trillion rise in broad money supply over the same period.
- Consequently, the increase in CBN bills accounted for approximately N5.59 trillion of the monthly expansion in M3, equivalent to 74.4% of the total increase.
By comparison, M2 increased by N1.92 trillion, representing the remaining 25.6% of the increase in broad money supply.
The sharp increase suggests the importance of distinguishing growth in the monetary aggregate from an actual increase in funds available for transactions, savings, and credit creation.
Notably, the increase in CBN bills does not establish that an equivalent amount of fresh cash is pumped into the economy. CBN bills are interest-bearing instruments that can be used for liquidity management, while their inclusion in M3 reflects the composition of the monetary aggregate.
M2 records more moderate expansion
While CBN bills recorded an exceptional increase, Nigeria’s M2 money supply rose by 1.38% month-on-month to N141.00 trillion in September from N139.08 trillion in August.
On a year-on-year basis, M2 increased by 19.72% from N117.77 trillion recorded in September 2025.
The narrower monetary aggregate comprises narrow money and quasi-money, capturing currency and deposits alongside other relatively liquid savings and deposit balances.
- Within M2, quasi-money increased by 1.03% month-on-month to N96.95 trillion from N95.97 trillion, while narrow money rose by 2.17% to N44.05 trillion from N43.11 trillion.
- Narrow money, which captures more immediately spendable monetary balances, therefore recorded a stronger monthly increase than M2.
- Currency held outside banks increased by 1.00% to N4.92 trillion from N4.87 trillion, while demand deposits rose by 2.32% to N39.12 trillion from N38.24 trillion.
These movements point to an increase in cash holdings and transaction balances during the month.
Government credit rises as private-sector credit declines
Within the CBN’s monetary statistics, net domestic credit increased by 4.96% month-on-month to N123.34 trillion in September from N117.51 trillion in August.
- The increase was accompanied by a significant rise in credit to the government, which grew by 19.26% to N39.40 trillion from N33.04 trillion.
- This represented an increase of approximately N6.36 trillion within one month. On a year-on-year basis, credit to the government rose by 63.09% from N24.16 trillion in September 2025.
- In contrast, credit to the private sector declined by 0.64% month-on-month to N83.93 trillion from N84.47 trillion.
- Despite the monthly decline, private-sector credit remained 15.73% above its September 2025 level, rising from N72.53 trillion to N83.93 trillion.
The contrasting movements provide another important dimension to the monetary data. While lending to the private sector remained higher than a year earlier, its monthly decline coincided with a sharp expansion in credit to the government.
Net foreign assets decline
The CBN data also show a decline in net foreign assets, which fell by 13.57% month-on-month to N30.90 trillion in September from N35.75 trillion in August.
- Compared with N41.66 trillion in September 2025, net foreign assets declined by 25.83%.
- In contrast, net domestic assets increased by 11.97% month-on-month to N115.70 trillion from N103.34 trillion and rose by 51.99% year-on-year.
The figures indicate a shift in the composition of the monetary survey towards domestic assets, even as net foreign assets contracted.
Backstory
The sharp increase in CBN bills recorded in September is attributable to the apex bank’s liquidity-management operations, as it continued to use Open Market Operations (OMO) bills to absorb excess funds from the financial system.
Nairametrics reported that the CBN sold approximately N17.51 trillion in OMO bills during September 2026, while about N10.89 trillion in maturing bills was repaid, leaving a net liquidity withdrawal of approximately N6.62 trillion.
The operations suggest that the apex bank was actively managing liquidity during the month.
What the figures mean
The September data highlight the importance of looking beyond the headline money supply figure when assessing monetary conditions in Nigeria.
Although M3 increased by 5.40% within the month, the exceptional rise in CBN bills accounted for most of the expansion, while M2 grew by 1.38%.
Changes in monetary aggregates do not automatically translate into higher consumer prices, increased lending, or stronger economic activity. The eventual impact depends on money demand, credit conditions, the velocity of circulation, and the supply of goods and services.
For policymakers, the composition of money supply is particularly relevant when balancing inflation control with the need to support productive economic activity.
For now, the figures point to an unusually large contribution from CBN bills, alongside rising government credit, a marginal monthly decline in private-sector credit and weaker net foreign assets.