Carney is doing what he has always done: defend the interests of the international rentier class.
Canadian Prime Minister Mark Carney has reportedly been trying to warn the British government off nationalising Thames Water, even on a temporary basis, with a threat that it could damage foreign investment in Britain. According to the Daily Telegraph, Canadian officials are increasingly concerned that any move by PM Andy Burnham to place Thames Water under state control “could result in heavy losses for overseas investors”:
Ottawa is thought to have cautioned that any expropriation of privately owned assets without accompanying compensation could jeopardise further investment in the UK economy. Canada’s so-called Maple Eight pension funds, and its banks have poured tens of billions into airports, ports, the energy sectors, key utilities and property.
The dramatic intervention underscores mounting anxiety about the Prime Minister’s hostility towards the private sector. Mr Burnham has promised to “end neo-liberalism” and undo Margaret Thatcher’s legacy of privatisation and deregulation.
Yet private property rights are a fundamental pillar of the UK’s legal and economic system, and one of the key protections that make Britain a top destination for overseas capital.
Ottawa was lobbying primarily on behalf of the Royal Bank of Canada (RBC), the country’s national bank champion. It is not known whether the Canadian officials were acting on the instructions of RBC senior figures or independently.
The discussions are understood to have occurred in recent weeks. Mr Carney met the Prime Minister on a visit to Liverpool last month where the pair watched Everton football club, who they both support.
RBC is a senior creditor to Thames Water, and is among a consortium of more than 100 financial institutions that has proposed a £16bn rescue package in which around a third of the supplier’s borrowings would be written off in return for ownership.
As Yves might say with a sardonic smile, “quelle surprise”. Mark Carney, an ex-Goldman Sachs banker and former central banker at two G20 central banks (the Bank of Canada and the Bank of England), is lending a helping hand to Canada’s largest lender by trying to nip in the bud any attempt, however unlikely, by a British government to renationalise an insolvent water company.
Carney may have gained plaudits around the world for his opposition to Trump and was even tipped to win the Nobel Peace Price a few weeks ago (despite supporting both of the big wars of our time as well as doing nothing to oppose the genocide in Gaza), but let’s be real: he is a self-proclaimed elitist and globalist. He was a member of the WEF at Davos, president of the Royal Institute of International Affairs at Chatham House in London, and a member of the board of the Peterson Institute for International Economics in Washington.
In trying to prevent the UK’s nationalisation of Thames Water, Carney is doing what he has always done — i.e. defending the interests of the global rentier class. The problem for Carney, and the rentier class he represents, is that the proposed alternative to nationalisation — a creditors deal that would see a sizable chunk of Thames Water’s roughly £20 billion of debt written off — is an even worse deal than the current arrangement.
An Anomaly in the World
When it comes to water provision and management, England is an anomaly in the world. It is one of only two countries where water, the most essential of all natural resources, is owned exclusively by private companies for profit. The other country is Chile. According to The Guardian, 90% of countries run state-owned operations.
In the case of Chile, it was the Pinochet government that drew up the “Código de Aguas” (water code) in 1981 — with input, of course, from the Chicago Boys. The post-dictatorship administration of Eduardo Frei Ruiz-Tagle completed the job in 1998 by privatising regional water and sanitation companies.
In the case of England, it was Margaret Thatcher who privatised the whole lot in 1989, promising that a fully privatised water sector would deliver higher investment. It hasn’t quite worked out that way. Indeed, as a 2024 Guardian editorial points out, the “decision to put water – a natural monopoly – in private hands defied the Thatcherite logic of competition and efficiency”.
There was never any possibility of pitting rival companies against each other to raise standards. No other water supply is competing for a household’s business.
Instead, private water monopolies have been used as vast enrichment vehicles for international investors — including pension funds, infrastructure funds and, ironically, many sovereign wealth funds. In 2002, ministers were warned in a report, which remained secret for many years, that privatisation would let large external private equity shareholders load water companies up with debt and the financial regulator Ofwat would end up losing regulatory control of the sector.
Which is pretty much what happened. In 2017, a report by Greenwich University found that the nine regional water and sewerage companies in England — three of which are publicly listed and six of which are owned privately — have invested no significant new shareholder equity but extracted nearly all of their post-tax profit as dividends. The study’s authors calculated the cost of privatisation at around £2.3 billion a year — over £100 for each household.
From the FT:
Greenwich researchers said the cost of maintaining and improving water and sewer infrastructure has been paid for almost entirely by an increase in debt, which has risen from almost zero at the time of privatisation to nearly £40bn in 2016. The interest payments on the debt are higher than what would be paid by the public sector, which can borrow more cheaply.
Together, the £1.8bn in dividends and the extra £500m of debt interest payments each year pushed up bills for each of England’s 23m households by about £100 a year, the researchers said.
“If all we are getting is debt, while we are financing company dividends, it clearly would have been better for these utilities to be in the public sector,” said Dr Bayliss…
The owners of the nine companies — many of which are overseas investors, including sovereign wealth funds — paid out £18.1bn in dividends in the 10 years to 2016, even though post-tax profits amounted to £18.8bn during the decade, according to the researchers’ analysis of their financial reports.
Three companies — Anglian Water Group, Severn Trent Water and Yorkshire Water Services — have paid out more in dividends than their total pre-tax profits over the past decade, a situation Dr Bayliss said was not “economically sustainable”.
And so it has proven. In April 2024, the parent company of Thames Water, the largest of the nine companies which manages all the water infrastructure for 15 million people in South East England, defaulted on its debt. Since then the company has teetered on the edge of bankruptcy as the government and its investors try to find a workable solution.
Michael Hudson explained how this all unfolded in a 2023 interview with Robinson Edhardt:
The buyers of Thames water simply borrowed money and they took all the money that was borrowed, paid themselves the dividend, and did not fix the pipes that are leaking sewage into the water systems, beaches…they didn’t fix the pipes from leaking, they didn’t really put much investment in at all.
Their role was to destroy the English water system and loot it and leave it a mess while taking out a huge amount of money pretending to spend the money back into the real economy. So the fact is the money didn’t trickle down from the owners of Thames’ water or from the corporate raiders in the United States. That’s why they’re called raiders. They pay themselves and they then raise prices if they can.
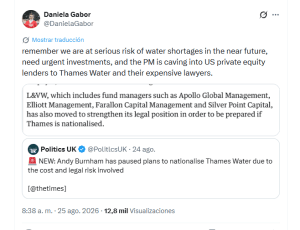
The most obvious solution to the UK’s growing water crisis would be to renationalise Thames Water. This was one of the policy pledges made by the UK’s latest Prime Minister Andy Burnham in his campaign for the Makerfield by-election. However, Burnham has so far failed to follow through on the proposed plans to place Thames Water into a special administration regime — which, let’s be clear, would only be a temporary arrangement.
On the campaign trail, Burnham told voters that “there’s a very strong case for public ownership [for Thames Water] to sort out its problems”. However, after taking over as PM, Burnham quickly shelved those plans “amid concerns about the cost and the legal risk involved”, according to Reuters. The “legal risk” presumably refers to the potential ISDS cases that could be brought against the UK, and ISDS cases tend to lean in favour of investors.
The privatisation of water, Burnham said, will be difficult to reverse.
Weeks later, Burnham flip-flopped again, saying he would legislate to repeal Thatcher’s “ideological ban” ban on public ownership of water companies, promising a ten-year route to “a very different water system”.
Whether Burnham will actually follow through on his proposed repeal of the ban is anyone’s guess. One thing that is clear is that if he does, investors that have poured money into English water companies will be up in arms, 70% of whom are from overseas.
They include the Abu Dhabi Sovereign Wealth Fund, which is already at loggerheads with the Burnham government over the Manchester City cheating scandal, the Hong Kong based investment giant CK Hutchinson, and, of course, Canadian banks and pension funds. According to The Guardian, the country with the strongest foothold in English water companies is the US, with investment firms owning nearly 17% overall. Again, quelle surprise!
“A Reshuffling of Chairs on the Deck of the Titanic”
The first Thames Water rescue deal was quickly rejected. As Left Foot Forward reports, it included a one-quarter haircut of the firm’s debt. However, a “full return to legal, regulatory and environmental compliance” would not take place until at least 2035-2040, meaning Thames Water could continue polluting rivers until then. Nor would there be much impetus to fix leaking pipes. The proposed deal would also see customers’ bills hiked by a further 35% by 2030.
In other words, none of the problems would be fixed while the costs to customers would continue to rise. It is no wonder, therefore, that a January poll carried out for anti-privatisation group We Own It found that a majority of customers (54%) think the water regulator Ofwat should reject the creditors’ deal and put Thames Water into special administration.
The SAR proposal would transfer the costs of running the company to the taxpayer, with Thames Water claiming the bill could come to £2bn. In recent months, the group of creditors pursuing a rescue bid for Thames Water have offered to overhaul the stricken utility’s board as well as increase the debt write-down to £10 billion.
Cat Hobbs, the director of We Own It, said:
“This is absolutely absurd. A cosy stitch-up that has nothing to do with the interests of the 16 million people who depend on Thames Water. This amounts to nothing more than a reshuffling of chairs on the deck of the Titanic.”
As Richard Murphy noted in an April 2024 post, the banks and funds that “invested” in Thames Water, which in turn never properly invested in South East England’s water infrastructure, knew the risks they were taking, or at least should have done:
As I demonstrated in the report that I wrote on the water industry last year, quite literally every penny that this sector has borrowed this century has been used to make payment of dividends to shareholders. Even more money was used to pay interest to those from whom funds had been borrowed to finance these dividends. The sector’s own net investment in new capital to provide water to the people of this country over the period that I reviewed was precisely nothing.
My point is a quite straightforward one. If I could work this out, then so could anyone. In that case, any institution lending money to these companies or providing them with their capital clearly knew the risk that they were taking, which was that the industry that they were providing with funds was not using those for gainful purposes but was instead exercised in undertaking financial engineering for the benefit of financiers, but not for the country as a whole.
Given that this risk was always apparent, known about, and widely talked about, the fact that loans have now failed can come as a surprise to nobody. This whole industry is environmentally insolvent, as I have described it, but is also now tottering on the brink of financial insolvency as well.
In that case, obsessing about how debt might be repaid is absurd. That debt never funded useful activity. As a result, the means to make its repayment do not exist. It is not repayable, as a matter of fact. That is why insolvency happens, and these companies are bust…
Thames Water is bust. Its shareholders need to accept that they have lost their money. Most, if not all, of its debt financiers need to do the same thing. They took the risk of losing their money. They have done so. That’s how markets work, unless you are a pro-market extremist, of course, when the idea that the market might fail cannot be tolerated.
Which is where we are now. If it was Thatcher’s infamous “there is no alternative” (TINA) doctrine that got us here, it is the likes of Carney who are now trying to ensure that “there is no way out” — or TINWO, an admittedly less catchy acronym — of the current neoliberal paradigm, even as the system itself is showing more and more signs of collapse.

Whatever the likes of Carney may say, there must be a way to correct course, especially if what is at stake is the sustainable management of the most important of all natural substances for human survival. On September 2, when we featured on our links page an article about Burnham’s latest admission that “the privatisation of water firms would be difficult to reverse”, long-time reader Ignacio responded with the only sane response:
Water is essential. Isn’t it? There you have a strong reason to reverse privatisation.
Reader vao then provided the cherry on top:
Difficult to reverse? Water is essential. Isn’t it? There you have a strong reason to reverse privatisation.
Even easier: make water a “national security” question — and presto, who would argue against nationalization and strong state-control when the defense of the nation and its precious fluids is at stake? Even better, one could argue the ensuing costs fall outside the usual budgetary constraints, because national security and all that.
I doubt it will happen.
