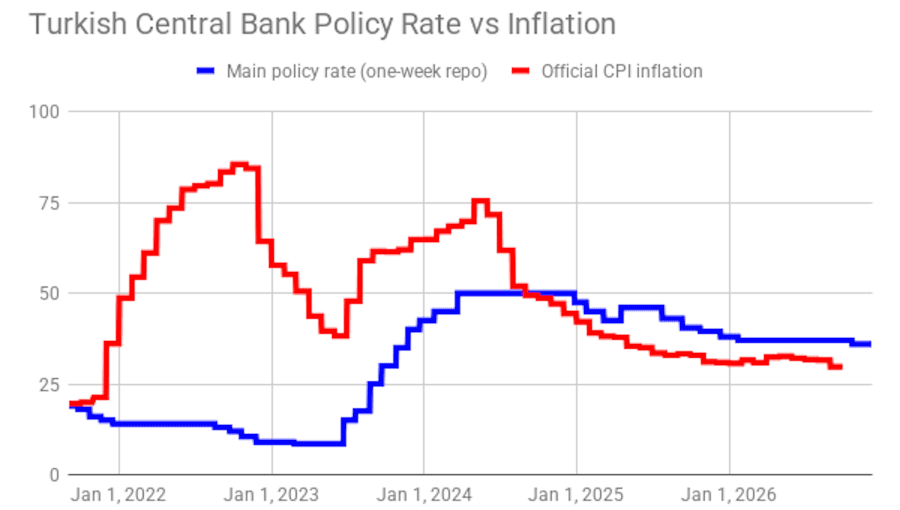
Turkey has entered a new monetary easing cycle. The monetary policy committee (MPC) of the Turkish central bank on October 22 cut its main policy rate (one-week repo) by 100 basis points to 36% in parallel with the expectation shown by the market consensus.
The so-called interest rate corridor was kept asymmetric as the overnight lending and borrowing rates were cut by 100 bp to 39% and 34.5%, respectively.
From time to time, the authority scraps its one-week repo auctions to instead direct lenders to the overnight window. That provides for temporary tightening within the “corridor”.
On August 23, the central bank resumed the one-week repo auctions. As a result, the national lender's weighted average cost of funding and market rates (TLREF) eventually approached the one-week repo rate of 37%. They will approach 36% in the coming days.
On September 10, the MPC held the policy rate for a fifth consecutive meeting in line with expectations.
Further 100-bp cut expected on Dec 10
On December 10, the MPC's last rate-setting meeting of 2026 will take place. The market consensus suggests another 100-bp cut.
On August 13, the central bank raised its end-2026 official inflation "forecast" to 28% in its latest quarterly inflation report. On September 6, the end-2026 official inflation target was hiked to 28.4% in the government’s latest medium-term programme (OVP).
On October 5, Turkey’s statistical institute (TUIK, or TurkStat) said that official annual inflation fell below the 30%-level in September to stand at 29.73%.
On November 12, the central bank will publish its next quarterly inflation report, the fourth and last of 2026. It will include updated forecasts.
On November 3, TUIK will release official October inflation. The September release signalled that the government is determined to release the end-2026 inflation at below the 30%-level.