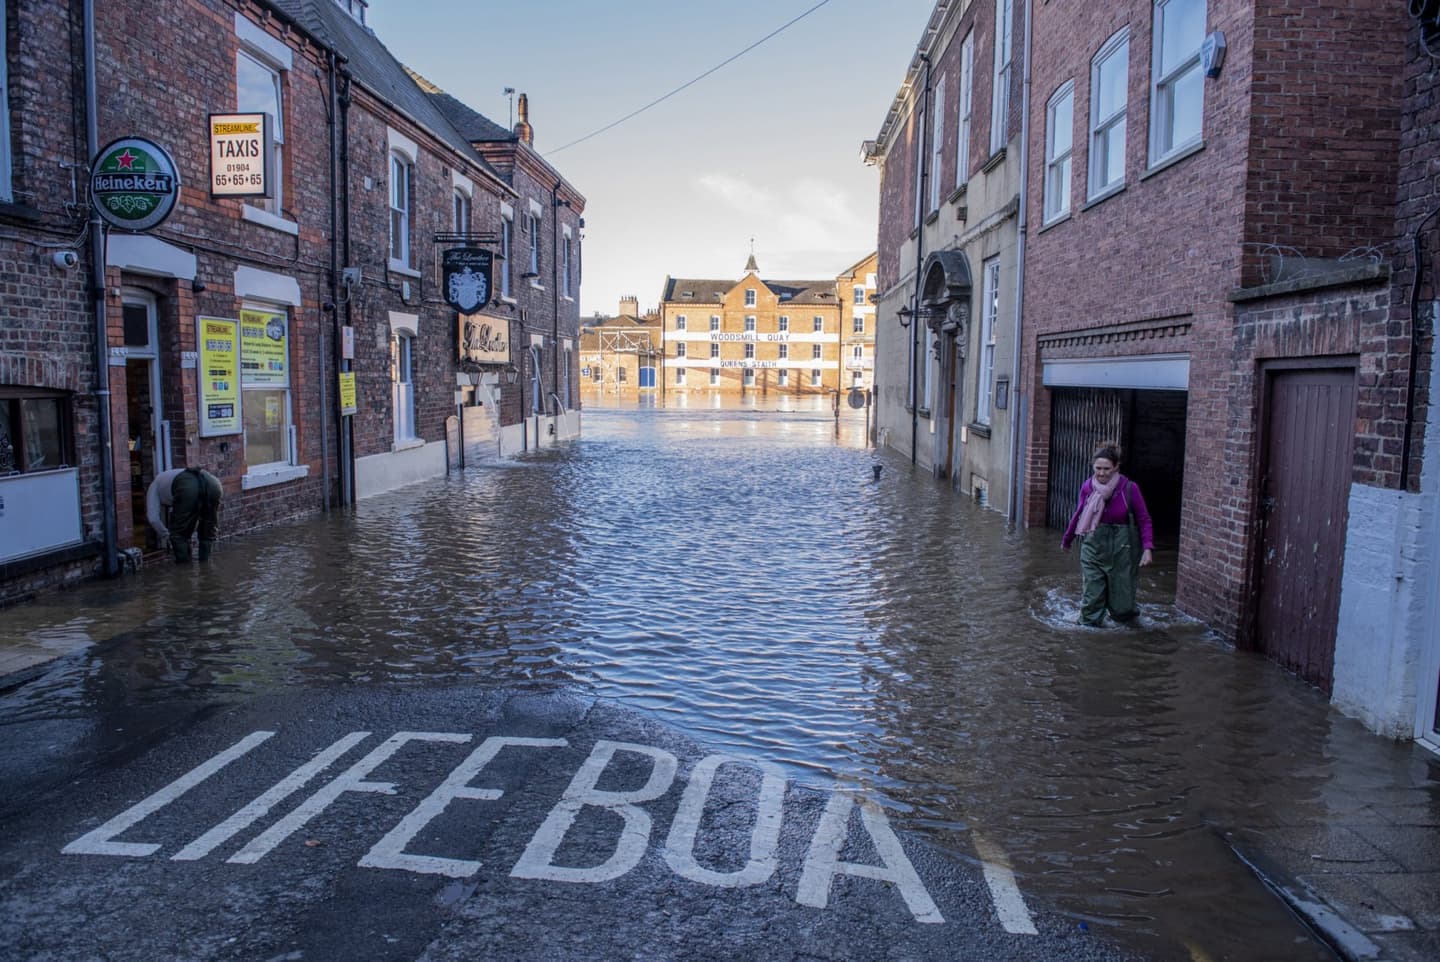
Hundreds of thousands of homes in areas including Skegness, Thurrock and Merseyside are likely to become uninsurable over the next 25 years due to climate change.
Senior industry insiders have warned the Government that insurers are increasingly withdrawing offers on properties due to the risks of flooding and other extreme weather, it has been reported this week.
If this continues, it could trigger a property crash on the scale of 2008, warned the anonymous group, which is being supported by the whistleblowing organisation Inside Track.
According to the insiders, current industry modelling shows coastal erosion, flooding and wildfires will cause “catastrophic damage” to properties in the coming years.
Which parts of the UK are most at risk?
Around 430,000 UK homes could become unmortgageable by 2050 due to the challenges in obtaining insurance for flooding, research published earlier this year by the UK Sustainable Investment and Finance Association (UKSIF) and Public First has found.
Owners of these homes, dubbed “climate mortgage prisoners”, could face paying £4,000 more per year on their mortgages.
This is because they would not be able to renew fixed-term deals and become “trapped” on more expensive standard variable rate (SVR) mortgages.
Those in the highest risk areas could see house prices drop by “over 20 per cent” and face costs of up to £45,000 to make their homes liveable after climate change damage.
Boston and Skegness was identified as the constituency with the most homes at risk of becoming unmortgageable (8,649), followed by Thurrock in Essex (7,663) and Goole and Pocklington in Yorkshire (6,873).
Merseyside was identified as another hotspot, with the constituencies of Bootle and Sefton Central also containing a high number of properties that could become uninsurable.
While many of the high-risk areas are coastal communities, this is not always the case.
A number of London boroughs, including Barking and Croydon, also have a high number of properties at risk.
London is particularly vulnerable to surface water flooding, which happens when heavy rainfall overwhelms the drain and sewer network, leaving it to collect in the street and flood properties.
“Flooding risks trapping hundreds of thousands of households in high-rate mortgages for uninsurable homes that they can’t easily sell,” said UKSIF CEO James Alexander.
“This could strain lenders’ balance sheets, with knock-on effects felt across the housing market and potentially the wider financial system.”
‘We’re critically unprepared’
The Committee on Climate Change (CCC), which advises the UK Government on climate risks, warned in May that this issue is being compounded by the closure of Flood Re.
The joint Government and industry scheme aims to keep insurance affordable in high-risk areas, but will end in 2039.
The CCC said this is “already creating uncertainty in the property insurance market”.
At the same time, the Labour Government has relaxed planning rules to make it easier to build on floodplains under its drive to build 1.5 million new homes within this parliament.
Homes are now being built that could become uninsurable in the future due to flooding, the boss of insurance firm Aviva, Amanda Blanc, has warned.
“The nation is just critically unprepared,” Hugh Ellis, Director of Policy at the Town and Country Planning Institute, told The i Paper.
“People are going to walk away from places [that then] become poverty-ridden and very risky. The most vulnerable in society end up living in the most dangerous places and that is not an outcome any Government should be happy to have.”

The Met Office has said that the UK faces an increased risk of flooding this Autumn and Winter.
This is in part due to the El Niño climate phenomenon, a periodic warming in ocean temperatures in the tropical eastern Pacific that affects weather patterns across the globe.
Around eight million homes – one in every four in England – could be at risk of flooding by 2050, the Environment Agency has warned.
A Government spokesperson said: “Climate change poses real long-term challenges for households, insurers and financial markets and we are working across government, with regulators and the insurance industry to understand these risks.
“We are already facing the issue head-on by strengthening flood insurance support, making flood cover more affordable for vulnerable households and investing in long-term flood resilience and adaptation planning.”
The 22 areas with thousands of at-risk homes
Boston and Skegness: 8,649 homes with mortgages that have a high flood risk in 2050
Thurrock: 7,663
Goole and Pocklington: 6,873
South Basildon and East Thurrock: 5,077
Bootle: 4,224
Sefton Central: 4,162
Louth and Horncastle: 4,087
Southport: 3,593
Hastings and Rye: 3,264
Rayleigh and Wickford: 3,234
Barking: 3,107
Harlow: 3,029
Basildon and Billericay: 2,697
Runnymede and Weybridge: 2,622
Bristol South: 2,588
Wycombe: 2,569
Castle Point: 2,568
Croydon South: 2,285
Doncaster East and the Isle of Axholme: 2,276
West Suffolk: 2,274
Selby: 2,176
Kingston upon Hull West and Haltemprice: 2,076