SK hynix (000660.KS) rebounded more than 4% after halting its review of a U.S. listing for Solidigm, shifting market attention to third-quarter earnings due on the 28th and to further shareholder return measures. Investors are watching whether a payout pool estimated at more than 30 trillion won ($20.9 billion) can drive a rebound in chip stocks and the broader KOSPI.
SK hynix closed 4.4% higher the previous day, according to the Korea Exchange on the 24th. The stock opened lower in the wake of a slide in U.S. chip shares, but sentiment improved after the company announced before the open that it had suspended its review of a pre-IPO funding round and an initial public offering for Solidigm. Samsung Electronics (005930.KS) rose just 0.5%.
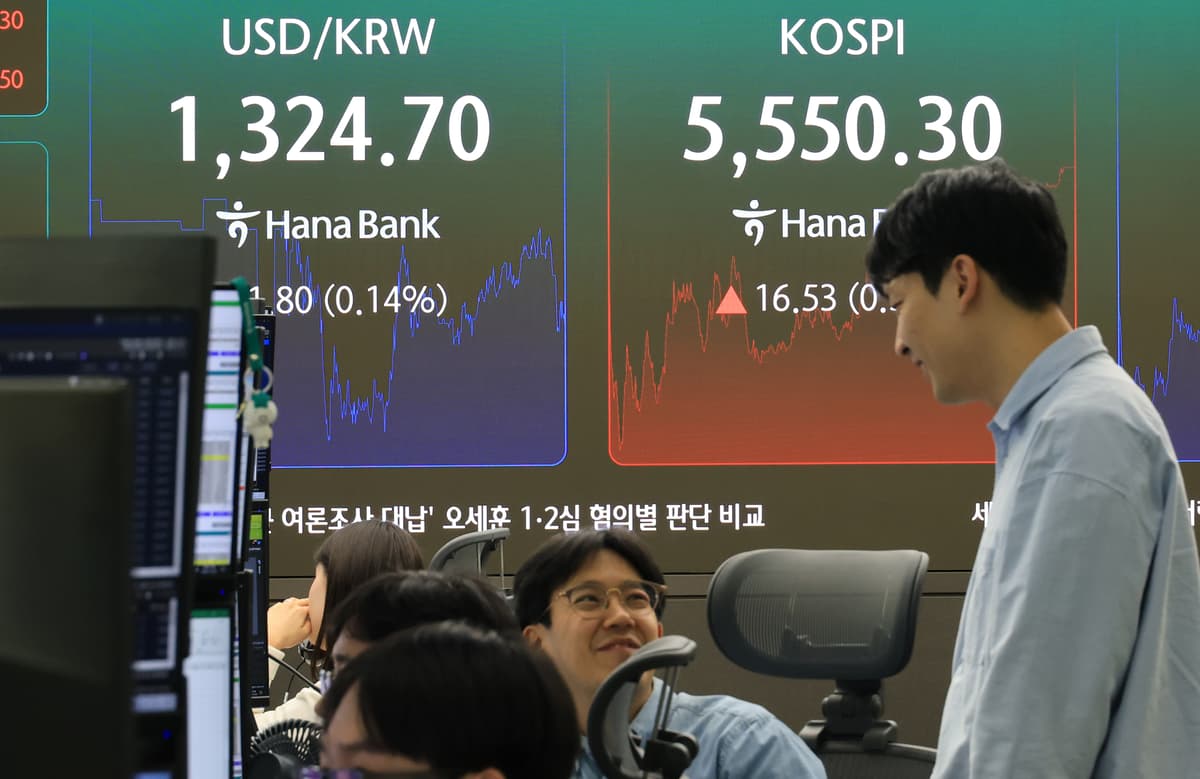
The KOSPI fell as much as 4.1% in early trading to around 5,306 before closing 0.3% higher at about 5,550, supported by SK hynix's rebound and institutional buying. Lee Jae-won, an analyst at Yuanta Securities Korea, said easing concerns over the erosion of shareholder value from a dual listing, along with bargain hunting by institutions, drove the recovery in both the stock and the index.
The planned Solidigm listing had weighed on SK hynix shares, drawing concerns about a valuation discount and equity dilution as well as objections from politicians and financial regulators. From Bloomberg's report on the listing plan on the 7th to the opening price on the 23rd, SK hynix fell 30.35%, a steeper decline than Samsung Electronics' 23.28% drop. Investor pushback grew, and the company said it had suspended the review after reconsidering whether the plan served existing shareholders, while adding that its view of Solidigm's growth potential and investment needs remained unchanged.
Analysts are focusing on the possibility that the decision leads to stronger shareholder returns. Kim Sun-woo, an analyst at Meritz Securities, said the move signals that enhancing shareholder value is the company's top priority. "There is a high likelihood that enhanced shareholder return measures exceeding earlier expectations will be presented at this earnings briefing," he said.
The key questions are size and method. SK hynix has pledged to return more than 50% of its cumulative free cash flow from 2025 through 2027 to shareholders. A 40 trillion won buyback announced in August was completed on the 21st, ahead of the originally scheduled date of Nov. 19. With that program finished and the resulting gap in buying demand, specific follow-up plans have taken on greater importance.
Kim Rok-ho, an analyst at Hana Securities, said at least 30 trillion won in additional funding for shareholder returns is expected based on free cash flow, and that share buybacks and cancellations are more likely to be used than dividends. Investors are watching whether the plan will include large-scale buybacks and cancellations that directly absorb shares in circulation.
The basis for additional returns is earnings expected to reach a record high. Consolidated third-quarter consensus estimates for SK hynix stand at 98.2257 trillion won in revenue and 76.964 trillion won in operating profit, according to FnGuide, up 301.76% and 576.11% respectively from a year earlier. The company plans to disclose additional shareholder return measures alongside its earnings release on the 28th.
Samsung Electronics will report final earnings and division-by-division results the following day, on the 29th. Its preliminary third-quarter figures, released earlier, showed revenue of 195 trillion won and operating profit of 107.4 trillion won. Earnings outlooks and cash deployment plans at both companies are expected to shape investor sentiment across chip stocks.
The share-price correction has also eased valuation pressure. Kim Sun-woo said SK hynix's projected 2027 price-to-book ratio stood at 1.10 times based on the closing price on the 22nd, near a historic low, and that shareholder returns backed by cash generation would provide a trigger for a rebound.
A sustained rebound, however, requires improved buying by foreign investors. Lee said that because the rebound was led by institutions, it remains to be seen whether foreign selling continues. Yang Hyun-kyung, an analyst at iM Securities, said the withdrawal of the listing eases concerns about a dual listing but added, "We also need to consider that opportunities to raise external capital will shrink and that the burden of future investment funding could grow."
