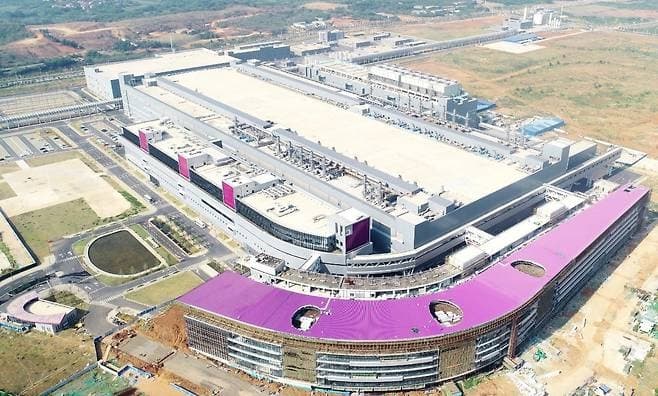
Chinese chipmakers are closing the gap faster, funded by the same artificial-intelligence memory boom that has lifted their Korean rivals. While Samsung Electronics (005930.KS) and SK hynix (000660.KS) concentrate on high-margin products such as high-bandwidth memory, Chinese producers are pouring the cash earned from rising commodity memory prices into new plants and technology development. The shift is not yet strong enough to unseat Korean leadership, but competition could intensify markedly once China's new fabs reach full operation in 2027 and 2028, industry watchers said.
ChangXin Memory Technologies, a Chinese DRAM maker, and Yangtze Memory Technologies, a NAND flash producer, are expanding capacity while moving into each other's main business lines, according to industry sources on the 23rd. CXMT is pursuing NAND research and development, and YMTC has begun work on DRAM. The moves suggest both companies, which built their businesses on commodity products, are aiming to become full-line memory suppliers.
Growth has been rapid. Based on preliminary nine-month guidance CXMT released on the 16th, third-quarter revenue works out to between 114.7 billion and 119.7 billion yuan (roughly 23 trillion to 24 trillion won), about seven times the figure a year earlier. Analysts attribute the jump to a DRAM supply shortage and price increases driven by expanding AI server investment. CXMT held a 10% share of global DRAM revenue in the second quarter, up 6 percentage points from 4% a year earlier, according to Counterpoint Research. YMTC has risen to third place globally in NAND shipment share and is targeting a 20% share over the long term.
The key question is how quickly the windfall translates into added capacity and stronger technology. Semiconductor research firm SemiAnalysis projects CXMT's monthly DRAM wafer capacity will grow from about 350,000 wafers at the end of this year to 420,000 by the end of 2027 and 500,000 by the end of 2028. On that trajectory, the company would account for roughly 17% of global DRAM capacity in 2027. That measure reflects installed equipment, however, and differs from actual shipment share. SemiAnalysis estimates CXMT's 2027 shipments at about 12% of the market on a data-capacity basis.
A rising market share does not by itself mean the technology gap is narrowing. CXMT's DDR5 products are reported to carry manufacturing costs per unit of data capacity more than 30% higher than those of Korean and U.S. producers. Still, if the company channels its improved earnings into further process upgrades, that cost gap could gradually shrink. CXMT's stock market listing in July, which raised a large sum, also adds to its investment capacity.

YMTC is likewise spending heavily on research and development. Its R&D staff numbers 4,796, more than 30% of total employees. The company has invested 14.2 billion yuan in R&D over the past three years and holds 5,611 registered invention patents. It is using Xtacking, its proprietary wafer bonding technology, to work around U.S. export controls on advanced chipmaking equipment. Samsung Electronics is reported to have signed a related patent licensing agreement with YMTC last year. YMTC is also seeking additional funding for capacity expansion and new technology development.
Chinese producers are no longer confining their push to commodity products. CXMT is preparing to unveil server DRAM built on a 4F² cell structure, which shrinks the area of each memory cell. YMTC is piloting mobile DRAM running at 7,500 megatransfers per second while developing a next-generation 9,600 MT/s product. One megatransfer equals one million data transfers, meaning 9,600 MT/s allows 9.6 billion transfers each second. YMTC is also moving into the enterprise solid-state drive market. Yields and commercialization timelines for the new products remain uncertain.
China's domestic market is another variable. Capital spending by the country's AI and cloud companies is rising, lifting domestic memory demand along with it. That gives Chinese producers a base on which to scale production and accumulate mass-manufacturing experience. Installing new equipment, stabilizing yields and winning customer qualification all take time, however. Tighter U.S. export controls on equipment could also delay investment plans.
Whether the threat to Korean companies materializes depends on when China's capacity additions take full effect, analysts said. Some point to 2028 as the turning point. If large volumes of new Chinese output hit the market just as growth in AI investment slows, it could put downward pressure on commodity memory prices.


Gap World digs into the gaps in the flood of news from the age of technological rivalry. Follow the column and the reporter's page for analysis and outlook on cutting-edge technology and semiconductor issues.
Questions and tips are always welcome. Reach the reporter by email, and follow-up reporting will be reflected in the next installment.
