The following is a translation of an article written by Réka Zsuzsánna Máthé, a research fellow at the Europe Strategy Institute of the University of Public Service, originally published on the Five Minutes Europe blog of Ludovika.hu.
France and Italy’s margins are rising, and they aren’t the only ones paying the price…
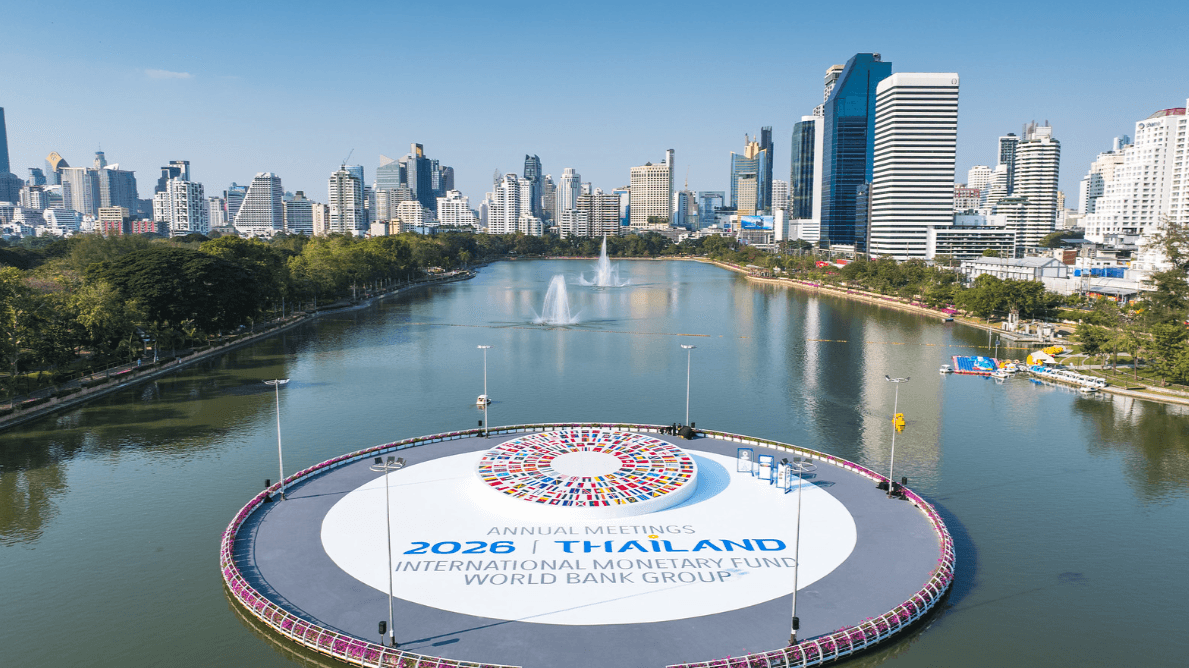
On Monday, 12 October, the 2026 Annual Meetings of the International Monetary Fund (IMF) and the World Bank Group (WBG) began in Bangkok, Thailand. The meetings last all week, and the guest list is impressive, though its length alone does little to help one navigate it. After all, titles don’t carry weight; who makes substantive decisions and who represents issues on the agenda this week do. From this perspective, five names are worth highlighting.
Ajay Banga, President of the World Bank Group, is hosting this week’s meeting and effectively setting the agenda: much depends on how much the debate over expanding the bank’s mandate aligns with his institutional clout. Managing Director Kristalina Georgieva represents the International Monetary Fund, and issues surrounding debt invariably come back to her. The mere mention of Tharman Shanmugaratnam’s name is noteworthy in itself: just a few years ago, he was finance minister and one of the most active shapers of the international financial system; today, he is head of state. In other words, he has both an insider’s knowledge of major institutions and represents a sovereign nation. Ed Miliband serves as the British governor of the World Bank; as foreign secretary, he committed himself to advocating for climate goals on the international stage, so he speaks from a government perspective. Last but not least—and by no means an exhaustive list—is Makhtar Diop, head of the International Finance Corporation, who has extensive experience in mobilizing private capital.
This year’s event (as well as announcements following similar events in previous years) frequently mentions ‘expanding lending capacity’, and prominent individuals play a key role in this process. However, the World Bank does not issue money; it can lend more by tightening its balance sheet—that is, holding fewer reserves for the same level of risk—or by bringing in other investors willing to share the risk. This is how the 2024 ‘Bigger and Better Bank’ programme raised $150 billion over ten years.
In addition to expanding lending capacity, similar events have also yielded results such as the recapitalization of the Poverty Reduction and Growth Trust (PRGT), which was approved at the 2023 Marrakesh meeting. At that time, the Hungarian National Bank also committed a historically significant contribution of 11 million SDRs to support the fund. Similarly, in 2024, significant progress was made in renewing the International Development Association (IDA), which provides interest-free or highly concessional loans to the poorest countries. Finally, it is worth mentioning the role these organizations play in managing the debt crisis. Because many African and developing countries have fallen into a debt trap due to high interest rates, multilateral debt-rescheduling frameworks (the Common Framework) have repeatedly been refined to prevent defaults.
However, this is not just a problem for the developing world: the same debt dynamics are evident in Europe as well, albeit in a different form, and this is what makes the EU’s situation this week a mixed one. A substantive realignment of voting weights has been delayed for years, while pressure from emerging economies remains constant. Aid to lower-income countries, however, is a double-edged sword: in Kenya’s case, for example, tightening IMF rules led to tax hikes, which sparked massive street protests that caused fatalities.
Critics argue that refusing to forgive debts and the ongoing fine-tuning of the so-called Common Framework (a multilateral debt management consultation framework) amount to nothing more than a superficial solution, one that could keep poorer nations mired in debt for decades. The accusation that these institutions serve Western interests rather than fostering a genuine global consensus is uncomfortable but not unfounded. Countries with larger contributions receive loans on more favourable terms; freezing the voting ratios preserves this long-standing imbalance.
‘This is not just a problem for the developing world: the same debt dynamics are evident in Europe as well’
All of this places a double burden on the EU. The EU is not a single entity in this forum: the Commission, the European Central Bank, and the member states often have differing priorities, and the most important decisions are consistently made behind closed doors while the joint final statement is being drafted. However, IMF Managing Director Kristalina Georgieva’s opening remarks reveal what unites all EU actors. She highlighted the situation of indebted eurozone countries, as their spreads relative to German government bonds (the extra interest investors demand for holding French or Italian bonds instead of German ones) are steadily rising. This is true not only for France and Italy, but also, to a lesser extent, for Ireland and Portugal—even though they have put their budgets in order since the crisis. From Georgieva’s remarks, we can conclude that the market is apparently not pricing in individual countries’ mistakes, but rather the debt trajectory of the entire eurozone: thus, even disciplined member states are not protected by their own discipline when it comes to the common currency.
In other words, the diagnosis is clear; the question is what the EU can do about it with the tools at its disposal. The EU can use its fiscal and regulatory clout to reshape the agenda. The debate over private capital’s involvement appears technical—it concerns risk-sharing and local-currency financing—but what’s really at stake is how much public funding will generate profits for private investors.
If the EU could enforce clear rules here regarding who bears the risk and who reaps the returns, it would also safeguard its development policy. Climate finance and digital regulation are similarly key areas: the EU’s digital regulatory framework is the most sophisticated internationally, so the question is how it can extend its standards globally, or to what extent it will remain isolated in this regard. However, as a lack of credibility with vulnerable countries persists, the week in Bangkok will undoubtedly serve as a reminder of this to the European delegations.
Related articles:
Click here to read the original article.
The post The Annual Meeting of the IMF and World Bank: What Might It Mean for the EU? appeared first on Hungarian Conservative.