
Visualization created with AI assistance based on original reporting.
- Key insight: Advisors may underestimate the compounding expenses of in-home care, treating elder care as a peripheral issue rather than a primary driver of retirement solvency.
- Expert quote: "Long-term care is not a side conversation in retirement planning." — John Roberts, Northwestern Mutual
- Supporting data: Eight hours of daily in-home care is projected to cost $105,120 out of pocket in 2026 and rise to $552,232 by 2060.
The vast majority of older adults want to age in their own homes, according to new research. But financial advisors may not be planning for the potentially steep costs of making that possible.
Processing Content
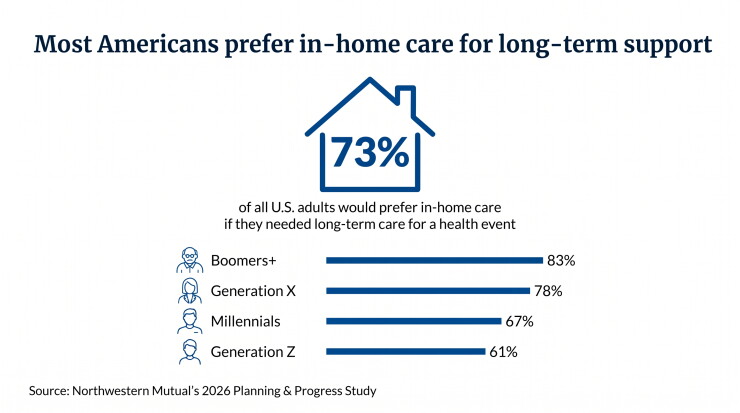
A Northwestern Mutual study found that 83% of baby boomers and members of the Silent Generation would prefer to stay home rather than receive care in assisted living, a nursing home or a medical facility. Yet the costs involved in doing that can be substantial, and some advisors may not understand just how expensive it can be.
In 2026, the projected out-of-pocket cost for a home health aide who provides eight hours of daily care is $105,120, according to Northwestern Mutual's analysis. By 2056, that figure could spike to $454,323, and by 2060, it would reach $552,232.
Those are sizable amounts of money that could shake up retirement planning and estate planning.
"Long-term care is not a side conversation in retirement planning," John Roberts, chief field officer at Northwestern Mutual, said in a statement. "It can be one of the largest and most personal expenses a family faces, impacting where people can age gracefully and how much of a legacy they can leave behind to others."
Because of this, planning ahead is critical. "A financial advisor can provide immense value — helping clients understand the numbers and the solutions available to them," he said.
Advisors may underestimate key care costs
Aging in place at home can mean 24/7 care, said Annalee Kruger, founder and CEO of Care Right, an aging-plan consultancy that collaborates with financial advisors on shared clients. Individuals can be bed-bound, incontinent or need to be fed. And the investments needed to make aging in place a reality — in-home nurses, wheelchair accessible ramps, remodeled bathtubs, for example — can add up quickly.
"I've noticed consistently with advisors [that] they truly don't understand the actual cost of care, and they also don't always understand how expensive it is to age in place at home," said Kruger. "So the more that advisors can really understand about the needs of their aging clients, the more that they can help intervene and safeguard."
After receiving feedback from advisors who said they weren't prepared to help clients with elder care issues, Kruger created a certificate program to equip interested advisors with the specialized skills to serve clients age 85 and older.
Overall, 73% of U.S. adults would prefer in-home care, according to results released Oct. 5 from the Northwestern Mutual study. The study, conducted by The Harris Poll, included 4,375 U.S. adults. Older generations were more likely to prefer in-home care, including 61% of Generation Z, 67% of millennials and 78% of Generation X.
Caregiving costs can affect the whole family
The financial implications of planning for in-home care can extend beyond the person receiving care. About two-thirds of millennials and Generation Z anticipate providing long-term care for a loved one, according to the study.
Northwestern Mutual found that the most common activity caregivers have taken to address the financial effects of caregiving is decreasing spending (32%). The next most common responses were using personal savings or emergency funds (25%) and working longer hours or taking a second job (21%).
Less commonly, caregivers reported taking on credit card debt, putting off paying down debt, asking family or friends for support, reallocating retirement funds or taking out a second mortgage, according to the study.
"Caregiving is one of the most meaningful ways people support the ones they love, but no one should have to sacrifice their own financial security to provide it," Roberts said in a statement.
Advisors might not think of planning around caregiving as something they can help with, but it can provide value to clients. As a resource for advisors, Denver-based aging-care platform bQuest built a network of vetted service providers.
As their health evolves, clients might gradually lose their ability to make decisions for themselves, yet they might not realize it. Planning ahead can help prevent clients and their families from being blindsided. Advisors can also help clients think through who will provide care, where that care will take place and how it will be paid for.
Introductory bullet points created by AI with editorial review.

Reporter
Zoe Sagalow covers tax and retirement issues for Financial Planning, bringing a decade of experience in financial policy and regulatory reporting to... Read full bio