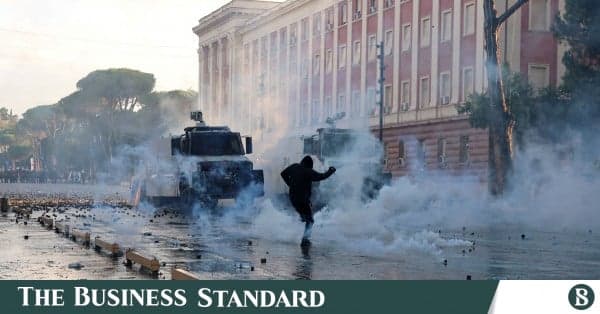
On Saturday, 17 October, Paris looked like 2018 again: kiosks burned at Place de la République, riot police turned water cannons on the crowds, and the Yellow Vests, the populist movement that began as a revolt against a fuel tax, were back on French streets.
Far to the south, in Puglia, truckers and olive farmers had already spent a week sleeping in tents at motorway toll booths, while shoppers in San Severo were walking past empty supermarket shelves. In Sicily, truckers who keep most of the island's supermarkets stocked, parked their trucks and refused to move.
It is tempting to read these as separate national dramas: French students angry about crumbling schools, Italian truckers angry about diesel, and Spanish families angry about the price of everything. They are not.
Europe is burning because three things have arrived at once: an oil shock the continent did not cause, governments that no longer have the money to cushion it, and a generation that had already concluded that the system was not built for them.
How diesel prices lit the fuse
The immediate cause is the war with Iran, which broke out at the end of February and has disrupted energy flows through the Strait of Hormuz ever since.
A ceasefire in June allowed crude oil prices to ease temporarily, but fresh attacks on Gulf energy infrastructure pushed them back up in late summer, and EU pump prices hit record highs in September. By the week of 12 October, the European Union's average prices stood at €2.01 per litre for petrol and €2.14 per litre for diesel, according to the European Commission's weekly oil bulletin. These were roughly 24% and nearly 40% higher, respectively, than a year earlier.
Diesel is the number that matters because it is what moves Europe's food. More than 80% of Italy's goods travel by road, and Sicilian truckers say fuel now accounts for 35% to 40% of their operating costs, wiping out their margins entirely. Meanwhile, compensation promised by the government in May has yet to arrive.
When the cost of moving a crate of oranges jumps, the burden falls first on the trucker, then on the farmer, and finally on the shopper. Eurozone inflation rose to 3.8% in September, its highest level in three years, with energy prices up almost 19% year on year.
Inadequate funds to cushion the blow
In 2022, when Russia's invasion of Ukraine sent energy prices soaring, European governments reached for their chequebooks. They spent more than €500 billion on price caps, fuel discounts and household transfers. Although there were strikes, the social contract held. This time, the chequebook is nearly empty: debt is higher, interest bills are steeper, and pressure from Brussels and the bond markets is to shrink deficits, not widen them.
France shows what that means on the ground. A government trying to rein in one of the eurozone's largest deficits has squeezed public services, and the cuts are landing exactly where ordinary people can see them.
The current wave began in September at a single high school outside Paris and spread across the country, as students and teachers blockaded hundreds of schools over classes of 36, broken toilets, teacher shortages and buildings that turn into ovens in the heat.
The placard that captured the mood read simply: "Tax the rich, not our future." Spain, Austria, Poland and Germany have offered temporary fuel tax cuts, but these are limited in duration and scope, and appear insufficient to offset a 40% jump in diesel prices.
The inflation trap
There is a cruel twist. Faced with rising prices, the European Central Bank has done what central banks are built to do: it raised interest rates in June and again on 10 September, taking its deposit rate to 2.5%, even though the eurozone is expected to grow by only 0.8% this year.
Higher rates cannot conjure oil out of the Strait of Hormuz. What they can do is make mortgages, business loans and government borrowing more expensive at the very moment households are paying more for fuel and food.
This is the classic stagflation bind, and it helps explain why the anger is directed at European capitals rather than at Tehran or Washington. People understand that a distant war started the fire, but they can also see that their own leaders are deciding who pays for it. So far, the answer appears to be them.
A generation locked out
The oil shock is the spark, but the kindling was already stacked. Youth unemployment rose between 2023 and 2025 in eight of the world's 11 regions, according to the International Labour Organization (ILO), with some of the sharpest increases in Northern, Southern and Western Europe. Young Europeans face rents they cannot afford, entry-level jobs that are harder to find, and pension systems they expect to fund but may never fully benefit from.
Then there is artificial intelligence. It is fashionable to claim that AI-related job losses are driving this unrest, and the fear is real: in one survey, more than a quarter of 18-to-34-year-olds said they or someone they knew had lost a job to AI.
The hard data is more modest. Stanford researchers have found that unemployment among the workers most exposed to AI has risen by less than one percentage point since 2022, while the ILO estimates that about 6% of jobs held by people under 30 fall within the most exposed occupations.
AI is not yet emptying offices. What it is doing is darkening expectations: young people believe the ladder is being pulled up behind them, and that belief makes today's price shock feel like a verdict on their future rather than a passing storm.
Add to this the contagion of the Gen Z protest wave, which began with Bangladesh's student uprising in 2024 and has since toppled or shaken governments from Nepal to Madagascar. Young Europeans have watched on their phones as leaderless movements forced concessions elsewhere, and the French students who chanted that "2026 is the new 1789" were drawing on more than their own history.
What comes next
Europe's fever will track the price of diesel. ECB experts say pump prices will fall only when three things happen together: the fighting stops, flows through the Strait of Hormuz return to normal, and global refining capacity recovers.
None of these developments is within Europe's control. In the meantime, the calendar is crowded: Italian truckers are due to meet ministers on 27 October, Italian fishermen have called a national strike for 22 October, French unions have further action planned, and winter heating bills are still to come. Expect the protests to ebb and flow with fuel prices, and populists on both the left and the right to capitalise on the anger.
Three lessons for leaders everywhere
For leaders everywhere, especially in economies that import energy, Europe offers three lessons.
The first is that an energy shock is never merely an economic event: it is a test of whether the state can share the pain fairly. Europe, for all its wealth and welfare systems, is struggling with that test in public. Governments with tighter budgets should assume the test will be harder for them, not easier.
The second is that the people who move goods are a pressure point. Truckers, farmers and fishermen operate on thin margins and can bring a country to a standstill within days. Support targeted at them and delivered on time offers greater stability than broad subsidies that disproportionately benefit those who need them least. Italy's truckers did not block roads simply because diesel was expensive; they blocked them because the assistance promised in May had still not arrived by October.
The third is that young people are watching to see whether anyone has a plan for their future. AI may not yet be destroying jobs on a large scale, but the fear that it will is already shaping how a generation interprets every price shock.
Leaders who invest visibly in skills, apprenticeships and entry-level hiring, and speak honestly about how AI will change work, will find their citizens far more patient when the next shock arrives. The time to build those buffers is before the shelves are empty, not after.
Dr Sajid Amit is an experienced development sector professional, academic and investments professional. He has received awards for his investment research from Morgan Stanley and BlackRock. He can be reached at [email protected].
Disclaimer: The views and opinions expressed in this article are those of the author and do not necessarily reflect the views and opinions of The Business Standard.