BIDS study says they spend over 40% of income on loan instalments
Published : 13 October 2026
•
Updated : 13 October 2026, 03:27
Staff Correspondent

Debt burdens among rural households, particularly the poorest, are growing heavier.
According to a study unveiled yesterday, 79 percent of the poorest families spend over 40 percent of their income repaying instalments on loans from microfinance institutions and local mohajons, or informal lenders.
The study by the Bangladesh Institute of Development Studies (BIDS) finds that 49 percent of the poorest people spent more than 40 percent of their income on loan instalments in 2010.
Overall, the share of borrowers who pay over 40 percent of their income in instalments increased from 22 percent in 2010 to 41 percent now, said BIDS Research Director Kazi Iqbal while presenting his research findings at a workshop at BIDS.
The research is titled “The Structural Transformation of Bangladesh’s Rural Credit Market Since 2000: Evidence from Nationally Representative Surveys.”
BIDS and the International Food Policy Research Institute (IFPRI) organised the event, where findings from other studies, were also presented.
“It means increased indebtedness for the poor and running into a cycle of debt,” Iqbal said.
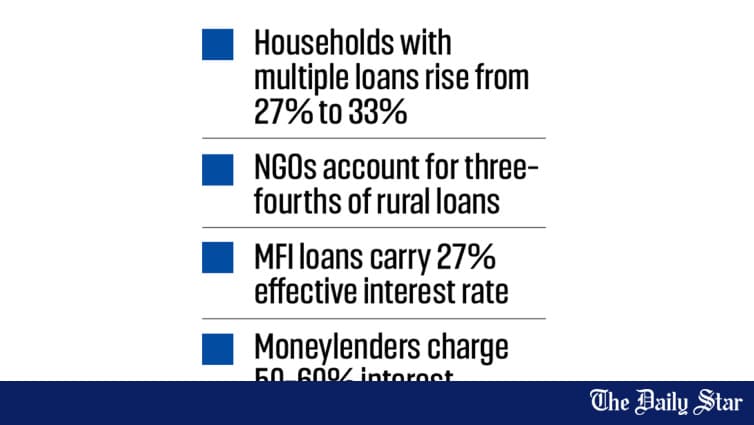
The research finds that the share of households with two or more loans increased from 27 percent to 33 percent since 2010. It did not examine the reasons behind the growing debt burden.
According to the report, NGO microfinance institutions (MFIs) now account for three out of every four rural loans, making them the dominant source of credit in rural areas.
However, wider access to loans has coincided with a growing repayment burden, particularly among poorer households.
Despite an increase in the number of lenders, interest rates have remained largely unchanged over the past decade.
The effective interest rate on loans provided by MFIs stands at 27 percent, while banks charge around 10 percent interest and MFIs charge a flat rate of 15 percent. Moneylenders charge between 50 and 60 percent.
The BIDS research director said competition could not bring down the effective interest rates charged by MFIs.
“This is because there is a huge demand for credit at the current high rates,” he said, adding that a push from the regulator, the Microcredit Regulatory Authority (MRA), was needed to cut borrowing costs.
Large and national-level NGOs are also better positioned to cut interest rates, he said.
The BIDS study also finds that agriculture’s share of total rural borrowing fell from 25 percent to 16 percent, reflecting broader structural changes in the economy.
Agricultural loans are mainly used to buy fertiliser, seeds, and livestock and to meet cash expenses for land leasing, rather than to purchase agricultural machinery.
Farmers who rent land through cash payments and those who cultivate under sharecropping arrangements borrow the most. Access to bank loans, however, depends on land ownership.
Another study by IFPRI, presented at the workshop, finds that banks finance only 2-7 percent of machinery purchases.
Among combine harvester owners, just 5 percent used bank loans to buy their machines. Around 32 percent borrowed money from relatives, 27 percent from microfinance institutions or NGOs, and 8 percent from moneylenders.
The study says dealers remain the main source of machinery financing, covering an average of 57 percent of a combine harvester’s net price, usually with repayment over 18 months. A signed blank cheque is often taken as security.
It says the costs of repairing machinery create further financial pressure. Over one-third of combine harvester owners borrow to cover repairs, mainly from relatives and moneylenders, and nearly half of those repair loans remain unpaid.
The report says about 64 percent of combine harvester owners’ income comes between April and June, leaving them facing cash shortages during the remaining nine months of the year.
The researchers recommend machinery-backed loans, seasonal repayment schedules, and hire-purchase financing with terms of at least three years.
They also call for changes to agricultural credit rules that exclude machinery services provided on other people’s land from recognised agricultural activity.
Another IFPRI study, conducted with WeGro, examined whether sharing business risks could encourage livestock investment.
Under the profit-sharing arrangement, WeGro financed cattle purchases and received one-third of the profit after sale, while farmers kept two-thirds. Farmers owed nothing to WeGro if there was no profit.
Agriculture Secretary Md Salim Khan, MRA Executive Vice-Chairman Prof Mohammed Helal Uddin, and Palli Karma-Sahayak Foundation Managing Director Md Fazlul Kader were present at the event, which was chaired by BIDS Director General Prof AK Enamul Haque.