

Jack comes to Simple Flying with a lifelong interest in all things aviation. He holds a degree in Aerospace Engineering from Georgia Tech, and is a certified private and remote pilot. Beyond these experiences, Jack previously worked for a corporate flight department where he gained first-hand experience in the world of business aviation. Currently, Jack works in the professional services industry and continues to build his flight hours outside of work.
Boeing expected the Boeing 737-900 to extend the appeal of its Next Generation narrowbody family by offering airlines a larger aircraft without abandoning the familiar 737 platform. The jet was the longest member of the family when it entered service with  Alaska Airlines in May 2001, but its extra fuselage length did not translate into the passenger capacity or range many airlines needed.
 Boeing had created a bigger aircraft without giving it a sufficiently bigger commercial advantage.
The result was a short production run of just 52 aircraft, compared with 505 examples of the improved Boeing 737-900ER. The original model’s shortcomings were not rooted in a single technical failure. Instead, a combination of cabin-evacuation limits, payload and range constraints, and strong competition from Airbus made it difficult to justify over the Boeing 737-800 or rival Airbus A321. Boeing’s subsequent redesign demonstrated that the market wanted a larger 737, but only if the added length came with meaningful operational benefits.
A Longer Aircraft Without A Larger Passenger Limit

Boeing authorized the 737-900 for production on September 10, 1997, after Alaska Airlines committed to launch the model. The new variant stretched the 737-800, reaching 138 feet, 2 inches (42.1 meters) in length and becoming the longest 737 Next Generation aircraft at the time. Boeing presented it as a way to give airlines more capacity while preserving the family’s commonality, which allowed crews and maintenance teams to work across related variants. The company’s launch announcement described a typical two-class configuration of up to 177 passengers.
The difficulty emerged at the upper end of the seating market. Boeing retained the same main-door and overwing exit arrangement used on the 737-800, limiting the -900 to a maximum of 189 passengers under its approved evacuation configuration. The fuselage could physically accommodate more seats, but a higher certified passenger count required sufficient emergency exits for an evacuation within regulatory limits. The longer cabin therefore did not raise the aircraft’s maximum capacity above that of the shorter -800. That ceiling mattered most to airlines built around high-density seating. A low-cost carrier could already configure a 737-800 with 189 seats, so replacing it with a longer -900 did not create an additional row or increase the maximum number of fare-paying passengers. The extra fuselage could offer cabin-layout flexibility, but it could not deliver the central financial benefit that typically motivates an airline to buy a larger aircraft: more seats over which to spread the costs of each flight.
Not every operator needed 189 seats, though, and Alaska initially used the aircraft in a lower-density configuration. The limitation was therefore not fatal for every route or business model. It did, however, narrow the pool of potential buyers and left Boeing’s stretched model poorly positioned for carriers seeking maximum capacity from a single-aisle jet.
A Longer Fuselage, But Limited Performance Changes
The second weakness was that Boeing increased the aircraft’s length without making equivalent changes to its fuel capacity or maximum takeoff weight. The standard 737-900 retained the -800’s basic limits in these areas, meaning the additional structure and potential payload consumed part of the available weight allowance without adding more fuel to compensate. When configured with more passengers or cargo, the aircraft could face a more restrictive range-payload trade-off than airlines expected from a larger model.
|
737 Next Generation Comparison |
||
|---|---|---|
|
737-800 |
737-900 |
|
|
Length |
129 feet, 6 inches (39.5 meters) |
138 feet, 2 inches (42.1 meters) |
|
Fuel capacity |
6,875 US gallons (26,022 liters) |
6,875 US gallons (26,022 liters) |
|
Maximum takeoff weight |
174,200 lb (79,010 kg) |
187,700 lb (85,130 kg) |
|
Range |
2,800 nautical miles (5,190 km) |
2,700 nautical miles (5,000 km) |
Range is not simply a fixed distance printed on a specification sheet. Actual capability depends on passenger and baggage loads, cargo, weather, reserves, airport conditions, and the route’s operational requirements. The -900 could serve many medium-haul routes effectively, but its longer fuselage did not automatically make it more capable on longer sectors. In some circumstances, an airline could carry the same passenger count as on a -800 while accepting a range penalty, weakening the value of the larger airframe. As a result, this constrained scheduling choices. A model with limited flexibility may require payload restrictions, an intermediate stop, or the assignment of another aircraft type to certain routes. Each workaround can complicate fleet planning and dilute the savings expected from commonality.
The -900’s range problem was particularly awkward because the aircraft’s extra length implied an upgrade. Airlines purchasing a larger narrowbody generally expect either more seats, more range, or a useful combination of the two. The original -900 delivered neither advantage at the level that would distinguish it from the -800. Its basic design retained much of the smaller model’s operating envelope while adding fuselage length, leaving customers with a compromise rather than a clear step forward.
The Airbus A321 Offered A Stronger Proposition

The 737-900 also entered a market in which Airbus already had a more convincing larger narrowbody: the A321. The A321 was designed as a stretched member of the Airbus A320 family and could carry more passengers than the standard -900 in typical configurations. Its greater capacity gave airlines another way to reduce the cost per seat on busy routes, especially when demand was strong enough to fill a larger cabin. Beyond the capacity advantage, its range and payload capabilities made it useful across a broader mix of routes, while its larger cabin helped carriers match capacity to high-demand markets. For airlines comparing aircraft on economics rather than family loyalty, the relevant question was not whether the -900 was longer than the -800. It was whether that length produced a competitive cost per passenger and enough operational flexibility to justify the purchase.
Boeing’s established 737 customer base remained an advantage when competing with Airbus. Airlines already operating a 737 fleet could benefit from common pilot training, maintenance practices, and fleet procedures. Such efficiencies can influence an aircraft decision because they affect costs beyond fuel burn, including crew scheduling, spare parts, and the complexity of daily operations. Yet commonality could not fully compensate for an aircraft that lacked the seating capacity or range needed for a carrier’s intended missions.
The A321 ultimately sold thousands of aircraft across its original generations, far exceeding the original 737-900’s 52 deliveries, and Airbus is now seeing strong demand with the A321neo series. Those totals cover aircraft produced over different periods and do not, by themselves, isolate every commercial factor behind the outcome. They nevertheless illustrate how much stronger demand proved for Airbus’s larger narrowbody offering. The 737-900 struggled to establish a distinct position between the capable 737-800 and an A321 that could offer more capacity and reach.
Only A Small Group Of Airlines Bought The Original Model
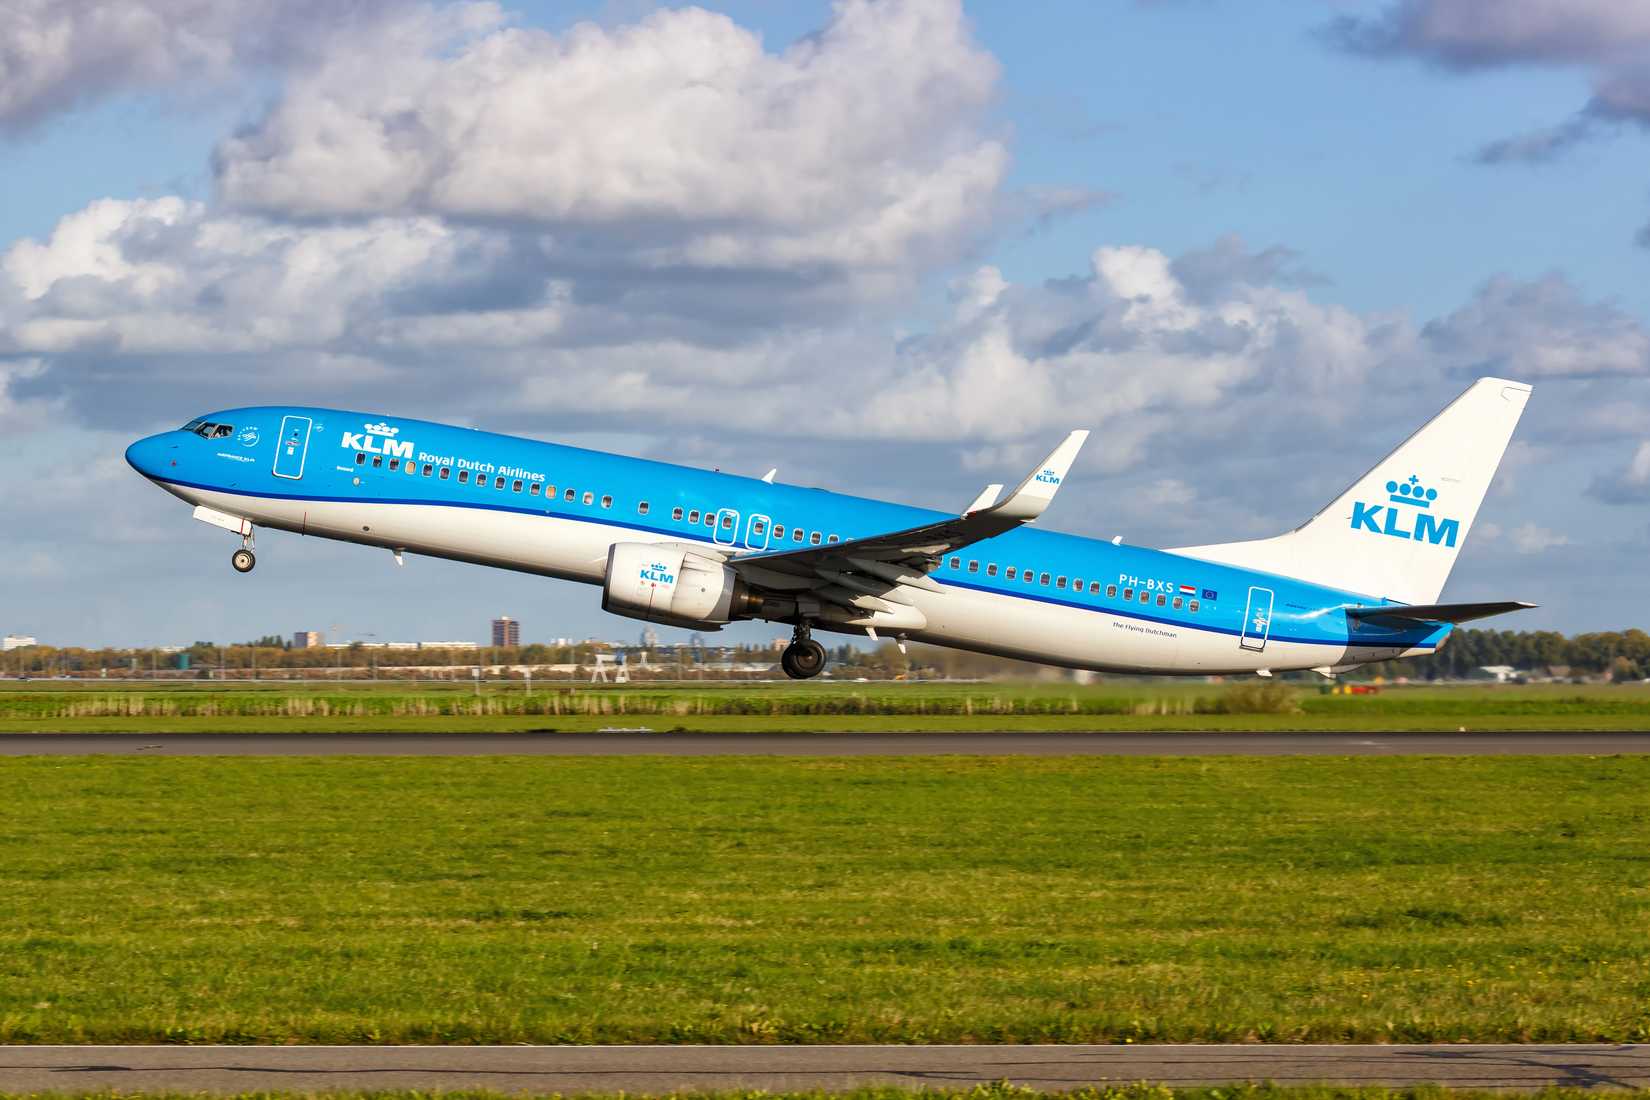
The sales record reflected the aircraft’s limited fit. Across its production run, the 737-900 was delivered in just 52 examples to a small group of airlines, including Alaska Airlines, KLM, Korean Air, Shenzhen Airlines, Jet Airways, and Continental Airlines, whose fleet later became part of United Airlines following the merger. The precise mix of operators changed over time, but the overall result was a niche model rather than a widely adopted member of the 737 family.
Alaska, as launch customer, could make use of the jet within its existing 737 fleet and deployed it on busy West Coast markets. Boeing’s first delivery announcement in May 2001 highlighted the aircraft’s size and Alaska’s plans to use it on routes connecting Seattle with cities including Anchorage, Phoenix, Las Vegas, Los Angeles, and San Diego. Its initial two-class cabin carried fewer than the maximum 189 passengers, demonstrating that the model could still serve a conventional network airline whose needs differed from those of a high-density low-cost carrier.
|
Current 737-900 Operators |
|
|---|---|
|
Airline |
Total |
|
Jin Air |
3 |
|
KLM Royal Dutch Airlines |
5 |
|
Korean Air |
9 |
|
United Airlines |
12 |
For Boeing, however, a narrow customer base limited the commercial payoff. A successful variant needs enough demand to support production, sales campaigns, engineering investment, and a durable place in the product range. When only a handful of airlines order a particular version, the manufacturer has less opportunity to spread variant-specific costs across numerous deliveries. Ultimately, the -900 was not unusable, and its low sales do not mean every operator regretted buying it. The more revealing point is that the model failed to attract the breadth of demand Boeing sought. The 737-800 already covered much of the family’s market, while the -900’s limitations made it less persuasive for customers needing a genuine high-capacity aircraft.
The 737-900ER Corrected The Weaknesses

Boeing responded with the 737-900ER, a revised version that addressed both passenger capacity and range. The aircraft first flew in September 2006 and entered service with Lion Air in 2007. Rather than simply extending the fuselage again, Boeing altered the configuration to make the extra length more useful. An additional pair of exit doors behind the wings, alongside a redesigned rear pressure bulkhead, enabled a higher maximum seating capacity. The -900ER was approved for up to 220 passengers, rather than 189, depending on its configuration.
The revised model also improved its range capability. It could be equipped with up to two auxiliary fuel tanks in the cargo hold, came with winglets, and had a higher maximum takeoff weight. Those changes gave airlines more flexibility to carry a larger passenger load over longer distances, strengthening the aircraft’s economics on routes where the original -900 had struggled to justify its size. Boeing later said the -900ER could carry up to 26 more passengers or fly about 500 nautical miles (926 km) farther than the standard -900. It also cited lower operating costs per trip and per seat-mile than competing models, though such manufacturer comparisons depend on assumptions and operating conditions.
Sales numbers proved the difference; Boeing delivered 505 737-900ERs, nearly ten times the total for the original -900. Airlines could now buy the longer 737 for a clear reason: it offered more seats when needed and greater range, without abandoning the operational familiarity of the 737NG family. The ER variant therefore became the version that fulfilled the commercial promise of a stretched 737, while the original model largely faded from Boeing’s catalog.
A Lesson In Designing For Airline Economics

The original 737-900 illustrates why aircraft development cannot rely on dimensions alone. Adding fuselage length creates value only when the rest of the design allows airlines to use that space profitably. In this case, the exit layout capped passenger numbers, while unchanged fuel capacity and takeoff-weight limits restricted the benefits of carrying more payload over longer routes. The A321 made those compromises harder to defend, and sales remained limited.
Boeing later identified the real market with the 737-900ER’s stronger performance. The future lesson for narrowbody development is increasingly relevant as airlines seek to balance seat capacity, fuel efficiency, range, airport compatibility, and fleet commonality. A larger aircraft must provide measurable gains across the routes an airline actually flies, not merely offer a longer cabin. As Boeing and Airbus compete for the next generation of single-aisle demand, the winners will be the designs that align capacity with range and operating economics from the outset.