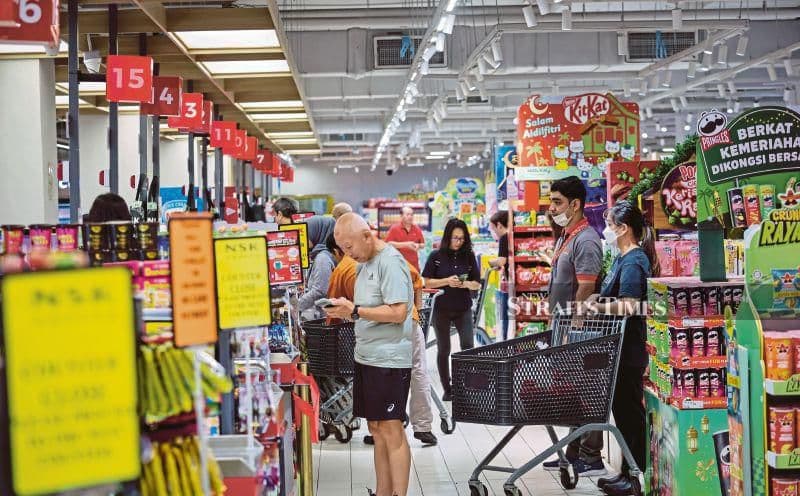
KUALA LUMPUR: Consumer and property stocks are set to gain from the 2027 Budget as cash handouts and housing incentives increase household spending power and support demand for homes, according to research firms.
However, the budget's benefits are unlikely to be evenly spread as higher labour costs threaten to squeeze margins in plantations, technology, rubber products, electronics manufacturing services, gloves, construction and selected retail segments.
MBSB Research identified consumer staples and value retailers as the clearest beneficiaries.
It named 99 Speed Mart Retail Holdings Bhd, MR DIY Group (M) Bhd, Leong Hup International Bhd and Nestlé (Malaysia) Bhd among its top picks.
"The strongest beneficiary is consumer staples and value retail because household assistance is large, direct and explicitly usable for essential goods," MBSB Research said.
Hong Leong Investment Bank Bhd (HLIB) also favoured consumer and property stocks, and identified oil and gas (O&G) and labour-intensive sectors as potential losers.
"Overall, we feel that 2027 Budget is 'for Main Street rather than Malaysia's Wall Street' and we expect a muted market reaction," analysts Jeremy Goh and Felicia Ling said.
RHB Research similarly maintained an "Overweight" rating on the consumer and property sectors, citing continued government support for household spending and homeownership.
CONSUMER SPENDING GETS A BOOST
MBSB Research said the RM16 billion allocation for Sumbangan Tunai Rahmah and Sumbangan Asas Rahmah (Sara), along with additional Sara payments, should direct spending towards food, groceries and low-cost household products.
The RM750 million allocation for Jualan Rahmah and Agro Madani would provide further support.
RHB Research said adjustments to individual income tax bands and reliefs, including raising the individual income tax relief threshold to RM12,000 from RM9,000, should also support disposable income.
However, retailers may need to improve efficiency to offset higher labour costs, as passing the full increase on to consumers could dampen demand.
PROPERTY, CONSTRUCTION GAIN SUPPORT
Property developers should benefit from stamp duty exemptions for first-time homebuyers extended until end-2030 and RM20 billion in housing guarantees.
The exemptions cover homes priced up to RM500,000, with partial relief for eligible homes up to RM750,000.
MBSB Research favoured Mah Sing Group Bhd and Matrix Concepts Holdings Bhd, while HLIB picked Matrix Concepts and SkyWorld Development Bhd.
RHB Research named Eco World Development Group Bhd as its top property pick and highlighted opportunities linked to the Johor-Singapore Special Economic Zone.
This includes the proposed Nexus Sedenak industrial development, with estimated investment potential of RM12 billion.
Construction companies could benefit from RM83 billion in federal development expenditure, up from the revised RM81 billion in 2026, and projects such as the East Coast Rail Link Phase Two, Penang Light Rail Transit Mutiara Line and Trans Borneo Highway.
The RM2.5 billion allocation to reduce non-revenue water losses could also support piping contractors.
MBSB Research favoured Gamuda Bhd, Sunway Construction Group Bhd, IJM Corp Bhd and Malayan Cement Bhd, while RHB Research picked Gamuda, Kerjaya Prospek Group Bhd and Sunway Construction.
RHB Research said public infrastructure and private developments, including data centres, should sustain contractors' workloads.
Reintroducing the variation of price clause for higher industrial diesel and bitumen costs could ease cost pressures.
UTILITIES LEAD INVESTMENT THEME
MBSB Research identified Tenaga Nasional Bhd (TNB) and the grid-electrification ecosystem as structural beneficiaries.
This is supported by TNB's RM15 billion grid investment programme, renewable energy initiatives and rising electricity demand from data centres and artificial intelligence infrastructure.
The firm kept its "Positive" stance on the sector, underpinned by the structural growth in electricity demand.
This is particularly from data centres and industrial expansion, which should sustain investments in power generation and transmission infrastructure.
"Meanwhile, the continued push towards energy transition, supported by initiatives such as LSS6, battery energy storage system adoption and the Corporate Renewable Energy Supply Scheme acceleration package should provide a sustained pipeline of opportunities for renewable energy developers and EPCC contractors," it said.
RHB Research expects contract awards to accelerate over the next year, creating opportunities for mechanical and electrical players with exposure to utility infrastructure.
"Ongoing cross-border initiatives under the Asean Power Grid involving TNB and Petronas could sustain high-value regional capital expenditure pipelines over the medium term," it added.
Both research firms favoured utilities and renewable energy stocks such as TNB, Samaiden Group Bhd and YTL Power International Bhd.
HIGHER LABOUR COSTS BITE
Research said the higher minimum wage could weigh on plantations, technology, rubber products, electronics manufacturing services and glove makers where costs cannot be passed on.
The minimum wage will rise from RM1,700 to RM2,000 a month from June 2027.
RHB Research estimated that the increase could reduce annual earnings by 2.2 per cent to 10.3 per cent for selected plantation companies in a worst-case scenario, assuming a RM300 monthly increase for foreign workers in Malaysian estates.
For selected technology companies, including outsourced semiconductor assembly and testing players and electronics manufacturing services providers, it estimated an annual earnings impact of one to 13 per cent if costs could not be passed on.
RHB Research also estimated a roughly 12 per cent full-year impact on core earnings for the glove manufacturers it covers, excluding Supermax Corp Bhd, before cost pass-through.
The impact in 2027 should be lower because the wage increase starts in June.
Despite wage pressures, RHB Research maintained an "Overweight" rating on construction.
It said the impact should be manageable given prevailing industry wages and the project pipeline.
It was "Neutral" on automotive, citing the risk of weaker vehicle sales after four consecutive years of records, although incentives for local electric vehicle assembly could benefit domestic suppliers over time.
HLIB warned that higher dividends from Petroliam Nasional Bhd could support government revenue but limit upstream investment, creating a potential headwind for oil and gas service providers.
"We believe Petronas' increased dividend payout could limit funding available for upstream investments, a potential headwind for upstream service providers including Dayang Enterprise Holdings Bhd, Deleum Bhd, Velesto Enregy Bhd, Perdana Petroleum Bhd and and Keyfield International Bhd," it said.
© New Straits Times Press (M) Bhd