South Korea's insurance industry is expected to grow at less than half this year's pace in 2027, as sales structures concentrated in a handful of products and distribution channels push up costs and new regulations taking effect next year weigh on expansion.
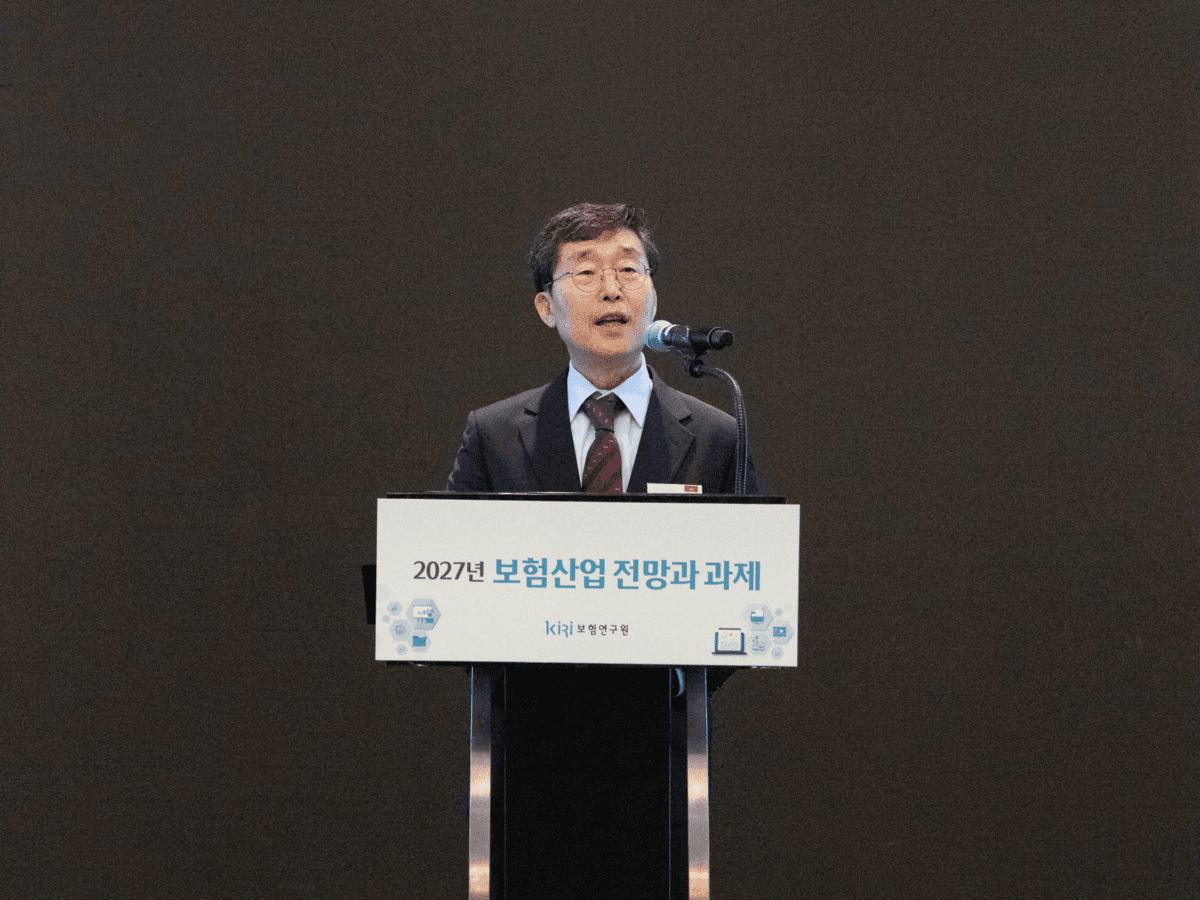
The Korea Insurance Research Institute said total premiums will reach about 299 trillion won next year, up 3.5% from this year, at a seminar on the 2027 insurance industry outlook and tasks held at the Conrad Seoul hotel in Yeouido on the 22nd. That is 4.5 percentage points below the 8.0% growth projected for this year. Premium growth has now declined for two straight years after reaching 11.0% in 2025.
Life insurance premium income growth is forecast to slow to 2.3% next year from 8.8% this year, hurt by declines in savings-type policies and retirement pensions. Non-life insurance growth is expected to ease to 4.5% from 7.2% as the boost from auto insurance premium increases fades and long-term non-life policies lose momentum.
The institute pointed to the concentration of sales in specific products and channels as a structural problem for the industry. Life insurers have focused on policies with no or low surrender values, while non-life insurers have concentrated on illness and injury coverage. Distribution has also tilted toward face-to-face sales and general agencies, intensifying cost competition centered on sales promotion spending. "Rising operating expenses are not translating into new-contract CSM, which is eroding capital productivity," said Kim Dong-gyeom, head of the institute's financial market analysis division.
A planned overhaul of sales commission structures, a new core capital ratio framework and upgraded actuarial assumptions, all set to take effect next year, were also cited as factors that could limit insurers' capacity to write new business. Adjustments to acquisition costs and the burden of raising capital could dampen incentives to sign new contracts, the institute said.
Insurance chief executives were also downbeat about next year. In a survey of 29 CEOs, uncertainty over monetary policy and interest rate volatility ranked as the biggest threat to management, followed by a delayed recovery in domestic demand, inflationary pressure and swings in equity and credit markets. Outlooks for growth, profitability and financial soundness in both the life and non-life sectors all fell below the neutral score of 3. The soundness outlook for the life insurance sector was the weakest at 2.31.
For sustainable growth, the institute advised insurers to strengthen earnings from their existing core coverage while reallocating resources to new areas such as retirement income, health and care services, and corporate risk. It also stressed the need to redesign claims and payout operations and to build commission systems that reflect how well contracts are retained.
"Sustainable growth is determined not by sales capacity but by the size of the risk you can bear," said Kim Hun-soo, president of the Korea Insurance Research Institute. "Insurers need to build risk management capabilities to close the protection gap and deliver growth that consumers can feel."