
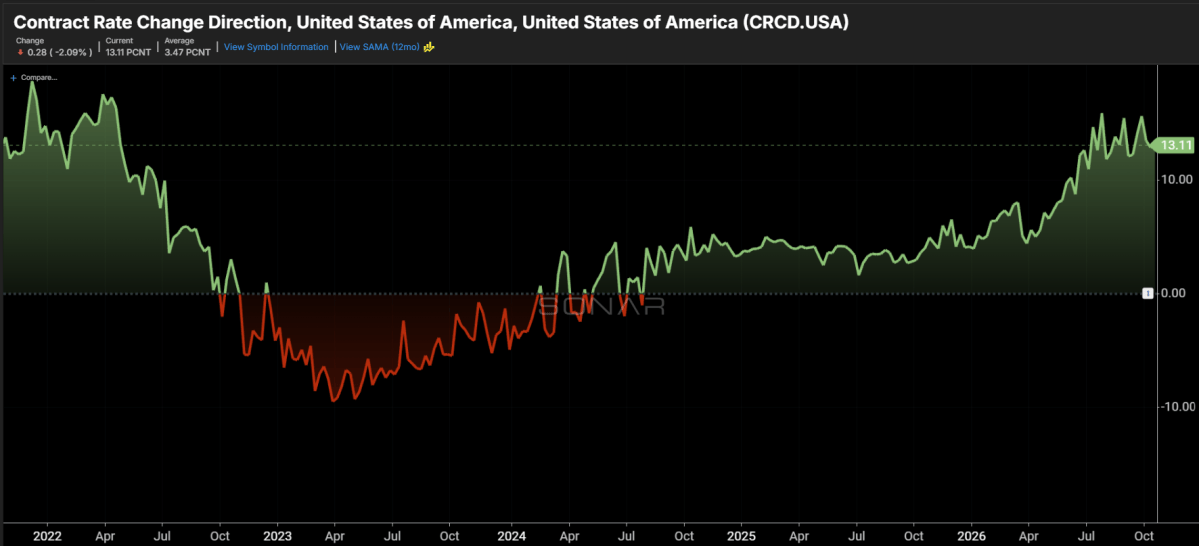
Chart of the Week: Contract Rate Change Direction Index – USA SONAR: CRCD.USA
Shippers who have reset truckload contracts over the past several months are paying about 13% more than the rates they replaced. That is the reading from SONAR’s new Contract Rate Change Direction index (CRCD.USA), which stood at 13.11% on Oct. 22, up from 3.53% a year earlier.
This index measures the average percentage difference between a new contract base rate and the one it replaced within an established shipper-carrier relationship. It counts a change only when the old rate had held steady for more than 90 days, which filters out short-term noise and isolates true bid-cycle repricing. The index is a seven-day rolling average, updated daily.
The metric strips out the effects of temporary route guide waterfalling and contract-plus pricing to show more durable changes in rates. Route guide failures say a lot about market pressure, but the rates they produce can overstate what eventually becomes the sustained cost.
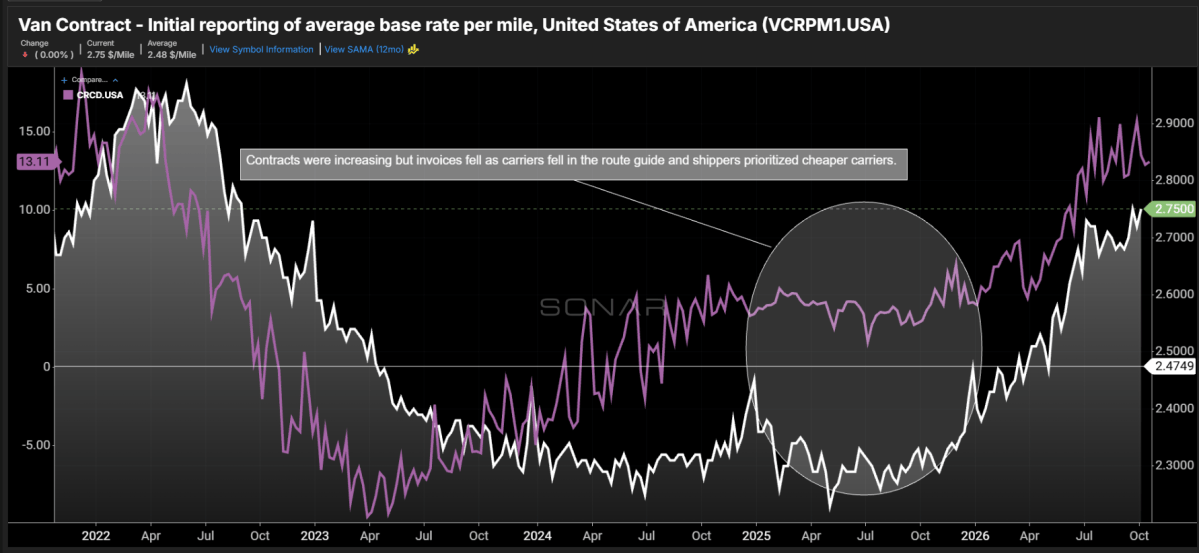
It is also important to note that the index measures only contracts that are changing. That makes it largely agnostic to volume, and readings can thin out when few contracts are changing. CRCD also does not account for whether a carrier moves up or down in a shipper’s routing guide after a rate change. That gap showed up in 2025: contract resets ran at roughly 3% to 4% starting in late 2024, yet the average contract rate index (VCRPM1) showed flat to slightly lower invoiced rates through most of the year.
Pairing the two indexes shows how successful carriers’ rate increases have been, or not. CRCD leads invoice data directionally, but it does not predict whether increases will stick. That carriers were pushing for increases a year before the recent cycle turned should be a cautionary tale for shippers now navigating a period of extreme rate inflation.
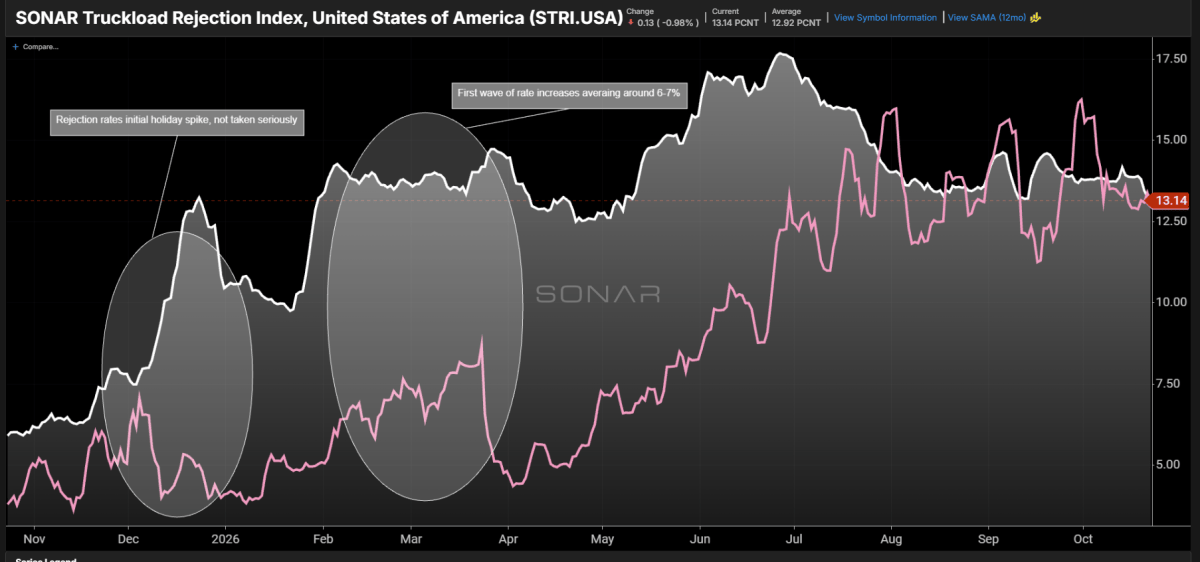
The current 13% reading shows that most contract changes are now landing well into the double digits, nearly a year after tender rejection rates jumped above 9%. As the chart above shows, contract rate changes lag rejection rates, which suggests it takes a sustained period of elevated rejections before contract rate increases follow. With rejection rates averaging close to 13% over the past few months, increases are still coming in above 10%. Note that CRCD is not an annualized rate. It measures the average change in contracts when they move, and a change does not register until it is implemented.
The takeaway for shippers is that carriers are still securing strong rate increases, and the contract rate index (VCRPM1) suggests those increases are sticking. The average increase should moderate as carriers move onto more financially healthy contracts. However, both FMCSA and tender data suggest capacity has not grown meaningfully over the past 12 months despite elevated rates, so it may take time for the curve to flatten.
About the Chart of the Week
The FreightWaves Chart of the Week is a chart selection from SONAR that provides an interesting data point to describe the state of the freight markets. A chart is chosen from thousands of potential charts on SONAR to help participants visualize the freight market in real time. Each week a Market Expert will post a chart, along with commentary, live on the front page. After that, the Chart of the Week will be archived on FreightWaves.com for future reference.
SONAR aggregates data from hundreds of sources, presenting the data in charts and maps and providing commentary on what freight market experts want to know about the industry in real time.
The FreightWaves data science and product teams are releasing new datasets each week and enhancing the client experience.
To request a SONAR demo, click here.
The post Truckload contract rate increases riding steady above 10% appeared first on FreightWaves.