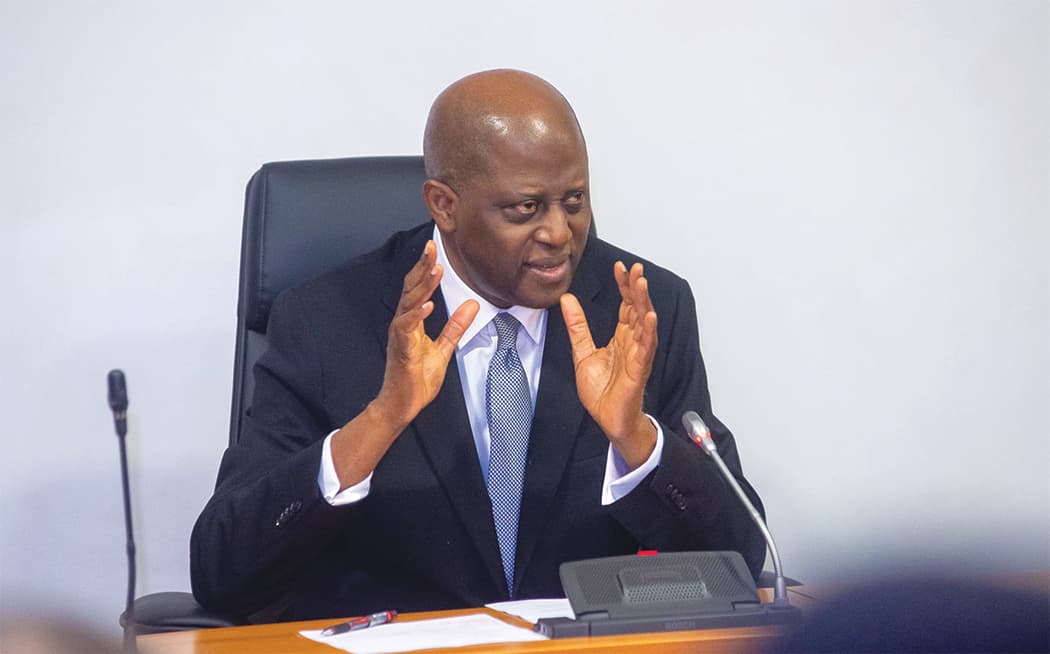
At the close of the IMF/World Bank Annual Meetings in Bangkok, Thailand, Central Bank of Nigeria Governor Olayemi Cardoso discusses Nigeria’s economic recovery reforms to attract long-term investment and the monetary policy implications of easing inflation. He also examines financial ties with China and other Asian economies, banking recapitalisation, monetary policy committee independence, and the promise and perils of artificial intelligence. Nume Ekeghe presents excerpts
As the meetings have come to an end, can you speak to the key takeaways from the IMF/World Bank Annual Meetings?
These meetings come at an important moment for Nigeria. Our economic indicators are showing encouraging improvements following a period of significant policy adjustments.
Headline inflation declined to 14.63 per cent in September 2026, a development we welcomed during our stay here, from approximately 34.8 per cent at the end of 2024.
External reserves have risen above $55 billion, their highest level in 18 years, while formal remittance inflows are approaching $1 billion monthly.
Our banking sector has mobilised N4.65 trillion in fresh capital through the recapitalisation exercise, with just over 70 per cent raised from domestic investors. This strong domestic participation is an important vote of confidence in the resilience and long-term prospects of Nigeria’s banking system.
International assessments are also recognising the progress being made, including Fitch’s recent revision of Nigeria’s sovereign outlook from stable to positive. These are important gains, and I want to acknowledge the patience and resilience of the Nigerian people through a difficult period of adjustment. Our responsibility now is to consolidate this progress and translate it into greater investment, productivity and sustainable economic growth.
During the Annual Meetings, we engaged international partners on Nigeria’s economic outlook and the challenges facing the global economy. Together with the Honourable Minister of Finance and Coordinating Minister of the Economy, we held bilateral meetings with the IMF’s First Deputy Managing Director, Mr Dan Katz, and the President of the World Bank Group, Mr Ajay Banga.
Our discussions covered Nigeria’s policy priorities and opportunities for continued cooperation. We also engaged S&P Global Ratings, Moody’s and Fitch Ratings on Nigeria’s economic outlook and the path towards attaining investment-grade ratings in the medium term.
These engagements underscored the importance of policy consistency, credible institutions and effective coordination between fiscal and monetary authorities.
Beyond these bilateral engagements, I was pleased to contribute Nigeria’s experience to two important IMF discussions.
At the flagship debate on the global economy, Forging Resilient and Dynamic Economies for the Future, I joined IMF Managing Director Kristalina Georgieva and other international leaders to share lessons from Nigeria’s experience for emerging economies.
For Africa, the ambition must go beyond surviving crises. In an increasingly uncertain global economy, we must build economies that are more productive, competitive and resilient to future shocks.
We also discussed artificial intelligence and its implications for the global economy. Africa cannot afford to be a passive participant in the AI revolution. We must develop the capabilities to shape its opportunities and capture the economic value it creates.
At the IMF seminar titled How Central Banks Decide: Committee Decision-Making and Communication in an Era of Uncertainty, moderated by Mr Dan Katz, I discussed the CBN’s experience in strengthening monetary policy decision-making, transparency and communication.
Our September decision to reset the monetary policy rate from 26.5 per cent to 23 per cent provided a practical example of the importance of credible institutions and clear policy communication.
I also participated in the Group of Thirty’s international banking seminar and discussions on African monetary cooperation, including progress towards operationalising the African Monetary Institute in Abuja.
Alongside the Annual Meetings, we have been pursuing a broader strategy to deepen Nigeria’s financial relationships with Asia through a series of engagements across the region.
In Singapore last week, on our way to Bangkok, we met with the Monetary Authority of Singapore, signed a memorandum of understanding with the Global Financial and Technology Network, and convened the Nigeria-Asia Financial Connectivity Dialogue in collaboration with JPMorgan, the Nigerian Exchange Group, and FMDQ Group.
A particularly important engagement here in Bangkok was my meeting with Mr Pan Gongsheng, Governor of the People’s Bank of China.
Our discussions focused on strengthening financial cooperation between Nigeria and China, particularly in cross-border payments, settlement arrangements, financial technology and trade finance.
We intend to build on these discussions during our forthcoming visit to Beijing, with an emphasis on practical arrangements to facilitate cross-border payments, support trade and investment flows, and strengthen financial intermediation between our two economies.
Together, these engagements are intended to deepen financial market linkages and expand opportunities for economic cooperation between Nigeria and Asia.
Looking ahead, our focus at the Central Bank remains firmly on price stability, maintaining monetary discipline and safeguarding the stability of the financial system.
We will continue to pursue a data-dependent and well-communicated monetary policy, with single-digit inflation remaining a medium-term objective.
We leave Bangkok with stronger international relationships and a clearer understanding of the opportunities ahead. Our task now is to build on these gains and ensure that Nigeria’s financial system is resilient, competitive and well positioned to support the country’s long-term economic ambitions.
Beyond the points you have already made, what are your major takeaways from those sessions? What lessons can Nigeria learn from these discussions? Also, can you elaborate on your session on how central banks make decisions, as well as the broader discussions on central banking?
Generally, I would identify three or four important takeaways. First, despite global fragmentation and the enormous headwinds experienced over the past year, the global economy has weathered the challenges.
However, considerable uncertainty and fragility remain. We cannot afford to rest on our laurels. Given the series of shocks the world has experienced, even a relatively small shock in one part of the global economy could have major repercussions elsewhere.
Second, the private sector is critical. Governments must create an enabling environment that allows businesses to invest, thrive and create jobs.
Third, collaboration is essential. There has never been a greater need for collaboration across national boundaries, geographical regions, institutions, governments and the private sector than there is today.
The fourth point relates to the positive reception Nigeria has received during these meetings. You would be surprised by how closely people monitor developments in different economies.
As you noted, I have participated in several forums with central bank governors from around the world. You would be surprised by how much they know about Nigeria’s economic journey, the actions we have taken, the currency and the measures that have moved the country from crisis towards stability.
More specifically, I believe there is a growing appreciation that Nigeria has passed through very difficult times and emerged stronger. That was evident in some of the examples discussed during the meetings, including our monetary policy reset.
As I mentioned earlier, we were pleased to receive the latest inflation figures while we were here. The decline in inflation further validates the position we took at the Monetary Policy Committee (MPC).
There was considerable interest in Nigeria’s MPC structure, particularly the relatively large number of external members compared with many other jurisdictions. There was also interest in the fact that the fiscal leadership has representation on the committee.
Beyond whether members are internal or external, the most important consideration is their character and independence of mind. We look for independent-minded individuals to serve on the MPC because this helps prevent groupthink, which can easily lead to poor decisions.
One particularly important question was how we ensure external MPC members have access to information equal to, if not greater than, what internal members have. We have assigned internal resource persons to each MPC member to provide the necessary support and information.
We also regularly organise strategy sessions with MPC members. Currently, a group is undertaking study tours to other jurisdictions to examine how monetary policy committees operate in different environments.
We are doing everything possible to ensure that we get the best out of the committee. Investor confidence had deteriorated, and the country was in a very difficult position. We therefore had to ensure that the committee brought together people with diverse skills, experience and independent perspectives.
The Nigeria Investors Forum generated considerable interest in the investment opportunities presented through the Investment Deal Room. From the CBN’s perspective, what is needed to sustain investor confidence and encourage long-term capital flows into Nigeria?
I think the answer is simpler than it may seem: we must stay the course. The question has come up repeatedly during our engagements. Investors want to know whether we will remain committed to our policies and reforms.
That is where the answer lies. In difficult circumstances, governments can be pressured to abandon their policies. When that happens, all the hard work already undertaken can be undermined.
But we are not about to do that. We have come a long way and demonstrated that the reforms can work. Stability is returning to our economy, and we must build on that progress. The last thing we intend to do is undermine the difficult reforms we have implemented. We will stay the course.
How can African central banks and development finance institutions work more closely together to mobilise long-term capital for Africa’s development?
This is where we begin to appreciate the benefits and power of economic stability. When stability returns, and foreign exchange becomes less of a constraint, it becomes easier to develop financial products and investment structures that support long-term financing.
At one point, the premium between the official exchange rate and the parallel-market rate was approximately 60 per cent. Today, it has fallen to about 3 to 4 per cent.
These developments encourage investment and make it easier to structure financial products around a more stable currency and economy.
As custodians of monetary stability, we have a responsibility to maintain that stability. Development finance institutions, on the other hand, have a responsibility to channel resources into development.
The prospects for mobilising long-term naira-denominated capital have increased significantly as a result of the stability we have achieved in the markets. The risks previously associated with exchange-rate volatility and sharp currency depreciation have receded considerably. We therefore expect development finance institutions to play a greater role in mobilising and deploying long-term capital.
A clear division of responsibilities is essential. The CBN’s responsibility is to ensure monetary and price stability, not just in the short term but also over the long term, while bringing inflation down and maintaining a stable macroeconomic environment.
Development institutions, including the Africa Finance Corporation, the Bank of Industry and the Development Bank of Nigeria, have their own mandates to finance development. With the improved stability we are witnessing, it should become easier for these institutions to mobilise resources and support productive activities.
I am pleased that, with this appointment, we will be able to work more closely with the AFC. The institution has demonstrated over time that it can mobilise resources not only in Nigeria but across Africa. We will work with it to advance this objective further.
Developed economies appear particularly focused on AI as a driver of global economic growth, although they also recognise the risks it presents. Where do you see the opportunities for Nigeria, and what major risks should we be concerned about?
On artificial intelligence and the opportunities it presents, I want to make an important distinction. AI’s impact on the developing world differs from its impact on emerging markets and advanced economies.
Developing countries face a different situation. For us, this is a defining moment. It could determine whether we achieve convergence with advanced economies or fall further behind. This is not just about differences between households or businesses within emerging markets. It is also about whether the gap between advanced and developing economies widens or narrows.
Artificial intelligence presents an opportunity to close that gap, provided we get it right. I believe the first step is to develop a clear strategy. From my research, I have found that many African economies have yet to develop comprehensive strategies to address this challenge. The risk is that the opportunity will remain available, but if we are not careful, it could pass us by.
At the Central Bank, we decided some time ago that the best approach was to start from the top. We brought the CBN Board together with AI specialists for an extensive discussion on the subject. We believe the Board and management must drive the initiative. It should be a top-down process rather than simply a bottom-up initiative.
For that to happen, those at the top must understand the opportunities and risks. AI carries significant cybersecurity risks. Other risks could destabilise an economy, complicate monetary policy, and create challenges for financial institutions.
AI could improve productivity in several areas, including pharmaceutical production and the operations of small and medium-sized enterprises. Businesses have much to gain by adapting and adopting these technologies.
There is great potential, but appropriate safeguards must be put in place. Collaboration must also be part of the discussion. We need globally aligned standards, to the extent possible, so one part of the world does not move in a direction fundamentally incompatible with developments elsewhere.
There is a lot of work to do in the AI space when we get back to ensure that we get the best out of it.
You mentioned that your engagements in Singapore and your upcoming visit to Beijing are part of a broader strategy to strengthen Nigeria’s financial ties with Asia. What is driving this approach, and what outcomes do you hope to achieve, particularly from your meeting with the Governor of the People’s Bank of China?
We are interested in seeing how we can deepen collaboration between institutions, including Chinese banks, the Central Bank of Nigeria, commercial banks and other institutions, particularly in the payments system.
China has a robust payments system, and we are exploring whether we can learn lessons from it. In particular, there is considerable interest in peer reviews between the People’s Bank of China and the Central Bank of Nigeria.
When we travel to China, the relevant teams will roll up their sleeves and examine the details to determine what makes sense and what does not. We want to avoid a situation in which these engagements become merely a talk shop. I can confidently say that, just as we are interested in making this work, Chinese bank leadership is also interested.
Finally, bear in mind that, despite the considerable liquidity available in China, there has not been much investment in Nigerian financial instruments over time. This could be an opportunity to change that trajectory and generate greater interest from Asian markets in Nigerian instruments and African instruments generally.
A few banks have not completed recapitalisation. Banks such as Providus and Union Bank have since consolidated and started publishing as a new entity. Where are we with the others? I know some are subject to legal orders, but how long will you wait for these issues to be resolved?
On the banks, the matter is still a work in progress. As you rightly pointed out, we are dealing with certain legal and possibly regulatory hurdles that we must clear. However, I am confident that things are moving in the right direction. A lot is happening that is obviously not for public consumption, but developments are moving in a very positive direction.
I would also say that customers doing business with these banks should continue to do so. You have nothing to worry about; continue your business with them. The banking system is strong and resilient.
You are also right that a handful of banks remain outstanding. But most banks have raised substantial capital. N4.75 trillion is not a small amount. Of that amount, approximately 72 to 73 per cent came from domestic resource mobilisation.
That is a big deal. It reflects the fact that Nigerians, unlike in the past when they might have been inclined to move their money abroad, are now showing confidence in their domestic markets. That is something we want to protect.
We have to work hand in hand with the Nigerian Exchange Group and FMDQ Group to ensure that the gains we have achieved are consolidated.
The same applies to the Dangote initial public offering. Why is there so much interest from across the African continent? It is the same reason: the stability brought to the market has increased investor confidence.
What is your view on the balance between satisfying the investment community and the people?
I think one common thread that cannot be wished away when dealing with markets is transparency. So far, we have come a long way in being as transparent as possible, and this is one of the things that gives investors confidence, whether in Indonesia, Nigeria or anywhere else.
We must always watch that transparency index. These market exits don’t happen without reason.