Treasury bonds issued during Korea's low-interest-rate era begin maturing in waves from next year, deepening the government's fiscal dilemma. Officials say the immediate cost of rolling over that debt is not large enough to threaten budget management. But with net new treasury bond issuance running close to 100 trillion won a year, and refinancing rates on older low-coupon bonds climbing, calls are growing for the government to relieve the mounting fiscal pressure.
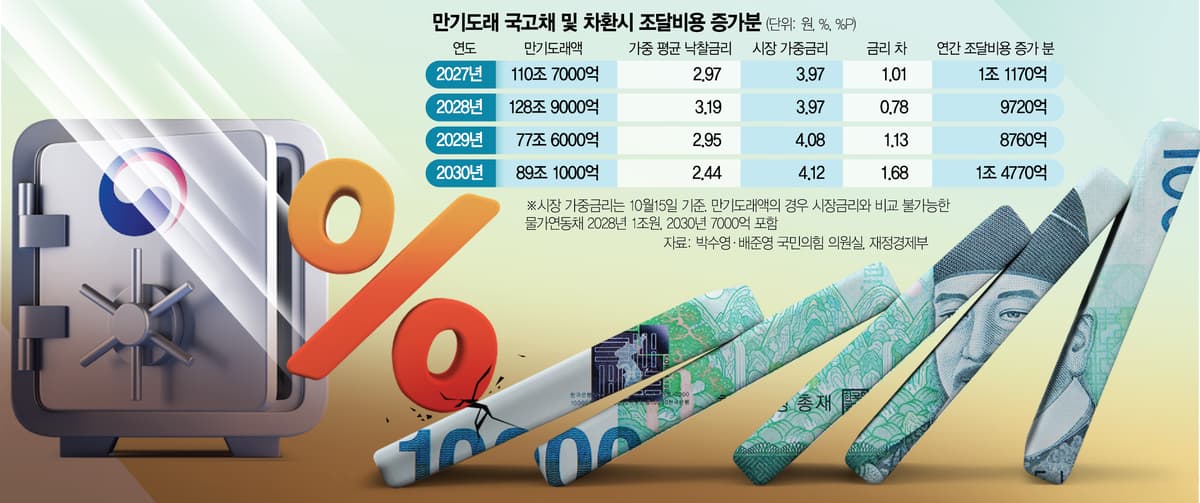
Treasury bonds maturing in 2030 carried an average winning yield of 2.44% when they were sold, below the 3.19% on bonds maturing in 2028, according to a breakdown of all treasury bonds maturing between 2027 and 2030 that the Ministry of Finance and Economy submitted on the 16th to Park Soo-young and Bae Joon-young, both lawmakers of the People Power Party. The gap is sharpest in 10-year bonds: 28.3 trillion won maturing in 2029 was sold at a weighted average winning yield of just 1.58%, and 40.9 trillion won maturing in 2030 at 1.66%. That means 69.1 trillion won of 10-year paper maturing across those two years was raised at an average rate in the mid-1% range. Of that, 63.3 trillion won was sold at individual winning yields that were actually in the 1% range.
Applying market rates as of the 15th of this month to treasury bonds maturing each year through 2030, and assuming each is rolled over into the same maturity, the increase in funding costs comes to an estimated 1.117 trillion won in 2027, 972 billion won in 2028, 876 billion won in 2029 and 1.477 trillion won in 2030. Maturing debt in 2030 totals 89.1 trillion won, about 40 trillion won less than in 2028, yet the added funding cost from rollovers is projected to be larger.
Rollovers are not the only problem. Total treasury bond issuance is planned at 222.8 trillion won next year. Of that, 126.6 trillion won covers refinancing, including redemptions and market-making operations, while net new issuance that adds to outstanding national debt comes to 96.3 trillion won. The net figure is 13.1 trillion won smaller than this year but still approaches 100 trillion won. The result is a structure in which debt raised cheaply in the past is being swapped into higher-rate debt, while freshly accumulated debt also costs more than it did during the low-rate years.
Applying a budget planning rate of 4.1% for 2027, the government projects treasury bond interest costs will rise by 10.7 trillion won, from 40.4 trillion won next year to 51.1 trillion won in 2030.
Abroad, the same dynamic has already become a major constraint on fiscal management. Government interest payments across member countries came to 3.3% of gross domestic product in 2025, close to the 3.4% peak of the past decade, according to a global debt report released in March by the Organisation for Economic Co-operation and Development. Bonds issued in the low-rate era are being refinanced at higher rates just as governments need to raise large volumes of new funding, keeping interest burdens elevated.
The United States is the clearest case. In a fiscal outlook released in February, the Congressional Budget Office projected federal net interest spending would more than double, from $1 trillion in 2026 to $2.1 trillion in 2036, with about half the increase stemming from a rise in the average interest rate on government debt. In Britain, debt interest spending in the 2025-26 fiscal year came to about 109 billion pounds, or 8% of total public expenditure. The more interest costs expand, the less fiscal room governments have for other policies.
The government also sees little chance that the rollover burden will escalate into a fiscal crisis. Hwang Soon-kwan, director general of the ministry's treasury bureau, said pure interest costs could rise because rates are higher than in the past, but stressed that "our country's overall debt level is markedly lower than in other advanced economies, so even if interest costs increase, risk management is in no way a problem." What has changed, however, is that debt built up during the low-rate years is being replaced with more expensive debt at the same time as new debt begins piling up at high rates.
Experts say the pace of the increase in interest costs needs to be managed pre-emptively, through steps such as using excess tax revenue to pay down national debt and adjusting the volume and maturity structure of treasury bond issuance. Woo Suk-jin, a professor of economics at Myongji University, said controlling issuance volumes and conducting buybacks are worth using as policy tools, adding that "redeeming treasury bonds with excess tax revenue is also part of the response."
The government plans to use a future response fund next year to cut net treasury bond issuance by 12.5 trillion won. How much further it trims year-end issuance using this year's excess tax revenue is another variable that could lower future interest costs. An official at the Ministry of Finance and Economy said it would be good to reduce treasury bond issuance volumes, but noted that next year's volume is already reflected in the budget bill and that any adjustment will be decided during National Assembly deliberations.