With sustained policy support, India has rapidly grown its domestic supply of PV modules over the past few years. Now it is moving into the more challenging sectors of cell and wafer manufacturing. The second Approved List of Models and Manufacturers (ALMM-II) came into force on June 1, 2026. This key milestone in India’s supply chain localization push extends domestic content requirements outlined in ALMM-I for modules used in any government-backed PV installation to include cells made in India. A further update set to come into force in 2028 will add the requirement for locally made ingots and wafers as well.
By the end of 2025, approximately 144.8 GW of domestic module capacity had been approved under ALMM-I, compared with 23.7 GW of cell capacity under ALMM-II, equivalent to 16% of the approved module capacity. Over the past several years, India’s module capacity has expanded rapidly, while capacity additions in the cell and wafer segments have lagged, along with solar glass and some other module components. Cell and wafer supply remains heavily reliant on imports, resulting in a structural imbalance of ample downstream capacity and insufficient upstream and midstream supply.
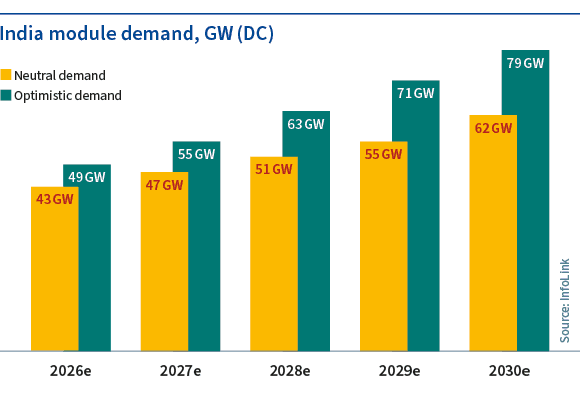
As of August 2026, module capacity approved under ALMM-I had reached approximately 217 GW, while approved cell capacity stood at around 36 GW. InfoLink forecasts India’s 2026 PV demand at between 43 GW and 49 GW. The country’s domestic cell supply remains insufficient to fully meet end-market demand, making compliant cell availability a key bottleneck.
New cell capacity will take time to translate into actual supply. India’s domestic cell supply is expected to remain constrained through most of 2027, with new capacity ramping up from mid-year. By the end of 2027, the country’s domestic cell nameplate capacity is expected to exceed 80 GW. Before significant new cell capacity comes online, the module segment will face mounting oversupply pressure from accumulated capacity. InfoLink forecasts India’s PV demand at 47 GW to 55 GW in 2027. With continued expansion of module capacity and relatively limited demand growth, the segment is expected to undergo a large-scale capacity shakeout in 2027-28.
India is unlikely to face immediate cell oversupply, even as nameplate capacity grows significantly from mid-2027. Instead, cell supply will remain tight while module overcapacity emerges earlier. As the module capacity shakeout progresses, competition will shift from expansion toward cost competitiveness, utilization rates, and supply-chain integration capabilities. Second-tier and third-tier Indian module manufacturers lacking cost advantages, vertical integration, or reliable upstream supply will face increasing pressure, with some inefficient capacity likely to exit the market during 2027 and 2028.
Upstream growth
India’s localization policies are expected to extend further upstream. Effective June 1, 2028, ALMM-III will bring wafer capacity under the ALMM framework, expanding compliance requirements beyond modules and cells. Indian manufacturers with integrated operations or early investments in wafer capacity are likely to be better positioned for this next phase of competition.
In the longer term, as ALMM and the production-linked incentive (PLI) scheme continue to drive localization, India’s PV manufacturing sector may face the risk of developing an overcapacity pattern similar to that seen in China. If domestic capacity expansion continues to outpace demand growth over the long term, the market could gradually shift from current supply-chain bottlenecks toward broad-based overcapacity, with competition moving from capacity expansion to cost competitiveness and supply-chain efficiency. In 2027, India’s PV market is expected to become more concentrated among manufacturers with cost and vertical integration advantages.
With ALMM List-III extending compliance requirements to wafers and ingots in 2028, India’s localization will also enter a new phase of supply-chain restructuring further upstream. For manufacturers, the ability to establish wafer capacity early and secure compliant upstream supply will be critical to building a durable competitive edge in the next phase and could determine their market position after the next capacity shakeout in India’s PV manufacturing sector.
The post Module feast, cell famine appeared first on pv magazine Global.