Doosan Fuel Cell (336260.KS), which has won large orders from the U.S. artificial intelligence data center market, is raising 400 billion won ($280 million) to secure the cash it needs for the business. The company has captured a growth opportunity, but accumulated losses and rising borrowings are weakening its financial structure.
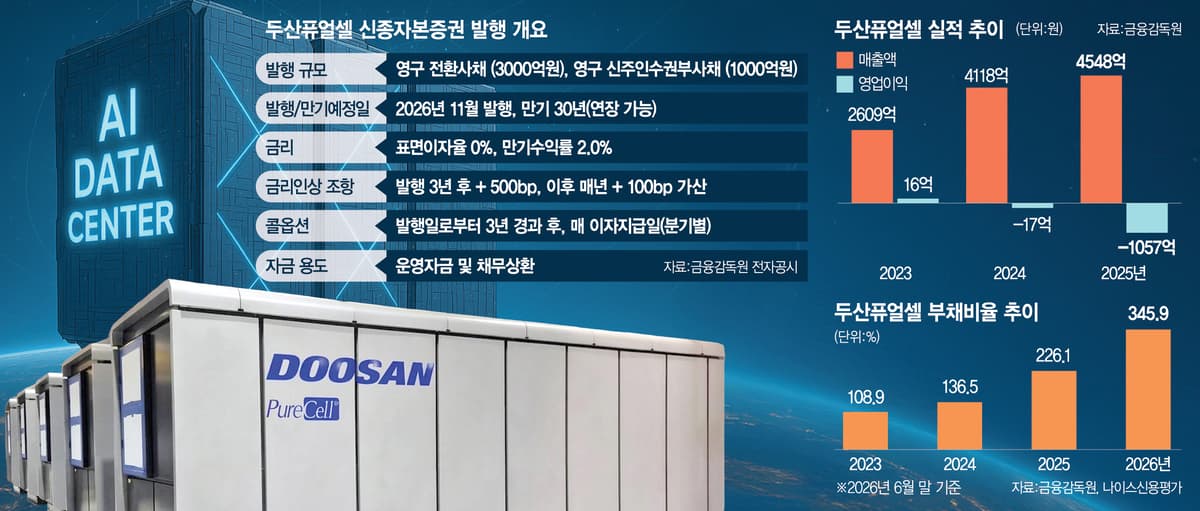
According to filings on the Financial Supervisory Service's electronic disclosure system on the 20th, Doosan Fuel Cell's board approved on the 13th the issuance of 300 billion won in perpetual convertible bonds and 100 billion won in perpetual bonds with warrants. The payment date is Nov. 12 and the maturity is 2056, extendable by 30 years at the company's discretion. The company will use 300 billion won for working capital, including raw material purchases, and 100 billion won to repay existing borrowings.
Because the proceeds are classified as equity for accounting purposes and 100 billion won will repay existing borrowings, the debt-to-equity ratio of 345.9% at the end of June would fall to the mid-130% range on a simple calculation. The actual year-end ratio could differ depending on earnings and changes in working capital.
The company turned to outside funding because of its deteriorating financial structure. Consolidated current liabilities rose 47.1% in six months to 680.9 billion won, and the debt-to-equity ratio climbed nearly 120 percentage points from 226.1%. Total borrowings increased by 118.7 billion won to 659.4 billion won. Short-term borrowings surged nearly fourfold to 285 billion won from 76 billion won, while cash and cash equivalents stood at just 34.8 billion won.
Earnings power has also weakened. First-half revenue fell 17.1% from a year earlier to 189.1 billion won, and the operating loss widened to 52.2 billion won from 13.5 billion won. Revenue declined as volumes scheduled for delivery in the second quarter were pushed into the second half. The loss widened further as a gap in solid oxide fuel cell orders lowered plant utilization rates and costs rose for replacing cell stacks in previously delivered phosphoric acid fuel cells.
Operating cash flow deteriorated to negative 52.5 billion won from negative 5.1 billion won, and inventories rose 83.9 billion won from the end of last year to 456.9 billion won, adding to the funding strain.
Paradoxically, even the recent run of orders is adding to the financial burden. In September, Doosan Fuel Cell won two orders two weeks apart for 823.6 billion won worth of fuel cells for U.S. AI data centers. But only 20% of the contract value was received as an advance payment, with the rest due as products are delivered through 2028. That means the company must spend on raw materials and production before collecting the remaining 80%, or 658.9 billion won.
The bigger issue with the bond issuance is the terms. The securities are classified as equity because investors have no early redemption right, but three years after issuance the coupon rate rises to 5% and the yield to maturity to 7%, climbing by a further 1 percentage point each year thereafter. If the full 400 billion won remains outstanding without conversion or early redemption, the coupon burden would reach 20 billion won a year from November 2029 and could grow further as rates step up. The conversion price and warrant exercise price are both 43,704 won, and full exercise would increase the number of common shares by about 14%, diluting shareholder value.
Market assessments are split. Meritz Securities said uncertainty over funding, which had been the biggest risk, has been resolved, while NICE Investors Service cautioned that "taking into account the call option and the step-up rate terms, the effective debt burden could increase over the short to medium term." In June, NICE affirmed Doosan Fuel Cell's unsecured bond rating at BBB but revised the outlook to negative from stable.
The key will be how quickly the order growth translates into actual profit and cash inflows. As of the end of June, 165 billion won in publicly offered bonds carries a covenant requiring the debt-to-equity ratio on a separate basis to stay below 700%, while 30 billion won in privately placed bonds carries an acceleration clause triggered if the credit rating falls to BB+ or lower. That is why analysts say that without an earnings recovery, this capital injection may only postpone the debt burden rather than improve the financial structure.