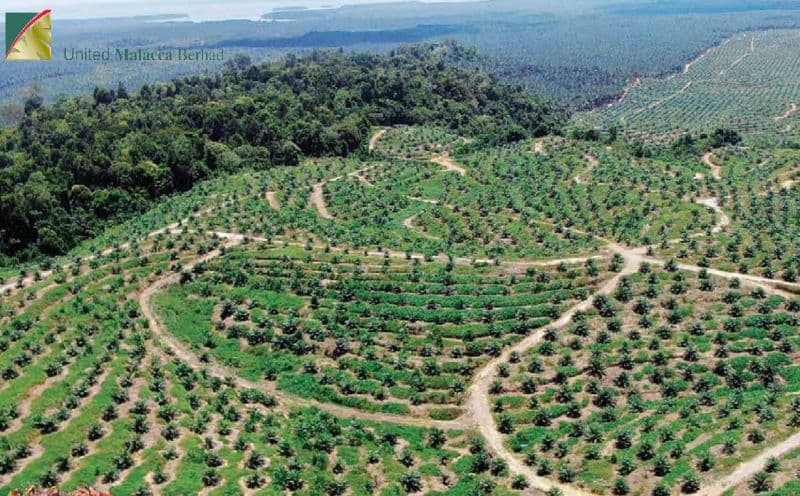
KUALA LUMPUR: United Malacca Bhd shareholders have been advised by Kenanga Research not to accept the Tee family's RM6.10-a-share mandatory takeover offer.
Kenanga Research said the price undervalues the plantation group despite the family raising its stake to 47.7 per cent.
The offer was triggered after Prosper Trading Sdn Bhd, jointly controlled by Tee Kim Tee and Tee Cheng Hua, acquired 28.19 million shares, or a 13.4 per cent stake, from Great Eastern Life Assurance (Malaysia) Bhd for RM171.9 million.
The RM6.10 offer price is below United Malacca's net tangible assets of RM7.44 a share for the financial year ended 2026 and Kenanga Research's target price of RM7.00.
Kenanga Research said the offer was only 2.5 per cent above the stock's closing price, leaving limited upside for shareholders who accept it.
The firm maintained its "outperform" recommendation and RM7.00 target price.
Kenanga Reserach advised eligible shareholders to pursue a separate cash compensation scheme linked to the Tee family's earlier breach of the mandatory takeover threshold.
The scheme covers shareholders who held United Malacca shares as at Sept 26, 2024, and sold them between Sept 26, 2024 and Oct 9, 2026, at below RM6.10 a share.
Eligible shareholders may receive the difference between their disposal price and RM6.10 a share. Shares sold above RM6.10 do not qualify.
The scheme closes on Dec 17, 2026.
The compensation follows the Tee family's collective shareholding crossing the 33 per cent mandatory takeover threshold on Sept 26, 2024, when it held 33.7 per cent.
The family said it had crossed the threshold unknowingly and intends to regularise the matter through the compensation scheme.
Meanwhile, Kenanga Research's positive outlook on United Malacca is supported by the potential contribution from maturing Indonesian estates, the company's net-cash balance sheet and its capacity to sustain dividends.
The firm expects crude palm oil (CPO) prices to remain elevated over the next six to 12 months, supported by the risk of a strong El Niño, tight edible oil supplies, resilient food demand and rising biodiesel consumption.
Kenanga Research maintained its CPO price assumptions at RM4,700 a tonne for financial year 2027 (FY27) and RM4,500 for FY2028.
United Malacca's core earnings per share forecasts were unchanged at 79.6 sen for FY27 and 65.1 sen for FY28. Annual dividends are projected at 30 sen and 20 sen a share respectively.
© New Straits Times Press (M) Bhd