||Bangkok Nigeria and the African Development Bank (AfDB) have agreed to review the lender’s portfolio in the country to identify


||Bangkok
Nigeria and the African Development Bank (AfDB) have agreed to review the lender’s portfolio in the country to identify bottlenecks delaying projects, as Africa’s most populous economy seeks to attract more development financing and reduce borrowing costs.
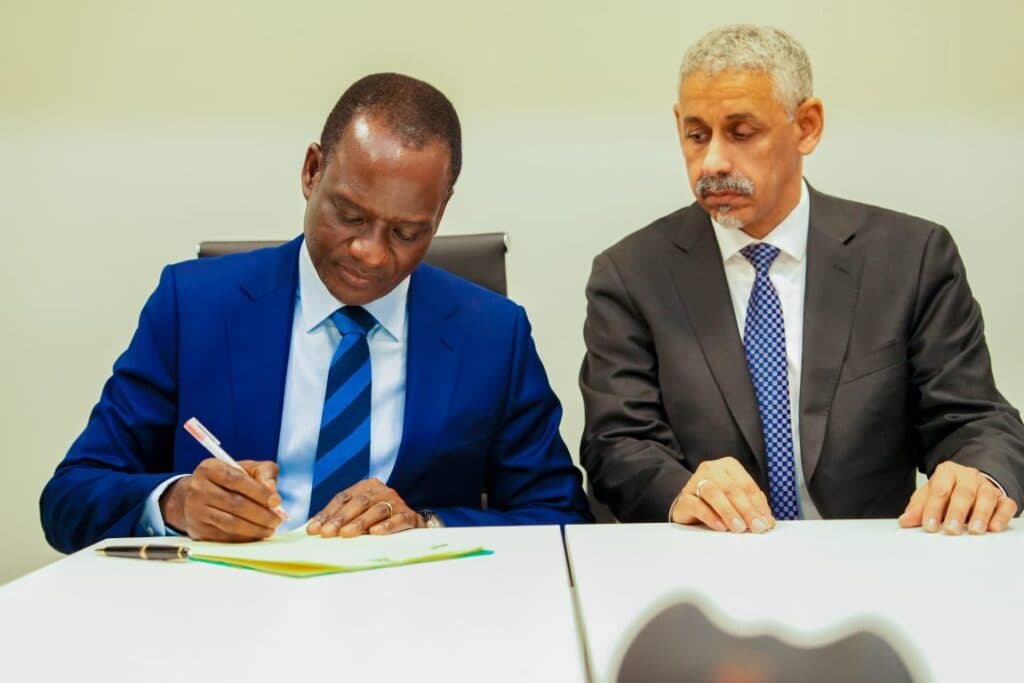
Taiwo Oyedele, minister of finance and coordinating minister of the economy, and Sidi Ould Tah, president of the AfDB, agreed to the review on Monday during a meeting on the sidelines of the 2026 IMF and World Bank Group Annual Meetings in Bangkok, Thailand.
The two sides also agreed to prepare an official visit to Nigeria by Ould Tah, during which he is expected to meet President Bola Tinubu, senior government officials and other stakeholders to discuss development priorities and cooperation with the lender.
The proposed review will assess the implementation of the bank’s ongoing projects in Nigeria, identify obstacles to delivery and align its operations more closely with the government’s economic priorities.
Read also: Nigeria seeks World Bank guarantees to unlock private investment
Oyedele reaffirmed Nigeria’s commitment to remaining the bank’s largest shareholder and meeting its capital subscription obligations, while calling for the longstanding partnership to deliver greater development financing and tangible economic benefits.
He also expressed support for Ould Tah’s four cardinal points, the bank’s strategic agenda focused on closing Africa’s financing gap, strengthening financial sovereignty, harnessing its youthful population and building resilient infrastructure through the local processing of natural resources.
The agenda, Oyedele said, aligns with Nigeria’s development priorities as the government seeks to expand investment, strengthen domestic production and create employment opportunities.
The discussions also addressed the high cost of borrowing confronting African economies, with Oyedele arguing that international credit ratings do not always adequately reflect improvements in economic fundamentals and reform performance.
Such assessments can increase borrowing costs for countries seeking funds to finance infrastructure and other development needs, potentially limiting their capacity to invest in growth.
Read also: World Bank targets $5.79bn in private investment for Nigeria
Ould Tah disclosed that the AfDB was developing a facility to provide African governments with technical and analytical support in their engagements with credit rating agencies.
The initiative is intended to help governments present credible economic data and challenge assessments where necessary, potentially improving how investors and rating agencies evaluate their economies.
The bank’s proposed support comes as African countries seek to mobilise financing for infrastructure and development while managing the cost of servicing existing debt.
Nigeria and the AfDB also discussed measures to strengthen financial integration across the continent, expand local-currency transactions and use trade insurance and credit enhancement instruments to reduce investment risks and attract private capital.
Both sides highlighted the importance of retaining skilled professionals in Africa, recognising the role of human capital in supporting productivity, innovation and sustainable economic development.
The portfolio review and preparations for Ould Tah’s visit will proceed alongside technical discussions on financing and project performance.
Related News