
Strong brands such as Tim Hortons, Starbucks and Pizza Pizza fuel steady returns for investors
See more Toronto Sun on Google — save as a Preferred Source
Subscribe now to read the latest news in your city and across Canada.
- Unlimited online access to articles from across Canada with one account.
- Get exclusive access to the Toronto Sun ePaper, an electronic replica of the print edition that you can share, download and comment on.
- Enjoy insights and behind-the-scenes analysis from our award-winning journalists.
- Support local journalists and the next generation of journalists.
- Daily puzzles including the New York Times Crossword.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account.
- Share your thoughts and join the conversation in the comments.
- Enjoy additional articles per month.
- Get email updates from your favourite authors.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account
- Share your thoughts and join the conversation in the comments
- Enjoy additional articles per month
- Get email updates from your favourite authors
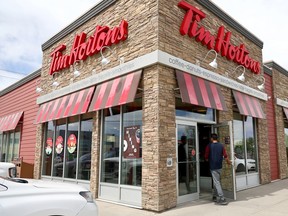
Driving around west Scarborough’s Golden Mile neighbourhood the other day, I got curious and asked myself: “How many Tim Hortons have I passed on this trip?” So I started counting: One in Eglinton Square, one inside the Rona, several blocks north of the Tims I passed on Warden Ave. south of St. Clair, the Tims in Providence Villa, another in a Petro Canada by the tall Bell communications tower, another that shares a building with Wendy’s, adjacent to a CIBC …
And it occurred to me: “Why am I not getting in on this? These guys are everywhere.”
Tims is just one example, albeit a special one on which I’ll expand later. Though they’ve underperformed this year, fast food stocks in general offer value for the defensive investor with their strong brand names, dependable revenue streams and juicy dividends. I’ve already covered McDonalds in this column, so here’s a look at some of the other top fast-food names on the stock market, and one of the biggest ones is Canadian, sort of.
Your noon-hour look at what's happening in Toronto and beyond.
By signing up you consent to receive the above newsletter from Postmedia Network Inc.
A welcome email is on its way. If you don't see it, please check your junk folder.
The next issue of Your Midday Sun will soon be in your inbox.
We encountered an issue signing you up. Please try again
(All prices from end of trading day, Oct. 23.)

Restaurant Brands International ($QSR)
Share price: $105.58
52-week price range: $89.08-$113.10
Market Cap: $36.82 billion
Quarterly dividend/Yield: $0.65/3.40%
Average analyst rating: Buy
You likely haven’t heard of this parent company, a key holding of billionaire Bill Ackman’s Pershing Square Capital Management, but you definitely know its chains: Tim Hortons, Burger King, Popeyes and Firehouse Subs.
Of those four, Tims has historically been the MVP because of its efficient business model and loyal Canadian support, despite Burger King’s vast global footprint. But the company announced in June that Burger King became the company’s top performer after second-quarter earnings, reporting $2.52 billion U.S. in revenue compared to $2.4 billion from the previous year. Tims flattened with $2.003 billion, with sales growth for the quarter down to 0.4% down from 3.9%.
Still, Tims’ name is woven into the fabric of our country’s culture and it enjoys the kind of unique brand recognition you can’t buy. And since RBI trades on the TSX, its reasonable entry point and steady dividend makes it a whopper of a candidate for your TFSA. Analysts have it going as high as $133.08 a share.

Starbucks ($SBUX)
Share price: $100.80 (U.S.)
52-week-price range: $77.99-$110.51
Market Cap: $114.91 billion
Quarterly dividend/Yield: $0.63/2.5%
Average analyst rating: Buy
The now-famous and hilarious online clip of Evan, the overwhelmed, crying Starbucks barista only makes this investment more appealing. “There are so many customers who are yelling at me!” Evan blubbers.
Are there indeed? Ought to be a good place to put my money, then, if I’m looking for a venti-sized dividend. Get to it, Evan! You don’t get paid to loaf!
You wouldn’t go wrong with that assessment, either. The Seattle coffee giant recently quelled early-stage takeover speculation of fast food giant Chipotle, to prudently invest — according to analysts anyway — in improving service, expanding its menu, intensifying its marketing and remodelling its stores as competitors such as McDonalds and (guess who?) Tim Hortons continue to creep into its market share. Analysts like the company’s direction, giving it a high estimate of $141 a share.

Yum! Brands Inc. ($YUM)
Share price: $149.71 (U.S.)
52-week-price range: $134.26/$170.14
Market Cap: $40.85 billion
Quarterly dividend/Yield: $0.75/2%
Average analyst rating: Buy
The world’s second-largest restaurant firm by dollar sales ($68 billion at the end of 2025), Yum’s portfolio includes KFC, Taco Bell, Habit Burger and up until recently, Pizza Hut, which Yum sold to private equity firm Longrange Capital and Yum China Holdings Inc. for a combined $2.7 billion. Morningstar analysts say Yum has benefitted from tech investment, with 4.9% system sales growth over seven years even as international competition intensifies. Despite the growing number of rivals, the Colonel remains a force to be reckoned with.
Analysts expect Yum to intensify its move toward a fully integrated tech platform: kiosks, digital menu boards, AI personalization for its loyalty programs, digital upgrades in its kitchens and more incentives to engage customers. Analysts think Yum! could reach $190 a share.
Pizza Pizza Royalty Corp. ($PZA)
Share price: $10.53
52-week price range: $10.10-$16.73
Market Cap: $259.23 million
Monthly dividend/Yield: $0.07/7.69%
Average analyst rating: Hold
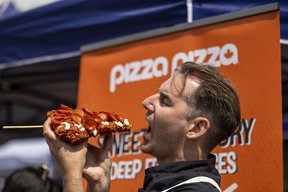
It’s midnight in downtown Toronto in November, you’ve just finished a night down the boozer with your buddies. You’re tipsy, you’re freezing, you’re starving. Who’s there for you? Who has always been there for you, with their bright orange signage, blast of pizza oven heat as you walk in the door, comforting scents of baking cheese and crisping pepperoni and irresistible creamy garlic dipping sauce? That’s right, this Canadian icon.
There are plenty of options for your pizza-purchasing dollar, but Pizza Pizza has stood the test of time since 1967. And you can own your piece of the pie for less than the price of a 10-slice large. With a reasonably safe and monthly dividend, it could be a great way to turbocharge a TFSA. Morningstar analysts believe there’s a real deal here, saying Pizza Pizza is going undervalued by at least 20%. It estimates its fair value ought to start near $13.
Disclaimer: The information contained in this column is for informational purposes and is not intended to be investment advice or an offer or recommendation to buy or sell any security. Brian Towie is not a certified financial adviser and encourages readers to do their own diligence before investing their money.
RECOMMENDED VIDEO

Join the Conversation

This website uses cookies to personalize your content (including ads), and allows us to analyze our traffic. Read more about cookies here. By continuing to use our site, you agree to our Terms of Use and Privacy Policy.