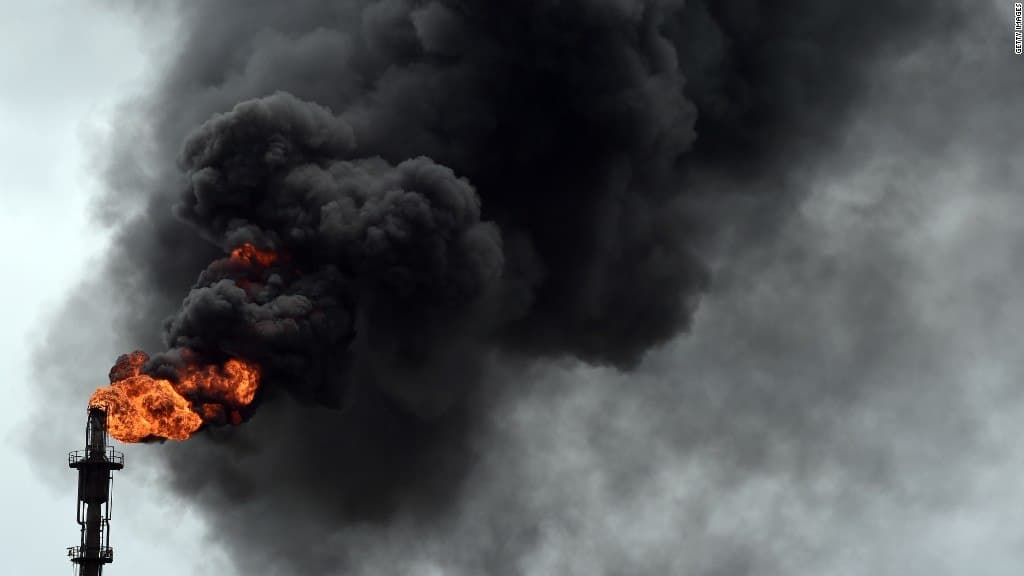
Nigeria’s oil sector experienced a loss of $230 billion and $235 billion owing to its inability to quickly enact a bill that was intended to draw in billions of dollars in investment.
- Nigeria lost approximately $230-235 billion due to the delayed passage of the Petroleum Industry Bill, which discouraged investments in the oil sector.
- Former Senate President Ahmad Lawan revealed these losses, highlighting that investors preferred other oil-producing countries with clearer regulations.
- The Petroleum Industry Act was finally passed in August 2021 after collaborative efforts between the legislative and executive branches overcame prior disagreements.
- The uncertainty caused by the lack of a predictable legal framework resulted in annual losses of about $15 billion in potential investments.
This information was disclosed by the country’s former Senate President Ahmad Lawan, who noted that he and the former Speaker of the House of Representatives, Femi Gbajabiamila, experienced significant delay when they presented the Petroleum Industry Bill to Nigeria’s ex-president, Muhammadu Buhari.
The former Senate President emphasized that Nigeria forfeited a substantial portion of its projected capital inflows, as investors redirected their funds toward rival oil-producing nations amidst legal and regulatory uncertainty.
The Petroleum Industry Act, which was eventually passed in August 2021, was enacted because of the alignment between the legislative arm of the government and the executive, as previous attempts to pass the bill were hindered owing to disagreements between both branches.
What the former Nigerian Senate President said
“We decided that having seen the failures of the solo efforts by the executive arm of government twice, and the failure of the legislature’s solo effort, we needed to bring everybody together around a roundtable,” Lawan said, as seen in the Punch Newspaper.
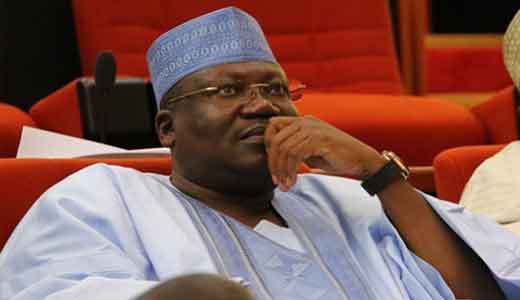
“The legislature and the executive arms would start the process together, create a framework, and work from the beginning to limit areas of disagreement and contention,” he added.
The former Senate President’s revelation, seen by the Punch in an interview published in the fifth-anniversary special edition of the Nigerian Upstream Petroleum Regulatory Commission’s in-house magazine, The Upstream Gaze, also showed that he and Gbajabiamila approached the country’s previous president after the inauguration of the Ninth National Assembly in 2019.
“So, the Speaker at the time, Femi Gbajabiamila, and I approached the President. We told him we wanted to pass the PIB, but we wanted to avoid the hurdles, mistakes, challenges, and misunderstandings that the PIB had suffered previously. We told him we wanted a joint effort from the beginning.”
DON’T MISS THIS: Africa’s largest refinery now supplies more than twice Nigeria’s total petrol imports
Although both branches collaborated on the initial framework, Lawan noted that lawmakers still reviewed and modified several provisions once the proposal reached the National Assembly.
He highlighted the high economic cost of these delays, pointing out that the absence of a predictable regulatory regime discouraged foreign oil firms and other investors from putting capital into Nigeria.
Following more than a decade of unsuccessful efforts to overhaul Nigeria's petroleum laws, the Senate ultimately passed the PIB in July 2021, and President Buhari signed it into law in August of that year.
“They were not sure why they should invest in Nigeria’s oil and gas industry when there was no certain legal framework to protect their investments. Therefore, they preferred to take their investments to competing regions such as Angola,” he said.
“We were losing about $15bn every year in funds that could easily have been invested in Nigeria. Cumulatively, Nigeria lost investments worth about $230bn to $235bn over the years because of the lack of passage of the Petroleum Industry Bill. We also lost revenues,” he added.
Furthermore, the former Senate President cited the 2019 amendment to the Deep Offshore and Inland Basin Production Sharing Contracts Act as further evidence of the substantial financial losses Nigeria sustained as a consequence of outdated legislation.