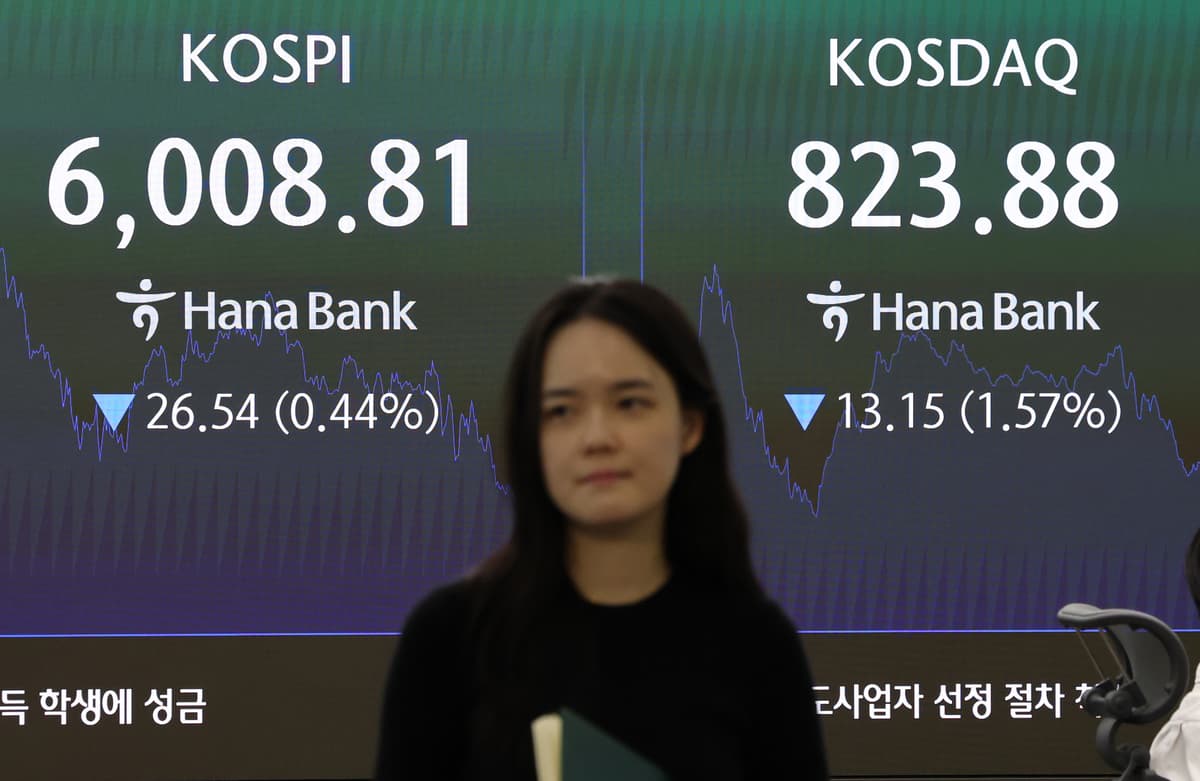
South Korean stocks, which barely closed above the 6,000 mark the previous day, tumbled in premarket trading on the 15th as a U.S. inflation shock and mounting concerns over debt tied to artificial intelligence infrastructure weighed on sentiment. Samsung Electronics (005930.KS) and SK hynix (000660.KS) each fell more than 6%, slipping to the 210,000 won and 1.3 million won ranges, respectively, while other large-cap shares weakened across the board. With macroeconomic uncertainty resurfacing, worries about returns on capital spending that have hit global technology stocks are spreading quickly to the Korean market.
Samsung Electronics and SK hynix were both down more than 6% in premarket trading, according to Nextrade data on the 15th. SK Square (402340.KS) and Samsung Electro-Mechanics (009150.KS) opened more than 7% lower, signaling a sharp chill in investor sentiment. If the regular session also ends lower, the KOSPI will post a seventh consecutive daily decline — its first such streak in about two years and one month, since Sept. 3-11, 2024.
On Wall Street overnight, credit and profitability risks across the AI value chain came to the fore. Borrowing costs surfaced as a concern after the yield on corporate bonds issued by CoreWeave, an AI-focused cloud company, to fund data center expansion approached 15%, highlighting the firm's heavy debt load. Its shares sank 15.46%. Tesla Chief Executive Elon Musk also pointed to debt risks, adding to market unease.
A warning from research firm Gartner accelerated the selling. Gartner projected that cumulative investment in AI infrastructure will reach $7 trillion between 2026 and 2030, while data center revenue will total only $3.6 trillion, leaving as much as $3.5 trillion in investment assets at risk of impairment. Amid pessimism that more than 80% of neocloud providers will fail to become self-sustaining, semiconductor value chain stocks slid broadly, including Nvidia (-3.2%), Micron (-4.1%) and SK hynix's American depositary receipts (-4.02%).
Concerns about monetary tightening also resurfaced after the U.S. consumer price index rose 3.7% in September from a year earlier, exceeding market forecasts of 3.6%. After the Federal Reserve's Beige Book confirmed the impact of surging oil prices, with West Texas Intermediate crude at $95.10 a barrel, the implied probability of an October rate increase at one point topped 50%. The macro backdrop remains clouded, with the 10-year U.S. Treasury yield hovering in the high 5.1% range and the dollar index climbing as high as 102.94 during the session, an 18-month peak. Anthropic's third-quarter revenue of $16.8 billion, up 46% from the previous quarter, showed that end demand remains intact, but analysts said that was not enough to reverse sentiment after a period of overheating.
Brokerages said the yardstick for assessing the AI investment cycle has shifted from capital spending competition to actual cash flow and funding stability. Analysts pointed to TSMC earnings due during the session and the market's ability to hold its previous low as the key tests for whether the short-term selloff will abate. "There are limits to reversing the trend on bargain hunting alone," said Han Ji-young, an analyst at Kiwoom Securities. "But in past cases following five or more consecutive sessions of sharp losses, the market has tended to confirm a bottom and revert to the mean rather than stage a V-shaped rebound, so whether downside resistance holds near the previous low will be the main point to watch."
