
Chart of the Week: Accepted SONAR Tender Volume Index, SONAR Tender Rejection Index SONAR: ASTVI.USA, STRI.USA
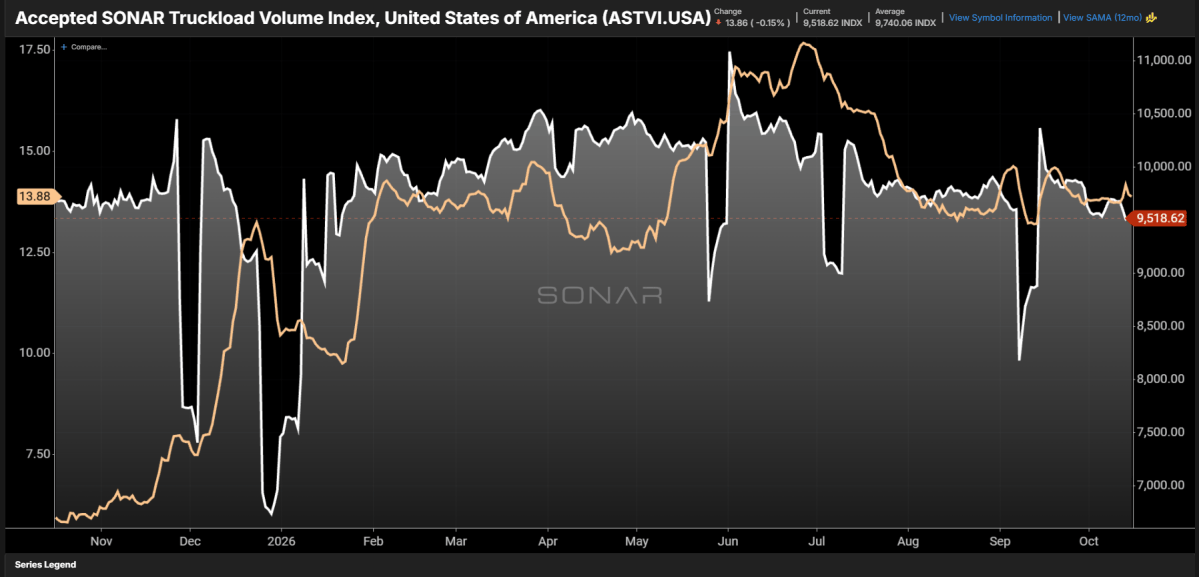
The truckload market is heading into the holidays with almost no slack. The Accepted SONAR Truckload Volume Index (ASTVI), which measures only the loads carriers accept, has fallen more than 4% over the past four weeks to 9,518. That’s its lowest level outside a holiday week since January. Normally, a drop like that would give carriers room to breathe. Instead, the national rejection rate (STRI) has barely moved and is holding near 13.9%.
A year ago, the market entered peak season with rejections under 6%, and the ASTVI was roughly 2% higher. That suggests the market has regained little, if any, efficiency over the past year.
Fewer accepted loads after 11 months of elevated rates is not what many expected. In the early phase of COVID, carriers appeared to hit their limit with the ASTVI around 11,500 in the fall of 2020. Rejection rates were near 25%, a sign that demand was well beyond what carriers could handle.
By the spring of 2021, carriers were accepting more than 10% more loads, even with rejection rates still elevated. That market was certainly tighter than today’s. Even so, most would expect accepted volumes to have improved by now after months of elevated rates.
A supply-led cycle
The two cycles differ in several ways. The biggest difference is that the COVID cycle was driven more by rising demand than by falling supply. Tender volumes rose nearly 50% year over year from September 2019 to September 2020, and accepted volumes rose 20%. That surge quickly used up all the slack in what had been an oversupplied market.
The current cycle seemed to appear almost out of nowhere. It first showed up during the 2025 holiday season, when rejection rates and spot rates ran well above the previous three years. Many still questioned it, because trucking demand was actually weaker.
Winter Storm Fern in late January was the second catalyst. It pushed tender rejections and spot rates higher, and neither has meaningfully retreated since. Again, demand wasn’t the driver; limited capacity was.
Barriers to entry
The other major difference from the last inflationary cycle is that barriers to entry are much higher now. English language proficiency enforcement, stricter rules on non-domiciled CDLs and tougher immigration policies are keeping a large pool of potential drivers out of the industry.
The Montgomery v. Caribe ruling has an indirect effect on drivers, because brokers are now less likely to use carriers with poor safety records. As of this past summer, close to 2% of carriers with substandard safety scores had been removed from service, according to GenLogs.
Rising costs
Diesel prices have spiked at times, making it hard for smaller carriers to manage cash flow.
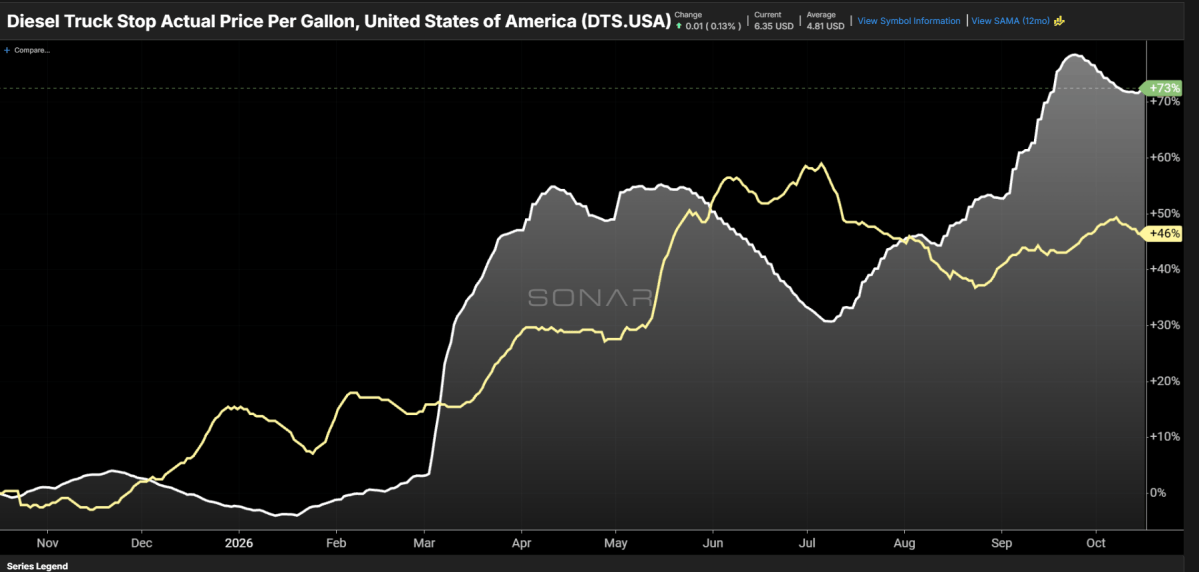
Retail diesel prices are up 73% year over year. Dry van spot rates are up a still-impressive 43%, but they haven’t kept pace with fuel over the past few months. That gap squeezes carrier profitability, a pressure that was largely missing in the COVID era, when diesel prices actually fell in 2020.
Carriers that made it through the difficult stretch from mid-2022 to late last year are hesitant to invest in growth. Borrowing costs are much higher, and the low-cost government lending that helped carriers during COVID isn’t available. Supply always moves more slowly than demand, and it now faces more headwinds than in any recent cycle. Even with economic concerns, transportation procurement teams should prepare for a market that stays tighter for longer, into 2027.
About the Chart of the Week
The FreightWaves Chart of the Week is a chart selection from SONAR that provides an interesting data point to describe the state of the freight markets. A chart is chosen from thousands of potential charts on SONAR to help participants visualize the freight market in real time. Each week a Market Expert will post a chart, along with commentary, live on the front page. After that, the Chart of the Week will be archived on FreightWaves.com for future reference.
SONAR aggregates data from hundreds of sources, presenting the data in charts and maps and providing commentary on what freight market experts want to know about the industry in real time.
The FreightWaves data science and product teams are releasing new datasets each week and enhancing the client experience.
To request a SONAR demo, click here.
The post No signs of truckload capacity recovering appeared first on FreightWaves.