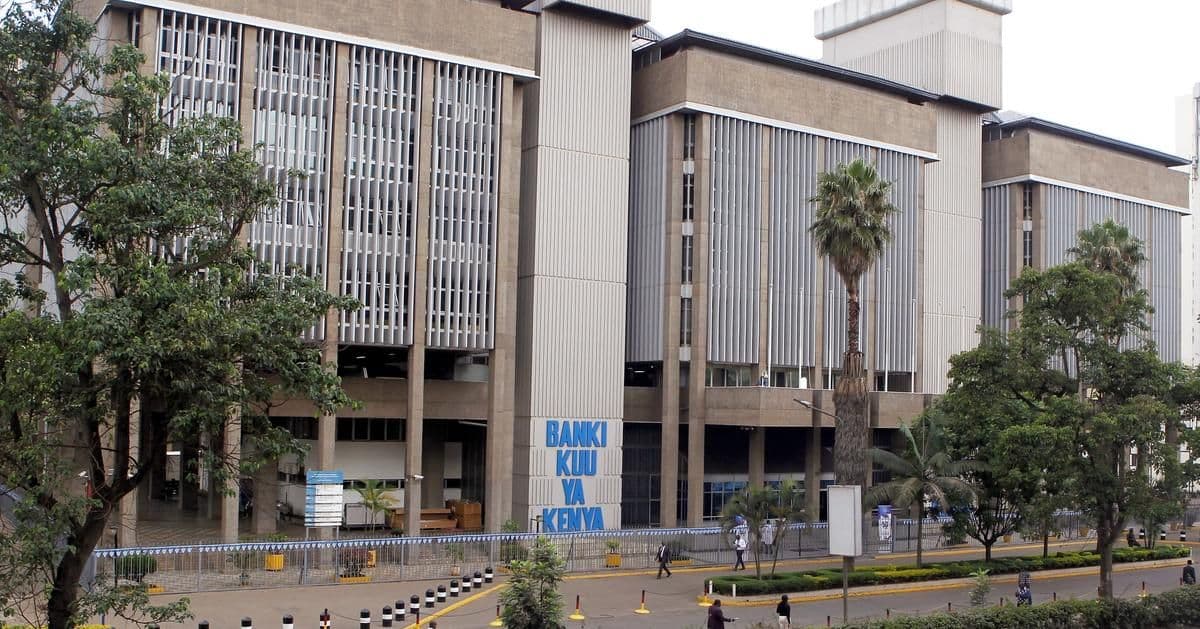
Kenyan banks have lost ground in Africa’s banking rankings after the shilling’s appreciation against the US dollar in 2024 gave way to a period of relative stability, removing a currency-driven boost that had helped lift their position against continental rivals.
The latest ranking by The Banker, a publication owned by the Financial Times, features no Kenyan lender among Africa’s 10 highest movers, compared with four in the previous edition: KCB Group, Co-operative Bank, Equity Group and NCBA. The decline comes even as most Kenyan lenders recorded growth in Tier 1 capital, assets and pre-tax profits, suggesting that currency movements and competitors’ expansion have played a significant role in reshaping the comparison.
The Kenyan shilling traded within a narrow range of approximately KSh129.00 to KSh129.92 against the dollar over an extended period. Its stability followed a sharp appreciation in 2024, when the stronger currency increased the dollar value of Kenyan banks’ reported financial positions.
According to The Banker, the absence of a comparable currency gain in the latest reporting period allowed lenders in other African markets to move ahead, particularly where local currencies strengthened against the dollar or banks raised additional capital.
Why Kenyan banks fell behind in Africa’s rankings
The ranking illustrates how exchange rates can influence comparisons between banks operating in different economies. Financial institutions report their results in local currencies, but an international ranking must translate key figures into a common currency to compare their relative size.
When the shilling strengthens, the dollar value of a Kenyan bank’s capital and assets rises even if the underlying amounts in shillings remain unchanged. When the currency stabilises, that source of additional dollar-denominated growth disappears, leaving Kenyan lenders more exposed to the performance of their balance sheets relative to competitors.
This distinction is important because a lower ranking does not necessarily mean a bank has lost capital, reduced lending or suffered weaker profitability. The latest report says all but Standard Chartered Bank Kenya recorded increases in Tier 1 capital, assets and pre-tax profits, although Standard Chartered’s capital position declined.
The Banker Top 1000 World Banks ranking uses Tier 1 capital as its principal measure of bank size, while other assessments consider profitability, efficiency, asset quality, liquidity and returns. These measures provide different perspectives on financial strength, and a bank’s position can vary depending on which one is being assessed.
Kenyan lenders also lost representation among Africa’s five highest-return-on-assets banks. ROA measures how efficiently a bank generates earnings from its asset base, making it distinct from a ranking based on capital. The reported decline warrants closer examination of margins, operating costs, loan-loss provisions and non-interest income before it can be attributed primarily to narrowing interest spreads.
KCB and Equity grow despite losing ground
KCB Group and Equity Group both fell two places in the African rankings, to 15th and 17th respectively, according to the supplied ranking figures. Their global positions improved, however, with KCB moving from 590th to 542nd and Equity from 590th to 573rd.
Their first-half 2026 results provide further evidence of the growth taking place within Kenya’s banking sector, although those results cover a different reporting period from the financial data underpinning the ranking.
KCB reported total assets of KSh2.299 trillion at the end of June 2026, an increase of 16.8%. Customer deposits rose 15.1% to KSh1.711 trillion, while gross loans increased 14.2%. The bank also reported a reduction of KSh17.3 billion in gross non-performing loans, easing one source of pressure on its balance sheet.
Equity Group reported KSh45.5 billion in first-half profit after tax, alongside deposits of KSh1.59 trillion and total assets of KSh2.16 trillion. Deposits increased 21%, while net loans grew 19%, reflecting continued expansion in its lending and funding operations.
The wider listed banking sector also delivered stronger earnings. Nine of 11 Nairobi Securities Exchange-listed lenders that had released their results recorded combined net profit of KSh144.9 billion, up 16.9% from KSh124 billion in the comparable period a year earlier.
Lower funding costs and improving asset quality helped support earnings. These results do not directly explain the earlier ranking movements, but they reinforce the need to separate domestic financial performance from changes in international standing.
Nigerian banks gain from a capital-raising drive
Banks in Nigeria, Egypt and Morocco gained ground in the continental comparison as currency movements and stronger capital positions changed the competitive landscape.
Nigeria provides a particularly clear example of how regulatory intervention can influence rankings. Following the naira’s sharp devaluation from 2023, the Central Bank of Nigeria increased minimum capital requirements for commercial, merchant and non-interest banks in March 2024. Lenders were required to raise additional equity, change their licence status or consider mergers where necessary to meet the new thresholds.
The resulting capital-raising activity strengthened the position of several Nigerian institutions in dollar terms. The Banker reported that Tier 1 capital across the country’s banking sector increased by 36% in dollar terms during the period under review, with Stanbic IBTC Holdings, Standard Chartered Nigeria and Access Holdings among the largest overall gainers.
The increase reflects a combination of additional capital and currency effects. It also shows why a ranking can change substantially when banks raise equity to meet regulatory requirements, even when the effects on lending, profitability and operational efficiency take longer to emerge.
Access Bank and Zenith Bank have also expanded their Kenyan presence through acquisitions. Access Bank acquired National Bank of Kenya from KCB Group, while Zenith Bank acquired Paramount Bank to establish a foothold in the market. Their progress illustrates the growing reach of Nigerian banking groups and the competition Kenyan lenders face from institutions seeking to expand across the continent.
Foreign lenders deepen their presence in Kenya
Kenya remains an important destination for international banking groups seeking access to East African customers and businesses. Fourteen of the banks ranked among Africa’s top 25 lenders reportedly have a presence in the country, underlining the attraction of its banking market and its position as a regional commercial centre.
South African groups feature prominently in the continental rankings. Standard Bank Group retained its position as Africa’s leading bank, with Stanbic Bank operating in Kenya. Absa Group ranked third, while Nedbank ranked fifth and Bank of Africa and Egypt’s Commercial International Bank also featured among the leading institutions.
Nedbank’s acquisition of a controlling 66% stake in NCBA, completed in October 2026, adds another dimension to this competition. The transaction gives the South African lender an established Kenyan banking platform and access to NCBA’s operations across East Africa and other African markets.
The deal reflects the value of acquiring an existing customer base, distribution network and regional operating structure rather than building a presence market by market. However, the acquisition should be viewed as a development in the ownership of Kenya’s banking sector, not as a cause of the ranking changes calculated using earlier financial results.
The interest from foreign lenders also presents a contrast. Kenya attracts international groups because of its established banking infrastructure and regional reach, yet Kenyan-owned lenders have found it more difficult to build comparable operations in Southern and Western Africa. Their smaller capital bases can constrain the size of acquisitions they can finance and the losses they can absorb while entering unfamiliar markets.
The challenge of building bigger African banking groups
Kenyan banks have expanded into neighbouring countries, where their technology platforms, established products and experience serving customers with limited access to formal financial services have provided opportunities for growth. Markets such as the Democratic Republic of Congo and South Sudan can offer higher margins, but those returns come with currency, political and operational risks that can make expansion more difficult.
Building a larger regional bank therefore requires more than growing assets at home. Lenders need sufficient capital to support overseas operations, manage regulatory requirements across jurisdictions and withstand losses in markets where political or economic conditions can change quickly.
The domestic market also presents balance-sheet risks. Moody’s has reported that Kenyan banks held government securities worth 1.7 times their equity at the end of December 2025. That exposure ties part of the sector’s financial position to the government’s creditworthiness and financing needs, even as banks benefit from strong earnings and improvements in bad loans.
Capital allocation will remain part of the debate as regulators consider how banks balance shareholder distributions with the need to retain earnings. Strong profits can support expansion, but the amount available for investment depends on capital requirements, credit losses and other demands on bank balance sheets.
The latest rankings place these competing forces into perspective. Kenyan lenders continue to expand their assets and generate stronger earnings, while rivals in other markets have benefited from capital injections, currency movements and acquisitions that increase their reach. The shilling’s stability has removed one source of comparative growth, leaving underlying financial performance and the ability to build scale across borders more important to their position in Africa’s banking industry.
Go to TECHTRENDSKE.co.ke for more tech and business news from the African continent and across the world.
Follow us on WhatsApp, Telegram, Twitter, and Facebook, or subscribe to our weekly newsletter to ensure you don’t miss out on any future updates. Send tips to editorial@techtrendsmedia.co.ke