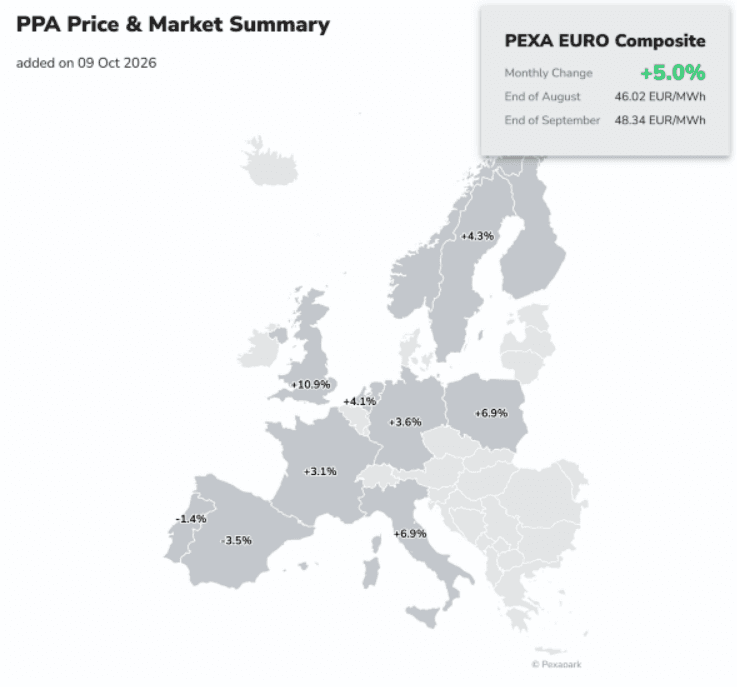
European PPA prices rose 5% in September, driven by higher forward electricity and gas prices, while Spain and Portugal recorded declines. Contracting activity rebounded, with 25 deals totaling 1.2 GW, alongside growing interest in hybrid PPAs and battery storage agreements.
Swiss consultancy Pexapark’s EURO Composite Index rose 5% in September, driven by higher forward electricity prices across most European markets. Rising gas prices pushed up power purchase agreement (PPA) fair values, although calibration adjustments also contributed to the increase.
Great Britain recorded the largest monthly increase, at 10.9%, followed by Italy and Poland (6.9% each), the Nordic countries (4.3%) and the Netherlands (4.1%). Germany and France posted increases of 3.6% and 3.1%, respectively. The Iberian Peninsula was the exception, with PPA prices falling 3.5% in Spain and 1.4% in Portugal.
Pexapark also recalibrated PPA fair values in Denmark after buyers increased the risk discounts applied to their pricing. The adjustment reduced 10-year baseload values for contracts starting in 2028 by approximately €5 ($5.6)/MWh, although an upward revision to capture curves partially offset the impact on pay-as-produced PPAs.
In Poland, an update to the hourly forward price curve increased the additional value available to solar PPAs paired with battery energy storage systems (BESS).
PPA contracting activity recovered after the summer slowdown. A total of 25 agreements representing approximately 1.2 GW of announced capacity were disclosed in September, compared with 14 contracts totaling 335 MW in August.
Corporate buyers accounted for 21 agreements and nearly 1.1 GW, representing 92% of the announced capacity. One of the largest deals was Google’s 22-year, 507 MW agreement supporting the extension of operations at Finland’s Loviisa nuclear power plant.
Onshore wind slightly exceeded solar PV in contracted capacity, with 281 MW and 276 MW, respectively. Solar projects paired with BESS accounted for an additional 167 MW.
Italy led in the number of agreements, with seven deals, including six small-scale, on-site self-consumption PPAs and Amazon’s virtual PPA covering 156 MW of capacity at the Big Fish agrivoltaic project in Sicily.
Flexible deals gain momentum
Flexible power agreements (FPAs) also gained momentum in September, with 16 deals announced across Europe, representing approximately 2.1 GW and 4.7 GWh of contracted capacity. This was more than double the 869 MW and 2.4 GWh recorded in August.
Four tolling agreements accounted for 925 MW, including a 10-year, 400 MW contract between Statkraft and Greenvolt, described as the first of its kind announced in Poland.
Agreements featuring revenue floors and profit-sharing mechanisms covered 548 MW, while merchant structures with revenue sharing accounted for just 80 MW, indicating a growing preference for revenue hedging.
Hybrid PPAs also gained traction, with three agreements announced in September, the highest monthly total to date. The third quarter also marked a record for these structures.
Zelestra signed a hybrid PPA with German steelmaker Salzgitter covering electricity from 147 MW of solar capacity and a 79 MW/237 MWh battery system charged exclusively by the solar plants. The agreement reflects growing interest among industrial electricity consumers in using storage to provide a more reliable renewable energy supply.
Other notable deals included Statkraft’s agreement with Wattmanufactur in Germany and Shell’s PPA for Abei Energy’s Arcos de la Frontera project in Spain. Both involve structures combining solar generation with storage optimization.
This content is protected by copyright and may not be reused. If you want to cooperate with us and would like to reuse some of our content, please contact: [email protected].