[SINGAPORE] The Asean Power Grid (APG) has immense potential as a regional growth catalyst, but the bloc faces a critical window of opportunity to agree on standards and frameworks that can actually turn vision into action.
The APG was conceived back in 1997, under the Asean Vision 2020 blueprint, which identified linking up member states’ electricity networks as a way to strengthen energy security and economic integration.
While the vision languished for many years, 2026 has been a turning point. The outbreak of the US-Iran war in February, combined with South-east Asia’s soaring energy requirements and need to decarbonise, have created a compelling business case for regional clean energy trade.
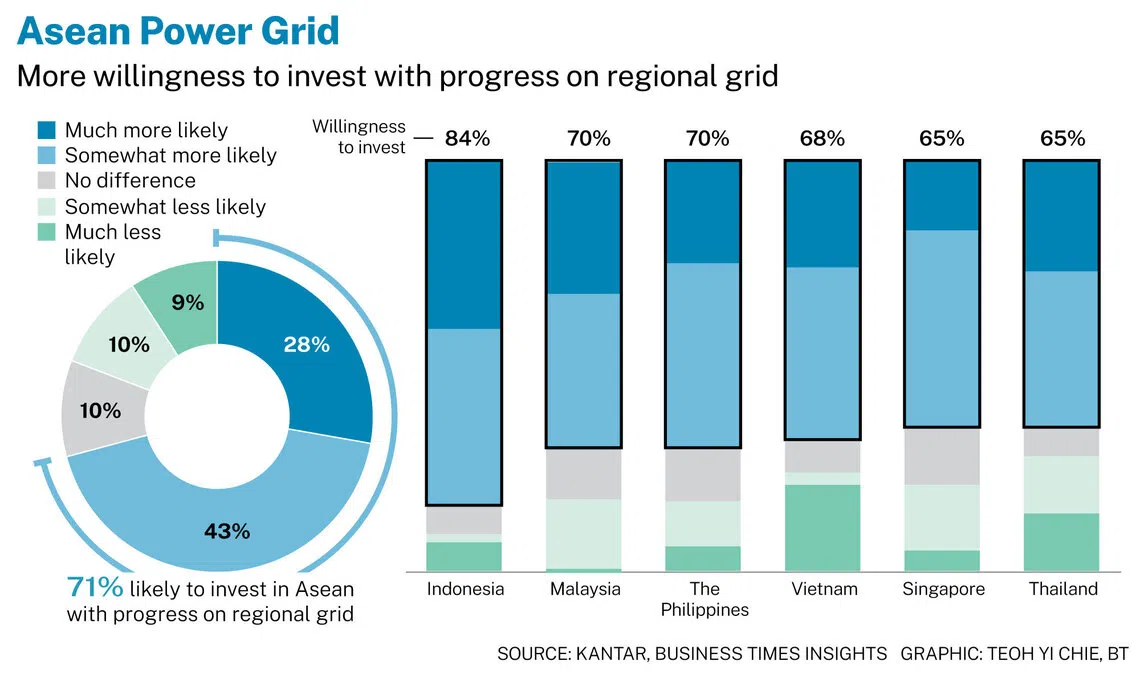
Many are bullish on the APG as a growth catalyst, according to The Business Times Insights: Powering Asean’s Future 2026, a poll of 514 regional business leaders released by BT on Monday (Oct 12).
Over 70 per cent of respondents said that meaningful progress on the APG would increase their willingness to invest and expand within the region.
Such optimism was strongest among Indonesian businesses at 84 per cent, followed by companies from the Philippines and Malaysia at 70 per cent each.

THE BUSINESS TIMES INSIGHTS
Powering Asean's Future 2026
Find out how enterprises are navigating power constraints and sustainability targets
ACCESS THE INSIGHTS
However, the APG still lacks the regulatory clarity that can make projects bankable.
For instance, even though Singapore has granted conditional licences to six projects to import clean power from Indonesia, regulatory hurdles have led to delays.
Specifically, Jakarta’s licensing rules require power exporters to renew their permits every five years – an overly tight renewal timeframe that does not provide banks and investors the confidence they need to finance these projects.
SEE ALSO
More
Other gaps that need to be fixed include the lack of an enforceable electricity-trade agreement between governments, and uncertainty over how renewable energy certificates can be recognised across borders, based on a September report by the Singapore Sustainable Finance Association.
A recent Wood Mackenzie report forecast that Singapore is set to fall short of its target to import 6 gigawatts of low-carbon electricity by 2035, despite the Republic having granted conditional approvals and licences to multiple projects.
Speed is critical
Having regional agreements that lay the foundation for future projects will be critical, and speed will have to be a priority.
Every year of delay on the APG beyond 2035 will cost the region US$2.6 billion, said energy think tank Ember.
That said, each government will still have to balance its ability to export clean energy with its own people’s ability to access reliable and affordable power.
Laos, for instance, faces a tension between its ambition to be the “battery of South-east Asia” with its hydropower exports and the reality that its own people are facing frequent blackouts.
Cautious of such risks, Indonesia in September said that it would hold off on an APG deal until the terms are “win-win”, indicated regional media reports.
It is also worth noting that even if two countries reach an agreement on electricity trade, they would still have to secure buy-in from any third-party countries that the electricity has to be transmitted through.
This was seen in the Laos-Thailand-Malaysia-Singapore Power Integration Project (LTMS-PIP).
Launched in 2022, the project involves exporting hydropower from Laos to Singapore. But its renewal in 2024 became stuck on disagreements over how the energy will be transmitted through Thailand and Malaysia, which were resolved only in January this year.
Small steps forward
Sentiment over the near-term prospects for the APG is mixed.
In the BT Insights survey, 80 per cent of Vietnamese businesses expect meaningful progress in the next three to five years, but firms in the Philippines and Malaysia are more cautious, at just 54 per cent each.
Some industry players recognise the challenge of a regionwide consensus, and are calling for smaller steps forward instead.
For instance, OCBC group chief sustainability officer Mike Ng sees bilateral agreements as a stepping stone.
“As we repeat this process, project by project, corridor by corridor, I personally believe that the APG will just emerge organically,” he told BT.
Nevi Cahya Winofa, renewables and power research analyst at Rystad Energy, sees Singapore’s power import projects as the key near-term opportunity.
“Successful delivery could build investor confidence and provide a model for further cross-border projects,” she said, citing the Brunei-Indonesia-Malaysia-Philippines PIP.
The clean energy access that the APG offers will also be an advantage in the artificial intelligence race.
As Sanjeev Gupta, Asean and Singapore energy leader at EY-Parthenon, noted: “The winner in AI won’t just be those with the best platforms or the technology they build; they will be the ones who (also) have access to efficient, reliable and, increasingly, clean energy.”
With the urgency from AI demand and the global energy crisis, South-east Asia is in a prime position to strike more APG deals while the iron is hot. But if this window is missed, the APG risks remaining in a state of inertia.