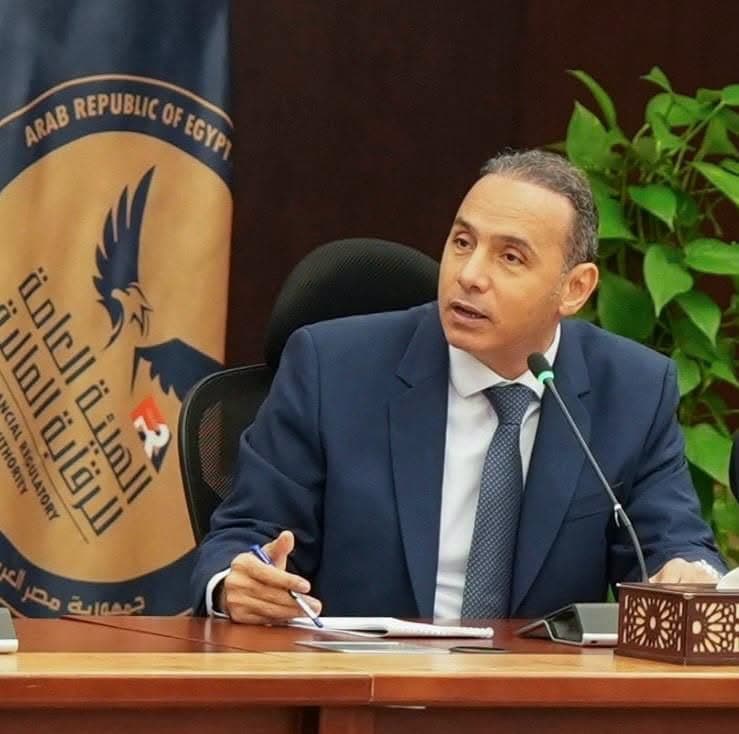
The Financial Regulatory Authority (FRA), chaired by Islam Azzam, has issued a model agreement governing the relationship between brokerage firms and clients borrowing securities for sale, marking another step towards the anticipated official launch of short selling in Egypt.
The move follows the introduction of a new regulatory framework under FRA Board Decision No. 155 of 2026.
The agreement establishes a clear contractual framework for clients seeking to borrow securities for sale through the centralised securities lending system operated by Misr for Central Clearing, Depository and Registry (MCDR), and brokerage firms licensed to execute such transactions on their behalf.
Short selling involves a lending client making securities they own available to borrow and a borrowing client borrowing those securities, selling them and subsequently repurchasing and returning them to the lender.
If the borrower expects the share price to decline, they can profit from the difference between the selling and repurchase prices, depending on market movements and changes in the security’s price. Transactions are conducted through a brokerage firm licensed to undertake such activities.
The model agreement was issued under FRA Chairperson Decision No. 3350 of 2026 following consultations with market participants to draw on the experience of companies operating in the sector and identify practical implementation requirements.
The move reflects the FRA’s approach of maintaining constructive dialogue with stakeholders to develop enforceable regulations that facilitate the mechanism’s operation while managing its risks and protecting market participants’ rights.
Agreement sets rules for collateral, fees and risk management
The model agreement defines the rights and obligations of brokerage firms and borrowing clients, their respective procedural responsibilities, and the arrangements governing expenses, commissions, returns generated from investing cash collateral margins and the distribution of those returns.
These provisions are intended to support effective implementation, improve participants’ understanding of the mechanism and its associated risks, facilitate the monitoring of collateral margins, and establish procedures for closing positions when circumstances specified in the contract or regulations arise.
The agreement also establishes risk management requirements, particularly regarding collateral provided by borrowing clients.
Borrowers must provide collateral margins at the rates specified in the agreement’s annex before executing a borrowing transaction, subject to the minimum ratios stipulated in the FRA’s decision.
Brokerage firms must deposit cash collateral into a separate account designated for securities borrowing for the purpose of selling.
To mitigate transaction-related risks and protect market participants’ rights, the model agreement requires brokerage firms to revalue borrowed securities using the latest closing price during the trading session.
Firms must also monitor the ratio of total collateral to the value of borrowed securities in accordance with the ratios specified in the agreement’s annex, subject to regulatory minimums.
The agreement also governs cases in which borrowed securities are not returned by the specified deadline. In such circumstances, the brokerage firm must purchase the securities required to fulfil the return obligation, taking the relevant settlement dates into account.
It also addresses circumstances requiring positions to be closed, including the removal of a security from the list of securities eligible for short selling and the issuance of regulatory decisions or approvals relating to acquisitions, mergers, tender offers, demergers, liquidations or other transactions specified by the FRA.
Brokerage firms must also provide clients with a detailed guide explaining securities borrowing for the purpose of selling, including its fundamental rules, procedures, benefits and associated risks.
The guide must be updated whenever amendments are made to the governing regulations and provided to clients at least once a year and whenever it is revised.
The agreement stipulates that cash collateral margins must be invested in instruments specified by the FRA throughout the lending period.
Brokerage firms are required to inform clients of the investment instruments used and the actual returns generated, and to credit those returns to clients’ accounts immediately upon receipt or in accordance with the agreed terms.
Regarding borrowing costs, the model agreement requires brokerage firms to disclose all expenses, commissions and other monetary amounts deducted from clients, specifying the basis on which each is calculated.
Any subsequent amendment to commissions or expenses is prohibited without the client’s explicit consent.
The agreement guarantees clients the right to issue orders to sell and purchase borrowed securities and to close their open positions, either fully or partially, during the borrowing period, in accordance with the contractual terms.
MCDR system undergoes live testing ahead of launch
Azzam said the model agreement represents another step towards launching the short-selling mechanism, as the FRA works to finalise the regulatory provisions and practical guidelines for all parties involved.
At the same time, final adjustments are being made to the centralised securities lending system developed and operated by MCDR through live testing.
The aim is to ensure full real-time connectivity between the system and brokerage firms while documenting all stages and procedures of the process.
The system will enable borrowing clients to view all available securities lending offers submitted by lending clients and select those that match their investment objectives. It will also allow lending clients to view other lending offers registered through the system.
Azzam added that the model agreement is intended to facilitate transactions for brokerage firms and borrowing clients, regulate their relationship and establish a standard contractual basis consistent with the mechanism’s regulatory framework.
It also defines responsibilities for managing collateral, monitoring open positions and handling cases involving declines in collateral value or delays in returning borrowed securities, thereby safeguarding the rights of all parties.
He noted that the agreement must include a declaration from the borrowing client confirming that they are the original owner and sole beneficiary of the account being opened and that their funds originate from legitimate sources.
Borrowing clients must also provide the relevant information in accordance with Anti-Money Laundering Law No. 80 of 2002 and the regulatory decisions governing anti-money laundering and counter-terrorist financing measures in non-banking financial activities.
Azzam explained that brokerage firms licensed to conduct these transactions are required to maintain the confidentiality of clients’ data and the privacy of their information and documents.
They are prohibited from disclosing information about clients or their transactions to third parties without prior written consent, and then only within the scope of that consent. Exceptions apply where firms are required to notify the FRA of specified data or information, or where disclosure is required under a judicial order in accordance with relevant legislation.
Short selling offers gains, but…
Under the short-selling mechanism, a borrowing client makes a profit if their expectation of a decline in the price of borrowed securities proves correct. The client repurchases the securities at the lower price, realises a gain and returns them to the lender, with borrowing costs deducted from the profit.
Conversely, if the price of the securities rises and the borrower decides to limit their losses, they must repurchase the securities at the higher price, incur a loss and return them to the lender, with borrowing costs adding to that loss.
In both cases, the lending client receives a return for lending their securities, comprising a return approximating the risk-free rate plus an additional lending premium, while retaining the other benefits associated with share ownership.